Powered by Blogger.

Home

Why NO Interest?

Saturday, October 7, 2006

Here is some market commentary posted on Star Biz..


Equity Market outlook
On paper, it would appear that the local stock market is headed for better times, with easing fears about higher domestic interest rates, expectations of a stronger Ringgit and the pullback in the price of crude oil, which will keep inflation fears in check.

Note the following comments...


Rumours and speculation of mergers and acquisitions (including privatisations) also appear to profligate lately, which would obviously be good for the market, especially if there is actually fire behind some of the smoke.

Lots of fantastic rumours, isn't it? Or is plain speculation?

How ironic because OUR business news is one the MAJOR sauce of distribution!!!

As an investor, would you be willing to invest in a market dominated by rumours and speculations?


But for some strange reason, these positives are not being translated into a bullish sentiment on the local bourse. On the contrary, investor sentiment appears relatively muted, at best, particularly among the retail investors (as evidenced by the relatively low daily trading volumes and the almost evenly balanced number of gainers and losers each day).


Yes... big issue isn't it?

Why isn't ppl interested in the market despite the market being at its six years high?

Oh, perhaps this six years high is a lousy indicator? What say you?

And here's more interesting comments...


Spending on consumer durables and big ticket items such as purchase of passenger cars and real estate are down year-to-date and consumer sentiment is further affected by talks of further increases in prices of basic items such as toll rates, petrol prices and food prices.

Here's the thing... if the market is so hot (at its six years high mah), why isn't the consumer spending????

I don't know... what say you?

Care to share some opinions?

Read more...

When BAD is GOOD!! (Doh!)

Thursday, October 5, 2006

Read today's FSO by Martin Goldberg. Rather interesting point. ( here )


Although the Dow is hitting all time highs in nominal dollar terms, not all of the 30 Dow stocks are in bull markets. The bull market is largely being led by the financial stocks within the 30 Dow Stocks. Some key Dow stocks are in long term technical peril in spite of a rally in the index to all time highs. Some, such as Alcoa are also in short term technical peril.

I guess you could relate that issue to those here in our Bursa, right?

Anyway, there was an interesting link in his write-up.

http://www.financialsense.com/fsu/editorials/shepherd/05/0415.html


Going into August 2004 the market was down heavily in particularly the NASDAQ which was looking at a 10% loss. This is not good just before an election, Presidents are not re-elected when the markets are falling. Everything was looking very bearish it looked like the Iraq war rally had run out of steam at exactly the wrong time for the election. We wrote about this publicly in March 2004

how?

Look at Goldberg's comments on Today's market near the end of his write-up.


Tomorrow’s jobs number will have an impact upon the bond market. With regard to the market, a “good” number will probably be a bad number. Today a couple of Fed representatives chirped about inflation and the potential for higher interest rates


SEE HOW THE BAD NUMBER IS NEEDED as more fuel to this GREAT BULL RUN?

:s54: :s54: :s54:

Read more...

Lion Deal So Good?

Wednesday, October 4, 2006

That was from the edge Weekly.

Unlocks value?

That above article does tells a lot.

1. Why this deal?


"LDHB's foray into the steel business has met with negative response from its minorities, who are in the company for its retail business. Now this issue has been addressed," says an industry observer.

See, look back at the past ( see here and refer posting dated on 22nd July).

Back as early as Oct 2004, when icap (less we forget the vested interest when icap had as early as then) first wrote on LionD, the intent from Lion Corp about its steel business via Megasteel was already there. See the problem is Megasteel was listed under LionCorp and if the LionD investors were bullish about the steel business, they would have purchased into LionCorp and NOT LionD. So it the announcement of LionD foray into the steel business was simply lacking in corporate governance. And less we not forget that the whole Lion Group restructured mainly because of too many complicated forays into too many businesses.

So they have to think of a new plan, right?

Well this is it. DO you like what you see?

2. So what's the deal?

  • Under the proposal, LDHB has valued its interests in the Parkson retail operations at RM4.3 billion. The lion's share came from LDHB's 55.5% stake in the Hong Kong-listed Parkson Retail Group Ltd (PRG), which is valued at RM4.03 billion. The remaining RM270 million is the value attributed to Parkson Malaysia's operations as well as several Parkson franchise department stores in China.

LionD is valuing Parkson Retail operations at rm4.3 billion.

Ahem. Valuation is always complicated. However, in the stock market, more often than not, earnings do matter.

So how much is Parkson retail making? These are some of the notes mentioned in LionD announcement of this deal..


PRG Corporation:

For the financial year ended 31 December 2005 and the six (6) months ended 30 June 2006, Parkson Retail achieved a consolidated profit after tax and minority interest of RMB248.0 million (RM114.1 million) and RMB196.2 million (RM90.3 million) respectively.

Parkson Malaysia:

For the financial years ended 30 June 2005 and 2006, the Parkson Malaysia Group achieved a consolidated profit after tax and minority interest of RM24 million and RM20 million respectively.

Parkson Venture:

For the financial years ended 30 June 2005 and 2006, the Parkson Venture and Serbadagang Group incurred a consolidated loss after tax and minority interest of RM2 million and achieved a consolidated profit after tax and minority interest of RM2 million.

Sea Corral:

For the financial period from 25 January 2005 (date of incorporation) to 30 June 2006, the Sea Coral Group incurred a consolidated loss after tax and minority interest of RM7 million.

Firstly, why are they NOT giving a consistent set of earning dates? Some states a half year earnings, some full year, some more than a year earnings? Why the need for such complexity?

How about we look directly into LionD books and look at what they announced in Aug 2006 earnings?
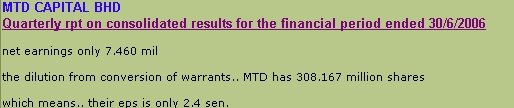
Quarterly rpt on consolidated results for the financial period ended 30/6/2006

Look under the notes worksheet, and we will see that the retailing from Parkson generated a sales revenue of 700 mil for the quarter, with a net profit of 53 million. So if we simplified it, we are looking at a business with an annualised profit of rm200 mil per year.

So based on earnings alone, LionD is hawking their Parkson group at a value of 4.3 billion.

Good SELL price for LionD isn't it? Yes?

Good BUY price for ACB, isn't it?

3. Now consider the 'as it is' balance sheet.

LionD has a net borrowings of 186.9 million and a piggy bank cash of 1018.196 million or a net cash of 831.296 million.

ACB? has debts totalling 110.215 mil and a piggy bank cash of only 2.941 million or a net debt of 107.274 million.

4. So what does the minority investor of LionD gets?


As an illustration, for one LDHB share, which currently trades at RM4.90, investors are getting 1.3 ACB shares, which works out to about RM5.10 (this is based on RM3.8 billion divided by 968.61 million shares in ACB, after ACB's capital reduction and reconstruction exercise, multiplied by 1.3). This assumption does not take into account the existing cash and liabilities of ACB.

Those comments were from the Edge article. LOL! See the last line?

Now there is such an illusion created in this picture. The bare essential one should instead focus on is that for one LionD share, the investor would get 1.3 ACB shares. But why am i saying it's such an illusion?

LionD was traded at 4.90. And it closed yesterday at 5.30. So since when the market traded price becomes a fair value for a company's worth?

And look at ACB. The writer based ACB on the purchase price of 3.8 billion of Parkson Retail Group. And again, is Parkson worth that much?

Now consider from the earnings perspective. Parkson retail should make around 200 million or so. Remember the key point is that after this exercise, ACB will have some 968.61 million shares. Which means ACB will become a stock earning some 200/968.61 = 20.6 earnings per share. So what kind of earnings multiple do you think it is fair? 15x? Too high? Or too low? Whatever the fair value earnings multiplier, multiple it by 1.3 again. What do you get? Or is my annualised earnings of 200 million to low? No problem. Readjust it yourself to say 250 million or even 300 million. And then do the same multipliers.

Oh. Another thing. LionD valuation. Does the market traded price reflects the true value of the share? What if LionD is way overly priced?

See this point posted at the other posting:
http://sahamas.net/view_topic.php?id=185&forum_id=5

Let me reproduce that one posting in the thread...

Lion Diversified posted its earnings today:

http://sahamas.net/view_topic.php?id=429&forum_id=28

This is what the company said:

  • The Group continued to post satisfactory results for the financial year ended 30 June 2006 on the back of the strong performance recorded by our retail and computer businesses. Our property development project in Cheras also posted positive contribution despite the lower billings generated during the year.

    After accounting for a gain of RM422 million arising from the disposal and dilution of Parkson China pursuant to its listing on The Stock Exchange of Hong Kong Limited and the loss incurred by an associated company due to the low international prices for steel products, the Group recorded a marginally higher profit before tax of RM606 million as compared to RM597 million registered in the previous year.

So, if you minus 422 million, earnings = 475.717 - 422 = 53.717 million.

err.. that's how much LionD made its current fiscal year!

Well catch this... Lion Div as of today... has 692,528,111 million shares!!

So how much....

  1. EPS how much?
  2. Where is the growth?

:s9:


5. How?

Think about why the need for the deal again. Look at the recent developments stated in the edge article.


Other developments
As at Sept 27, 2006, Lion Ind held a 23.89% stake in LDHB. Meanwhile, Cheng and nephew Datuk Cheng Yong Kim, in their personal capacity and through their private vehicles, have a 33% stake.
By having a direct exposure to Parkson, Cheng and Lion Ind will be in a better position to recapitalise and raise funds to beef up the group's steel operations.
Lion Ind, in particular, needs funds to meet its debt obligations. Recently, its 81%-owned subsidiary Lion Forest Industries Bhd increased a proposed cash distribution by 67% to RM420 million to channel more funds into Lion Ind (its share of the distribution is RM340.6 million) to pay off debts.
More interestingly, the demerger of the Parkson business from LDHB will help Lion Corp, which is seeking financing to expand its hot-rolled-coil steel operations, shed some of its burden. The cash-rich LDHB can now finance or undertake some of the steel projects. The RM641 million proceeds from its 10% sale of PRG could be utilised to fund the group's steel-related projects.
With the value-unlocking exercise, it is not surprising that Lion Corp's subsidiary Megasteel recently terminated a proposed undertaking to acquire the above-mentioned DRI plant from LDHB

See the game plan?

Now consider this statement...

  • "The proposal sets to unlock value for LDHB shareholders. Shareholders will have a direct exposure to Parkson through ACB while continuing to hold LDHB shares. The market will give better valuations to ACB as a pure retail play rather than lumping Parkson with the other businesses of LDHB," says Tan Teng Boo, whose closed-end fund iCapital.biz holds shares in LDHB.

LOL!!!!

Truly incredible.

So honey.... do you think I should pawn my car wash business and lump it all into LionD?

how?

Demerger is such a fancy word hor.

How about flipping the business between subsidiaries?

:s39:

So anyway, ultimately, LionD = LionD + 1.3 ACB.

Gooduh?

:s18::s18::s25::s18::s18:

ps.. I think I read it somewhere that LionD should be worth 7.80 based on net assets. Based on net assets woh. Don't you wonder why they don't base on earnings? Does earnings not matter?


Read more...

Pay Performance for Directors

Tuesday, October 3, 2006

Read this article in the Business Times: here

  • PUBLIC-LISTED companies (PLCs) should pay their directors based on their performance in order to be fair to them, the stakeholders and minority shareholders, the Minority Shareholder Watchdog Group (MSWG) said.

    "The basic rule of pay per performance should apply. If the firms are making losses, the directors should just get nominal pay," MSWG chief executive officer Abdul Wahab Jaafar Sidek told Business Times.

    If the firms are to perform well, they should also equally reward the stakeholders and shareholders, he added.

Hmmm..... extremely good suggestion in my opinion. Far too many directors do not appear to be bothered about the performance of the listed company.

The article continues by saying...

  • The MSWG is currently working on a similar salary survey that may take a few months to complete, Abdul Wahab said.One of the best ways to set the remuneration band is through key performance indicators, he said.Offering salaries based on that measure also suggests better transparency towards the minorities.The MSWG has been encouraging the PLCs to be more transparent in disclosing remunerations. It shares the same view as Bursa Malaysia Bhd's chief Yusli Mohamed Yusoff.

What say you?

Do you reckon that this is a good move?

And how about cleaning up the huge mess in the ESOS????

ps..

Let me SHOW YOU WHERE IS ZE MOOLA!!!!

back in July 2006, there was an article on Fortune stating the issue of high CEO pay. here

  • Lee Raymond$405 Million That's the 2005 comp, lump-sum pension, and current value of various stock grants with which Exxon's chief rides into retirement.
  • Bob Nardelli$250 Million The total value of the package Home Depot has paid him so far. He's collected about 30%. The rest varies with the stock price.
  • William McGuire$1 Billion UnitedHealth's CEO holds a ton of options. Alleged accounting flaws have hit the stock. But his potential reward (above) remains rich.
  • Hank McKinnell$99 Million Pfizer's CEO took heat for a hefty pension built up over many years (present value: $83 million). He earned $16 million in 2005.
  • Franklin Raines$90 Million Fannie Mae's boss made that from 1998 to 2003. But auditors now say the earnings his comp was based on were overstated by $11 billion.
  • Phil Purcell$66 Million Morgan Stanley's stock fell 25% in the past five years. Pushed out last year, he collected this amount in severance plus 2004 pay.

Read more...

Of Gamuda and the Construction Sector

Saw this article on the Edge in which Citigroup stirs up the construction section by suggesting the possibility of M&A!! ( more )

  • Citigroup Investment Research said on Oct 3 opportunities are abound as companies with low valuations may attract interest of potential suitors or partners to rise on the construction upturn. Based on a price-to-earnings ratio/price/book basis, there are several companies which look interesting. They are Road Builder Holdings Bhd, Sunway Holdings Bhd, Ranhill Bhd, WCT Engineering and MTD Capital Bhd. “These companies’ low valuations may attract the interest of potential suitors or partners to ride on the construction upturn,” it said.
And they continure by adding...
  • Another angle for M&A could be the acquisition of expertise or attractive assets. It said a focus on the Ninth Malaysia Plan (9MP) on water infrastructure could spur interest in companies with relevant expertise. “Big-cap construction companies under our coverage such as Road Builder, IJM Corporation Bhd and Gamuda Bhd, do not have major shareholders with more than a 50% holding. This could pave the way for possible mergers between these companies with suitable candidates,” it said.

Wah! As the local saying goes 'macam-macam pun boleh!' (Anyhow also can!)

Take MTD Capital.
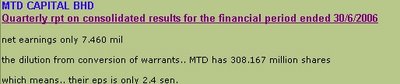
So how cheap can MTD be? Based on what? Doesn't earnings matter?

Book basis? Here's something to ponder upon. A company can have tons of contracts on their books but what good are these contracts if they cannot turn it into dollar and cents!

How?

Show Me the Moola dude!

More can be read here.

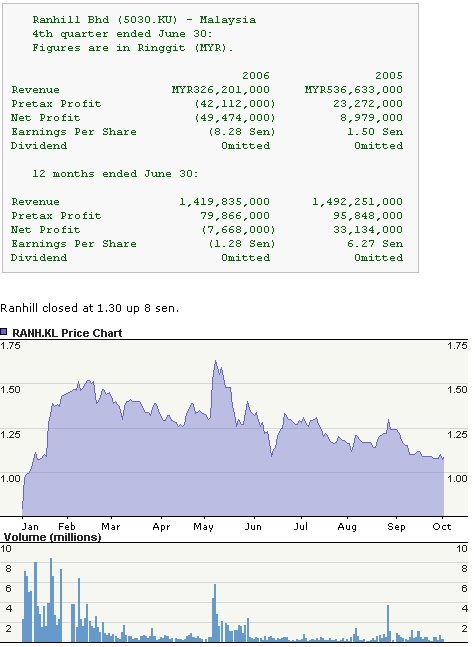
Or about Ranhill? Ranhill just registered a loss of 49.474 million for its most recent quarter.

Or how about Gamuda? Let's look at the market leader.

This one, I had a good discussion here. here

Let me reproduce it again for easy reading:

Hi Dycarr,

I do have a couple of issues I want to share with you on Gamuda.

  • Ah...Gamuda has just announced its final quarter results for 06 and it was hardly suprising with EPS for full year 22cts. :s11:. A final dividend of 9cts as per last year was declared

Let's talk about its business.

The big picture of its earnings, isn't really a pretty at all, in my opinion. (ps. let's leave the issue of the quality of the company/management etc and just talk earnings. Since after all, it's all about Gamuda and its earnings, right?)

First thing I would look at it's quarterly earnings..


Ann Date Reporting Q Revenue Profit/Lost
29-Sep-06 31-Jul-06 4 440,361 41,782
22-Jun-06 31-Jul-06 3 249,838 40,151
23-Mar-06 31-Jul-06 2 243,031 40,027
20-Dec-05 31-Jul-06 1 293,667 46,598
And as you can see it's rather flat and lacklustre.

Now Gamuda used to be a GREAT construction stock. The market leader, whose reputation was based on its stellar earnings growth per year, which saw the stock hitting its peak end 2003/early 2004 at around 8.00.


So obviously, based at current price, around 4.00, perhaps that there is some justifications that 'perhaps' the share is cheap enough or as they say, the poor/lacklustre earnings has been reflected in the stock price.

True. That's sometimes a valid justification or reasoning to bet on the stock.

But...

Perhaps it would be interesting to see what was the main driver/catalyst that drove the stock so high, and for me it was the stellar earnings growth achieved by Gamuda. The earnings really was top-class.


FY Sales Revenue
2000 637.488 146.815
2001 830.763 191.708
2002 1042.752 193.899
2003 1442.069 241.773
2004 1719.032 281.869

Based on the table above how could one argue Gamuda was no good?

And wasn't it clear how the impressive growth in earnings was probably the main cause that drove the share so high? Long term investors would have been proud.

But....

Things have changed.

The landscape has changed.

Growth as they say it's rather finite...

Now if I add in the last 2 year earnings (including yesterday earnings report), here is a different picture.

FY Sales Revenue
2000 637.488 146.815
2001 830.763 191.708
2002 1042.752 193.899
2003 1442.069 241.773
2004 1719.032 281.869
2005 1661.453 265.778
2006 1226.987 168.558

Two years of decline. This fiscal year's earning was really poor. And based on the earnings revenue of 168 million, this would put Gamuda back to the levels it achived in its fiscal year 2000.

As they say, the good times is over for now.

So perhaps it would be better to remember that the 8-ringgit-Gamuda and current Gamuda is 2 totally different animal. The 8-ringgit-Gamuda had stellar earnings growth riding on its back. The current 4-ringgit-Gamuda is riding on the back of a serious decline in its earnings. Two different animals.

And as you have said, the poor earnings is expected.

Delay in recognition of revenue of on-going projects, completion of SSP3 and the delay in NT1 Laos (which was supposed to commence 2 years ago) were partly the reasons results are weak.

And as you argued that you expect next year earnings is to pick up strongly. But where will the earnings driver come from?Moving forward, GAMUDA should resume its growth path with larger contribution from projects in middle east and NT1 Laos and its property development division. Naturally, it is also eyeing a slice of some of the targeted larger projects at home and I would be suprise if they are not successful.

Very much possible. I WON'T be a bit surprised at all.

However, I will be extremely cautious. I believe that Gamuda is paying the price of its earlier success and the issue of the size and reputation of Gamuda itself. Remember Gamuda is now really considered a five-star-construction company based on what it achieved from 2000-2004.

But....

The five-star-construction stock is simply missing the GODZILLA-sized mega, mega contracts it was enjoying back in the those days. Remember the issue of companies venturing overseas? The risks are so much more and yet these companies are willing to do so simply because the huge chunk of meat in our kampung is no longer as meaty.

And because of these reasons.. i would be cautious.

==================================

However, most research houses are still upbeat about Gamuda.

Here's JP Morgan comments

  • · The poor results for FY06 was mainly attributed to the slowdown in construction sector, which witnessed 33% drop in revenue Y/Y. The property segment remained flat, and management continues to guide for modest growth from their existing developments in Valencia, Kota Kemuning and Bandar Botanic. Growth in property will come from Bandar Nusajaya in South Johor as the pump priming projects are targeted for kick-off in CY07.
    · Management indicated that earnings growth for FY07 will be driven by the incremental orderbook from 9MP and remains optimistic of their chances to revive the double-tracking project. SAE and LDP toll concessions will still expect a toll hike soon, though timing of the implementation has yet to be finalized. All other business segments should expect a flat and stable outlook.
    · We remain OW and maintain our Aug-07 PT of M$4.80, based on a RNAV approach - valuing their normalized construction orderbook at a P/E multiple of 15x, 9MP anticipated orderbook using a DCF valuation, property earnings at a P/E multiple of 10x, and DCF valuation for the rest of their toll and water concessions. The risks to our call and target price depend on the successful implementation of 9MP and the implementation of the toll hikes.

JP Morgan remains Ove-Weight and maintains a price target of m$4.80.

CIMB has it as a TRADING BUY with a trading target price of rm4.30.

  • RM4.02 TRADING BUY Maintained Target: RM4.30
    Gamuda
    Slow and steady
    • Broadly in line. FY7/06 net profit amounted to 96% of our forecast and 97% of consensus. Topline declined by 26% but net profit slumped 37% as weaker construction margins dragged EBIT down 56% and the tax rate rose from 27% to 35% due to non-deductible expenses.
    • Dividends maintained. Despite the lower earnings, Gamuda kept its full-year DPS at 16 sen, with a final DPS of 9 sen, in line with our forecast. This translates into a decent yield of 4%.
    • Construction contraction. Construction revenue fell by 33% but its pretax profit tumbled 79%, mainly because of a 14.4% pt drop in construction pretax margin to 6.6%. Management attributed it to (i) continued glitches for the SMART project, and (ii) the completion of major contracts in 3Q06.
    • But other divisions stepped up to the plate. The water-related and highway concession division chalked up solid pretax growth of 54%, which helped to plug a big part of the hole caused by lower construction margins. The strong growth came from a 27% increase in revenue from its two Indian highway concessions and higher capacity payments for its water concession.
    • A 9MP winner? The Ninth Malaysia Plan holds much opportunity for contractors like Gamuda, particularly in the form of PFI jobs. Some of these projects entail significant engineering works, namely flood mitigation system, inter-state water transfer and railways. The revived RM14.5bn double tracking project could provide a fillip to Gamuda’s earnings if it comes through.
    • Reiterate TRADING BUY. Our FY7/07-08 earnings are adjusted upwards by 2- 3% to factor in lower tax rates while we introduce an FY7/09 forecast. However, we retain our target price of RM4.30, which is based on a 30% discount to its RNAV. The key share price catalyst would be the award of bigger jobs that enlarge its order book significantly. Since our upgrade to TRADING BUY on expectations of a bigger flow of positive news, the company has secured two projects worth RM866m, taking its order book to RM2.5bn as at July-06

RHB was more optmistic despite its cautious views with a fair value of 4.94. Note that RHB realises that Gamuda can only start booking in profits from its Nam Theun project in fy07/08.

  • Earnings To Catapult Later Than Sooner
    Share Price : RM4.02 Fair Value : RM4.94 Recom : Outperform (Maintained)
    RHB RESEARCH INSTITUTE SDN. BHD.

    X FY07/06 net profit came in within our forecast as well as the market expectation.
    X We are downgrading FY07/07-08 net profit forecasts by 38% and 17% respectively largely to reflect the management guidance that:
    1. Realistically, Gamuda can only start booking in profits from the Nam Theun 1 Hydroelectric Power Project in Laos from FY07/08 as it is unlikely to hit the first 15% billing milestone in FY07/07. We had assumed the project to start contributing in FY07/07; and
    2. Gamuda is expecting "finer" margins from its projects in Qatar due to the rising costs of bitumen, diesel and stones. Contributions are also not expected to stream in as quickly due some delays with regards to the site possession (of which Gamuda will not be held liable for LAD).
    X However, indicative fair value based on 12x forward EPS is unchanged at RM4.94 as we roll over the base year from FY07/07 to FY07/08. We believe. Gamuda’s earnings recovery is delayed, but not denied. Also, in our earning forecast for Gamuda, we assume Gamuda to secure RM1.5bn worth of new contracts per annum in CY2007-2009.
    X Against the 8MP, development expenditure in the 9MP is 17.6% higher at RM200bn, or 29.4% higher at RM220bn if RM20bn under the private finance initiatives (PFI) is included. Similarly, as compared with a year ago, development expenditure under the 2007 Budget is 24.3% higher at RM44.5bn, or 35.5% higher at RM48.5bn if RM4bn under the PFI is included. These augur well for all construction boys including Gamuda.
    X Given its strong track records and engineering capabilities in tunneling, water supply and flood mitigation works, we believe Gamuda stands a good chance of winning or at least playing a substantially role in: (1) Tunneling works for the Pahang-Selangor Inter-State Raw Water Transfer project; (2) A new railway tunnel in Padang Rengas, Perak, with an estimated cost of RM800m; (3) Construction and upgrading of water treatment plants and dams; and (4) New flood mitigation projects.
    X We like Gamuda for the following reasons:
    1. A vibrant local construction sector over the medium term on the back of the 9MP and Gamuda’s fortes in tunneling, water supply and flood mitigation works;
    2. Gamuda’s good earnings visibility underpinned by an outstanding construction orderbook of RM4bn (see Table 3) that could keep it busy for the next 2-3 years; and
    3. Gamuda has a large market capitalisation and high share liquidity, and it is an established name among the local and foreign investors. Maintain Outperform..

So was OSK who reconds that the prospects are rather exciting for Gamuda and places a value of 4.70 for it.

  • Exciting ProspectsAhead
    Below expectation. Net profit of RM169m fell short of our forecast by 10% and 8% below consensus, attributed mainly to weak construction earnings and the slowdown in property sales.
    Weaker y-o-y performance. The group revenue and operating profit were down by 26% and 53% respectively, on the back of the completion of construction works for the Sungai Selangor Supply Scheme Phase 3 ("SSP3") and the two highway projects in India.
    Revenue Op. Profit
    Better q-o-q numbers. Revenue and pretax profit were up by 76% and 29% respectively underpinned by higher contributions from property water and expressways.
    Improving construction activities. The construction division which has been underperforming over the past few quarters is expected to rebound in FY2007 on the back of an expanding order book from RM2.8bn a year earlier to RM4.1bn. Two big projects in Qatar (Dukhan Highway and Doha Airport works) are currently underway totaling RM1.8bn. In addition, it recently secured the RM640m Bahrain causeway works which should start by year end.
    The RM2.5bn Laos Hydropower project is not expected to be affected by the recent coup in Thailand and works should commence in the near term. The green light from EGAT of the Nam Theun 1 Hydroelectric power proposal paved the way for the finalization of the Power Purchase Agreement with EGAT and Concession Agreement with the Laos Government. However, we are wary of the execution risk of this project as evidenced by the troubled start after delays of more than a year.
    Flattish income from properties. Property contribution is not expected to rebound due to the limited growth prospects and with the near completion of Kota Kemuning. Its long term growth prospect will be from the commencement of its JV with UEM Land at Bandar Nusajaya at the end of this year should provide an upside potential in earnings for FY08 and onwards. The group also plans to develop a township near Kajang but it is still early to deduce anything from it.
    Growth driven by concessions. Going forward, growth would be driven by the concession division in view of the imminent toll rate hike in 2007 for Kesas Highway and LDP, and the launch of Gamuda’s Indian toll concession. We expect traffic to drop early on from the initial reaction post rate hike but should normalize in due time. In addition, the full commissioning of the SSP3 would provide further boost to its bottomline.
    9MP prospects. So far, there have been very limited announcements regarding the status of the 9MP projects. As for Gamuda, its prospects for the 9MP most would most likely stem from water projects, namely the Pahang-Selangor Interstate Water Transfer and flood mitigation projects. It still unclear on the potential award of this contract but judging from track record, we feel that Gamuda is in with a shout given its experience in the Selangor water project via Splash and the SMART tunnel flood mitigation project.
    Compelling valuation. At current juncture, the counter is trading a 17% dscount to its target price, which we derived from a RNAV calculation of RM4.70/share. Maintain our BUY call.

How?

Are you optimistic about the construction sector?

And oh about the M&A. LOL!! In my opinion, Citigroup is merely cooking up a storm... however, I am realistic enough to understand that anything can happen in the market. Deals can always be struck between anyone. For example the Business Times is also cooking up a storm in RoadBuilder too:

Read more...

Glomac

Thursday, September 28, 2006

Glomac reported its earnings yesterday.

Just came across this research report..

Here is the earning comparisons.


It wasn't pretty. On a q-q basis, net earnings dropped some 74.9%.


But despite earning just 4.2 million, this research report still insists that Glomac will earn some 49.7 million for its Fy 2007 or some 45.5 million for the remaining 3 quarters!

Isn't this being too optimistic?

So this research report admits that Glomac earnings is below their full year forecast by some 67.9% and they said it loud and clear that it was a weak quarter.

So they issue a Neutral call.

Down so much still Neutral?

And here comes this....


See their NEUTRAL call?

But do you see that their TARGET is at a whopping 1.51????

Isn't that irony?

Here's their reasoning:

By the way, don't you get confused by the misleading news articles which focus on irrelevant issues such as sale revenue of XBZ stock up by YYY%???

Here is the link to one such article: Glomac revenue up 13% to RM52.8m (Sounds good from the title, eh)


Read more...

Tanjong

Wednesday, September 27, 2006

Tanjong announced its earnings yesterday.

What about its German Resort thingy?

Well.. it's net losses increased! (why can't they acknowledge that this simply is a bad project?)

And here's some comments from RHB.

  • o RM17.7m operating loss from Tropical Island vs. RM11.4m loss in the 1QFY07 due to a 45% qoq drop in visitor arrivals although this was partly mitigated by a 13% increase in revenue per arrival to €26.
Operating loss increased. A 45% qoq drop in visitors arrivals is most disturbing, isn't it?

LOL!!! Anyway RHB Research is saying that do not be alarmed because all this bad news is already reflected in the share price? (doh!)

  • Although the 2Q results represent a "perfect storm" for Tanjong with disappointing earnings from almost all business units, we believe the 6% drop in the share price since June, and 14% for the year to date, has more than compensated for the poor 2Q performance. We expect good news ahead, including progress on the revamp for Tropical Island, as well as more stable power and gaming earnings.
And here's the flashback to what was blogged earlier:

====>>>

Saw this newsclip:

Tanjong's German resort gets another fund injection By Tamimi Omar, 12 Jul 2006 6:18 PMTanjong plc is taking steps to turn around its loss-making Tropical Islands resort in Germany with the injection of another 34 million euros (RM154 million) for its second phase of development over the next two years, bringing the total investment in the project to 110 million euros.
MORE>>

Incredible isn't it?

Let me repost an old posting on Tanjong's Tropical Island Resort Investment (best comment of course was “Compared with net asset or capitalisation, it's not significant at all,” he said.

=======>>>>>>

I was looking at Tanjong latest quarterly earnings when this statement in their earnings notes caught my attention.

  • The Leisure segment recorded a RM76 million increase in revenue following the
    commencement of Tropical Islands operations in December 2004. The segment registered an operating loss of RM69 million in the current year due to delays in the completion of certain facilities in Tropical Islands which resulted in lower than expected admissions and revenue.

Hmm... commenced in Decemeber 2004, and had operating loss of rm69 million. No wonder Tanjung earnings wasn't too happening this quarter.

Let's go back a year ago, March 2005 and look at how this
Tropical Island did. Now the notes in the earnings report was pretty sketchy, so I will use a snippet from RHB research notes back in March 2005.

  • Tropical Island Resorts (TIR) losses to continue in FY01/06 but should be immaterial by FY01/07 and turn around in FY01/08. To recap, TIR reported a higher-than-expected operating loss of RM51 versus earlier expectations of RM30m start-up losses. The higher losses of TIR were due to delay in installing a “translucent” roof. The cold weather condition slowed installing work and the doom’s height of 107m did not help. As a result, TIR’s main attraction (the Rainforest) did not have the intended tropical sunlight effects. The delay has resulted in negative publicity, which in turn affected tourist arrivals.

    In addition to the start-up losses, the resort has yet to reach its optimum number of visitors and yield. To date, one of the four translucent roofs has been installed. A check with TIR’s web-site shows the significant difference in having a ranslucent and non-translucent roof (refer to the above picture). Installation of the roof is scheduled for completion in 3QFY01/06. We believe pre-completion tourist arrivals are not likely to hit optimal level, especially when it would miss out on the peak holiday season (summer months) in Europe. Thus, we expect TIR to remain in the red in FY01/06. However, we estimate that the operating losses would be trimmed from RM51m in FY01/05 to about RM33m in FY01/06.

    We were given to understand that with costs under control, TIR is expected to turn around and commence positive contribution in FY01/07. After the completion of the translucent roof, the company would adopt more focus and aggressive marketing efforts to attract visitors and hope to benefit from the spillover effect of the 2006 World Cup in Berlin. However, we have adopted more conservative assumptions on tourist arrivals and costs. We expect an immaterial operating loss of RM0.2m. For FY01/08, we are forecasting RM11.6m operating profit on account of higher visitors.

So what is this TIR? Well, TIR stands for Tropical Island Resort. A project started by Tanjung back in 2003. And this Tropical Island Resort was built in Brand, 60 kilometer south of Berlin.

Yes, a tropical island resort in Germany. LOL!

  • Tanjong and Mr Colin Au propose to enter into a joint venture agreement to develop the land into a "Tropical Island" holiday destination that provides an all year-round indoor tropical environment. The "Tropical Island" holiday destination will house a variety of tropical settings such as rainforest, sea, lagoon, beaches, water parks, exhibition centres, tropical flower world, resort hotels and spas to cater for all age group visitors.

Yup, this is probably what an investor do not want to see. Companies straying way off course in their own business objective. Totally bad.

Even the idea is lousy, isn't it? Say, you are a German and you want to go for a tropical holiday. Wouldn't you want to just fly away to a real tropical island than end up in Brand, Berlin? It wound really sound a drag of a holiday. Those Germans that I know, they really like to travel.

And needless to say, the stock was hammered when Tanjong made the announcement back in June 2003. Here is a short snippet then.

  • Business Times - 24 Jun 2003
    KUALA LUMPUR
    Tanjong shares plunge on German theme park move

    Stock falls 6% as investors deem it a poor investment

    MALAYSIAN lottery and power firm Tanjong plc's surprise plan to build a mock tropical retreat in Germany knocked 6 per cent off its shares yesterday as investors guessed it may have made a wrong bet.

    Tanjong said on Friday it had bid an undisclosed amount for the land and assets of Germany's Cargolifter AG in a joint offer with Colin Au, the ex-chief executive of cruise operator Star Cruises Ltd.

    'Trying to have a theme park in Europe is not a good idea. Just look at Euro Disney,' said Nik Azhar Abdullah of Commerce Asset Fund Managers..... 'I'm a bit surprised with the type of investment. The European economy is not exactly booming right now,' said JP Morgan's Melvyn Boey.

And of course, the company was forced to defend itself...

  • Friday, June 27, 2003
    Tanjong: German park not a significant investment

    TANJONG Plc said a bid for 500ha in Germany to build a holiday park will not require a “significant'' investment, addressing concerns its finances will be strained.

    “The project is not significant in the context of Tanjong,'' chairman Datuk Khoo Eng Choo told reporters after a shareholders' meeting in Kuala Lumpur.

    “Compared with net asset or capitalisation, it's not significant at all,” he said.

How would you feel, as an investor, when you hear the chairman declaring that such an investment to be not significant?

So how much was the total investment? It wasn't until July 7th 2003, that folks like me could read it in the papers.

  • Tanjong, Au to spend RM304.6m on German tropical resort project
    GAMING and power company Tanjong plc is teaming up with Colin Au to develop a tropical resort in Germany at a total cost of RM304.5 million.

    The company said the total cost includes the RM76.1 million or 17.5 million euros cash it is paying for the assets of CargoLifter AG Group.

    The assets include a 500ha piece of land situated 60km south of Berlin, Germany. The land currently houses a free-standing hangar measuring 360 metres long, 210 metres wide and 107 metres high.

    Tanjong said that two German companies, Tropical Island Management GmbH and Tropical Island Asset Management GmbH will develop and operate an entertainment and leisure based tourist holiday destination with tropical island setting within the hangar. Both companies are 50 per cent owned by Tanjong Entertainment Sdn Bhd, a wholly owned subsidiary of Tanjong.

    “The project cost will be funded through a combination of equity funds, shareholder’s advances and bank borrowings to be secured by two German companies,” Tanjong said.

    It added that the project is only expected to be completed in the fourth quarter of 2004. “As such, it will not have any material effect on the group’s earnings for the current financial year ending January 31 2004,” it said.

    “This project is very much an extension of Tanjong’s existing involvement in the leisure and entertainment business. Over the years, we have been continuously identifying opportunities for the expansion of our business in this sector,” says Tanjong’s chairman Datuk Khoo Eng Choo in a statement to the Kuala Lumpur Stock Exchange.

    Au said: “We are confident that this project, when completed, will draw in repeat visitors, especially from Germany and its neighbouring European countries.”

    He said the tropical resort is also expected to feature monthly exhibits of a tropical country or region.

    “As a start, we hope to work with the Malaysian Tourist Promotion Board to feature Malaysia with its rich heritage of culture, arts, food, architecture, islands, resorts and its rainforest. Also, Malaysia’s cultural groups, musicians and dancers will have the opportunity to perform at the Tropical Island,” he added.

    Tanjong also agreed to set up a joint venture company with Au Leisure Investments Pte Ltd to identify, develop and operate entertainment and leisure based holiday destinations with tropical island setting.

    The joint venture company, Central Pacific Assets Ltd will have an initial share capital of 5 million euros (1 euro = RM4.35) and an eventual enlarged paid-up share capital of up to 30 million euros. Central will be owned equally by Au Leisure and Tanjong Entertainment.

    Tanjong said Au, who has 30 years of experience and expertise in international leisure and tourism industries shall be appointed as chief executive officer of Central. “The position of chairman and chief financial officer of Central shall be nominated by Tanjong Entertainment,” it added.

According to the closed Surf 88 back in 2003...

  • The investment cost… With the details now unveiled, the expected investment in the venture is not as massive as earlier feared by investors. The jv will initially be capitalized at Euro 5M (RM21.8M) and eventually up to Euro 30M (RM130.5M). Tanjong’s 50% share hence works out to RM65.3M at the final stage (16.9 sen per Tanjong share or 1.6% of current share price). This is considered a relatively small investment for Tanjong, where funding is not a problem given more than RM300M free cash flow annually (cash flow from operations after dividend and capital expenditure).

So how?

Well, it looks like this 'not significant' investment for Tanjong cost some rm65.3 million.

And the end results?

This fiscal year 2006 earnings for Tanjong showed that the Tropical Island's reported opertaing losses of rm69 million!!

Ahh... when company embarks on a funky corporate exercise, like investing in a tropical island resort, most of the time, the company would end up producing some real funky results too for its investors.

Yeah dude... just play that funky music man!

---

edit 12.09 pm 29th March

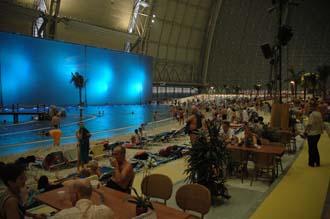
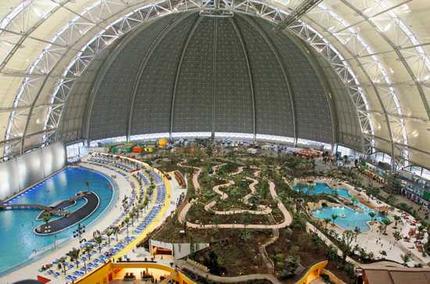
found some pictures... via a google search on the phrase 'tropical island resort; brand; germany'..

err... how? look fun ar?

and here is a newsclip on it... Gone troppo in Germany

Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP