Powered by Blogger.

Home

Showing posts with label Dilution Of Earnings. Show all posts

Flashback: Integrax: My Earnings Has Shrunk!

Monday, July 28, 2008

The following posting was initially posted way back on May 2006. I am reproducing it here again.

I was told that this stock was recommended by a fund when it was trading around 1.38 back in Aug 2003.

Did they NOT know about the MASSIVE dilution impact from the conversion of the ICPs? They should have known, yes?

As of today, this stock still carries a HOLD recommendation.

It's now July 2008.

Stock trades at around 0.79.

Buy and Hold Forever?

Well? You tell me.

--------------------------


The following post is dedicated to Anon who asked about the dilutions effects caused by placement shares, esos etc.


One of the best example I could really think of is a past discussion I had on this one stock called Integrax.

On 28th feb 2003, Integrax announced its fy2002 Q4
quarterly earnings.

It made a total net earnings of 16.159 million from a sales revenue of 25.244 million for its fiscal year.

I got a message in July 2003 asking about this stock:

==>

I have made some studies on this counter and noted some good points:

  1. stable assure income from TNB power plant (future earning will double)
  2. closely link to state goverment
  3. potential aluminiam plant project (will add on the coal transportbusiness)
  4. low PE (really fantastically low)
  5. proposed to transfer to main board.
here was my reply then.

<<==>>

my comment on integrax ...

1. those listed port stocks, their fundamentals are ok, meaning they are companies that operates on a very high profit margins. in which you have also choices like Bintulu Port. So far, from its only earnings (Integrax was a newly listed stock, which was listed via a reverse takeover of a stock called Ganz) , in its
02 Q4 earnings report, Integrax had figures like this...


2. now as you would see the numbers were fantastic. (the eps is based upon 115.656 million shares, which was stated in that quarterly earnings report). And if you annualised such performance for fy 2003, then the potential is there.. cos one is looking at a potential eps of 38-40 sen for fy 2003. And yes, I did note that folks like Ah Goh (GK Goh) was projecting 03 earnings to be lower, at around 30 million, or an eps of 26 sen based on 115.656 million shares.

( Back then Integrax trading around 1.15-1.30 and based on the projected 03 earnings, Integrax at 1.15 was trading at a super duper low PE of 4.4x based on Ah Goh's estimates.. and at such a low PE multiple, surely this would have been an ideal hidden gem right? In fact, Surf 88 back then, had a super positive research calling it a Lumut Gem!)

3. But after researching more, i found out that there were lots of ICP shares being converted into ordinary shares. This was part of the agreement under Integrax's takeover of Ganz. Now I do NOT know know the exact restriction (if any) on how these ICPs were converted but judging from KLSE announcements, they were converted on quite a regular basis. So what's important is, if you wanna invest in this stock, you need to figure out how many total ICP's were issued.
(here is where the DILUTION of shares has such an impact on the share price.)

Now these ICPs, they have this dilution effect. As I had checked out the other day (back in July 2003), the number of shares in Integrax stands at 196,762 million shares!!

Now based on the projected earnings of 30 million, Integrax projected DILUTED eps is now 15 sen. Which now means, at 1.15 Integrax is trading at a forward PE of 7.6! (compared to a pe between 4.4).

See how greatly the eps has been diluted by these ICP's?

So... if you are not carefull.... you might have actually invested in Integrax had a much higher PE multiple than you have imagined...


4. Is Integrax an average company or an excellent company? I dunno.

Too early for me to determine, plus there is really too limited info i can dig up on Integrax itself.... so i cannot comment on it.

<<==>>

That was in July 2003. Now Integrax was in a nice rally mood.

And soon in Oct 2003, it was trading around 1.90++ (which turned out to be its peak today)


And here is another extremely interesting point.

Integrax Loan Stocks and its Irredeemable Convertible Preference (ICP) shares were still constantly being converted into ordinary shares. (here is one announcement indicating
the conversion of ICP shares )

Which meant that the earnings per share were constantly being diluted at a very rapid pace.

But the share price was rocketing.

How?

Would an investor cash out back in Oct 2003? (remember, they had an opportunity to buy just in July 2003 at around 1.15)

A year later, on 27th Feb 2004, Integrax announced its fy 2003 quarterly earnings.

It made a total net earnings of 28.819 million from a sales revenue of 93.434 million for its fiscal year.

Integrax's results is pretty impressive really. And in fact it does look like a decent and very profitable company... but i guess the main question is why the share price is performing so poorly was explained clearly by the company.

  • PATMI changes are reflective of the above while EPS changes reflect the impact of a larger share capital base this quarter.

Ahh... the EPS shrunk!!

Diluted!

The dilution effects from the conversion of Integrax's ICP shares and loan stocks. And the more conversion are made, the large the share base becomes, hence Integrax share base is growing each quarter, which meant that unless Integrax earnings grow at a much faster than how its share base expands, the eps would become smaller each quarter and when the E in PE becomes smaller, the price 'usually' goes down to reflect the lower E.

To fully illustrate how diluted the earnings become:

Integrax number of shares now is 263.882 million shares!! (back in Feb 2004)

Which meant Integrax eps is only 10.9 sen for its fy 2003! (a huge cry from Ah Goh's estimate of 26 sen eps!.. and most important see how the net profit increased a lot BUT yet the EPS 'dropped drastically?)

Which meant that the traded shares of Integrax is now much more expensive despite a pretty impressive fiscal year earnings? (In Feb 2004, at 1.50, Integrax was trading at a PE of 13.7x!!)

Perhaps it is better to take note of all those ICP shares, right?

Example
(done on 28th Feb 2004)

Integra has 263.882 million shares
Integra LA has 31.890 million shares
Integra PA has 10.570 million shares.
Full dilution = 263.882 + 31.890 + 10.570 = 306.342 million shares.
Fully diluted eps = 28.819 / 306.342 =
9.4 sen.

So do remember.. this bugger just got soooooo many shares out there.... that you dun really know what is going.... plus since this is a RTO listed company.... so you never know the true cost of those ICP shares, etc, etc..... and do take one step back ... dig deeper back into history.... look at Ganz last reported earnings report. Ganz had only got 19.8 million shares. Compare it to now. 263.882 million shares. A lot of new shares has been issued.

<<==>>

So in July 2003.. Integrax was trading around 1.15-1.30.

It peaked in Oct 2003 around 1.90++

On Feb 2004 it traded in the 1.50 region.

now on May 2006? Less than 0.70!

The below pix says it all...
(long term buy and hold? if your initial reasoning is wrong.. holding it longer is holding in hope!)


So if one purchases a share in a company and discounts the effect of the dilution of earnings, see the drastic end result?

Of course not all companies are like that. And as mentioned in the case of IOI, the conversion of warrants did not have a negative impact on the share price. Why? IOI Corps earnings grew at a much faster pace.

It's pretty simple actually.. take the blog posting
ROI on Uchi: Part III - the ESOS issue

<<==>>

Now if you add both figures up, you will get 82,820,992 new shares, assuming full exercise of ESOS.

Currently Uchi has 372,392,800 shares. Which means there is a possible dilution in earnings per share of 22% assuming full exercise of all these ESOS.

Now let's be realistic and ask ourselves this... is 22% dilution in earnings per share a lot or not?

Simple way to look at this dilution.

Say U** has a current eps of 100 sen.
Say U** has a possibility to trade at a price earnings multiple of 18x.

Which means U** could be worth some 18.00 in market price.

Now a 22% dilution means... the eps would be 78 sen.
And using the same pe multiple assumption of 18x, U** should be trading at a market price of 14.00.

See how disadvantage it is to the minority shareholder?

<<==>>


Read more...

Notion Special Issues of Shares

Sunday, August 5, 2007

My Dearest Alvan,

  • Recently, if you read the announcement properly, Notion's major shareholders sold off portion of their shares to comply with with NEP requirement (i.e. 30% bumiputra spread). So, they are not diposing it because of the change in prospect or fundamental. Furthermore, there is no new share issued, so there is no dilution of share value. Correct me if I am wrong.
Subject: NOTION VTEC BERHAD ("NOTION" or "Company") I. PROPOSED BONUS ISSUE II. PROPOSED SPECIAL ISSUE III. PROPOSED INCREASE IN AUTHORISED SHARE CAPITAL IV. PROPOSED AMENDMENTS TO THE COMPANY'S MEMORANDUM OF ASSOCIATION (COLLECTIVELY REFERRED TO AS THE "PROPOSALS")

If you read that announcement,


  • 1. (b) special issue of 103,500,000 new NOTION Shares ("Special Issue Shares"), representing 17.65% of the enlarged issued and paid-up share capital of NOTION (after the Proposed Bonus Issue), to Bumiputera investors to be approved by the Ministry of International Trade and Industry ("MITI") at an issue price to be determined later ("Proposed Special Issue");
If you open up that Wordfile attached, you will see a table which clearly states what is happening.

Or you can see the screenshot below.


At the end, AFTER the proposed special issue, Notion was supposed to have an enlarged share capital of 689.819 million shares.

So correct me if I am wrong, after the special issue, the share based is enlarged. Is this not a dilution of earnings?

Some interesting links which shows the extension of time and the revisions made on this special issue of shares.

30th Nov 2006, Notion made a revision to this special issue:
NOTION VTEC BERHAD ("NOTION" or "Company") Revisions to the Special Issue

22nd Jan 2007. Notion made an extension.
NOTION VTEC BERHAD ("NOTION" or "Company") Extension of time to comply with the 30% Bumiputera Equity Condition

27th March 2007. Another extension.
NOTION VTEC BERHAD ("NOTION" or "Company") Extension of time to comply with the 30% Bumiputera Equity Condition

17th May 2007. Another extension.
NOTION VTEC BERHAD ("NOTION" or "Company") - Revision to the Promoters' Placement; and - Extension of time to comply with the 30% Bumiputera Equity Condition

  • On behalf of the Board of Directors of NOTION, HWANGDBS Investment Bank Berhad (formerly known as Hwang-DBS Investment Bank Berhad) (formerly known as Hwang-DBS Securities Berhad), is pleased to announce that the Ministry of International Trade and Industry ("MITI") has, vide its letter dated 15 May 2007 (which was received on 16 May 2007) taken note and has no objections to the following:

    (i) Revision to the collective placement of existing ordinary shares of RM0.10 each in NOTION ("Notion Shares") by the promoters of NOTION, from 125,895,000 to 147,500,000 NOTION Shares to Bumiputera investors to be approved by the MITI ("Promoters' Placement"); and

    (ii)
    Out of the 147,500,000 NOTION Shares, the remaining balance of 51,000,000 NOTION Shares will be allocated by the MITI to Bumiputera investors to be identified later.

    MITI is agreeable to the above, provided that the Company obtains the approval of the Securities Commission ("SC") for the Promoters' Placement, and complies with the Guidelines on the Acquisition of Interests, Take-Overs and Mergers by Local and Foreign Interests.

    In this regard, the SC's approval was obtained on 4 April 2007.

    This announcement is dated 17 May 2007.

Quote: Out of the 147,500,000 NOTION Shares, the remaining balance of 51,000,000 NOTION Shares will be allocated by the MITI to Bumiputera investors to be identified later.

How?

Read more...

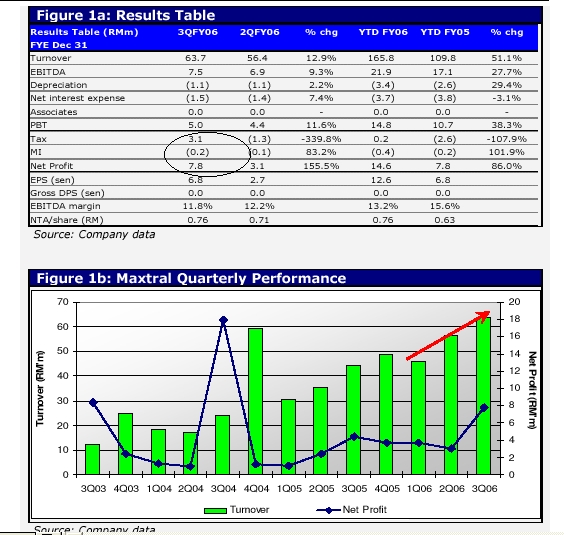
Maxtral's Earnings and its possible ICP dilution effect

Wednesday, November 29, 2006

Unker Anon,

Sorry was in a rush this morning. :D

Firstly, its earnings.

I'm kinda confused cos i had a glance at OSK write-up.

So I decided to look back at Bursa website.

This is Maxtral's Q1 earnings.

Quarterly rpt on consolidated results for the financial period ended 31/3/2006

net profit reported: 3.707 million

This is Maxtral's Q2 earnings.

Quarterly rpt on consolidated results for the financial period ended 30/6/2006

net profit reported: 3.053 million.

This is Maxtral's Q3 earnings.

Quarterly rpt on consolidated results for the financial period ended 30/9/2006

net profit reported: 3.470.

If you add up the numbers, its net profits shows 10.230 million only. But if you look at what Maxtral is saying, its ytd 3 quarter net profit is at 14.559 million.

How?

I think the later is correct because the cash flow is much, much stronger than Maxtral's earnings of 10.230 million. So what i am saying is i believe Maxtral's Q3 net earnings is much more than stated. I believe it's a typo, perhaps.

I took a screen-shot of Maxtral's earnings (look at the circle). OSK is saying that according to Maxtral data, its Q3 net earings is 7.8 million. (which kinda tally with Maxtral's cash flow, cos this quarter, Maxtral's cash flow increased by some 14+ million!)


Now regarding them dilution effects again.

Remember i wrote the following....

>>>>

1. Them preference shares issue. See Maxtral posting.

  • At the moment of writing, Maxtral has some 210.099 million shares and it has some 84.415 million shares of ICUL outstanding. (ICP can converted on 1-1 basis)

Which means that if one ass-u-me full conversion of these ICP shares, then Maxtral should have 294.514 million shares. That should the share base you probably should work upon to avoid any shocks from discovering that your earnings per share has been diluted by these ICP shares. Ass-u-me the worse case scenerio. That's what I would have done. Remember this is just a mere second opinion. Some would probably have a different approach depending on one's investing style. For example, some would dare just the current share base (210.099 mil shares) cos they do not reckon that they would be such a long term investor. Which is right or wrong, it depends on your own interpretation.

>>>

So if you have a look at Max's earnings, its Q3 earnings states that its net earnings came in at 14.979 million.

Now assuming this figure is correct.. then this company is churning out some 4.993 million per quarter or as they say, if u annualise on a yearly basis, that's close to 20 million in earnings.

Using the fully-diluted number of shares - ie assuming full conversion of ICP, then the earnings per share is 20 million divided by 294 which gives you roughly an earnings per share of 6.8 sen.

So if you use this diluted earnings per share number, i think you should be ok lah.

PS..

regarding the mp player. BUY the IPOD nano unker. Your kids been good and they deserve a grand christmas present!

:D


Read more...

My Earnings has been Shrunk!

Wednesday, May 3, 2006

The following post is dedicated to Anon who asked about the dilutions effects caused by placement shares, esos etc.

One of the best example I could really think of is a past discussion I had on this one stock called Integrax.

On 28th feb 2003, Integrax announced its fy2002 Q4
quarterly earnings.

It made a total net earnings of 16.159 million from a sales revenue of 25.244 million for its fiscal year.

I got a message in July 2003 asking about this stock:

==>

I have made some studies on this counter and noted some good points:

  1. stable assure income from TNB power plant (future earning will double)
  2. closely link to state goverment
  3. potential aluminiam plant project (will add on the coal transportbusiness)
  4. low PE (really fantastically low)
  5. proposed to transfer to main board.
here was my reply then.

<<==>>

my comment on integrax ...

1. those listed port stocks, their fundamentals are ok, meaning they are companies that operates on a very high profit margins. in which you have also choices like Bintulu Port. So far, from its only earnings (Integrax was a newly listed stock, which was listed via a reverse takeover of a stock called Ganz) , in its
02 Q4 earnings report, Integrax had figures like this...


2. now as you would see the numbers were fantastic. (the eps is based upon 115.656 million shares, which was stated in that quarterly earnings report). And if you annualise such performance for fy 2003, then the potential is there.. cos one is looking at a potential eps of 38-40 sen for fy 2003. And yes, I did note that folks like Ah Goh (GK Goh) was projecting 03 earnings to be lower, at around 30 million, or an eps of 26 sen based on 115.656 million shares.

( Back then Integrax trading around 1.15-1.30 and based on the projected 03 earnings, Integrax at 1.15 was trading at a super duper low PE of 4.4x based on Ah Goh's estimates.. and at such a low PE multiple, surely this would have been an ideal hidden gem right? In fact, Surf 88 back then, had a super positive research calling it a Lumut Gem!)

3. But after researching more, i found out that there were lots of ICP shares being converted into ordinary shares. This was part of the agreement under Integrax's takeover of Ganz. Now I do NOT know know the exact restriction (if any) on how these ICPs were converted but judging from KLSE announcements, they were converted on quite a regular basis. So what's important is, if you wanna invest in this stock, you need to figure out how many total ICP's were issued.
(here is where the DILUTION of shares has such an impact on the share price.)

Now these ICPs, they have this dilution effect. As I had checked out the other day (back in July 2003), the number of shares in Integrax stands at 196,762 million shares!!

Now based on the projected earnings of 30 million, Integrax projected DILUTED eps is now 15 sen. Which now means, at 1.15 Integrax is trading at a forward PE of 7.6! (compared to a pe between 4.4).

See how greatly the eps has been diluted by these ICP's?

So... if you are not carefull.... you might have actually invested in Integrax had a much higher PE multiple than you have immagined...


4. Is Integrax an average company or an excellent company? I dunno.

Too early for me to determine, plus there is really too limited info i can dig up on Integrax itself.... so i cannot comment on it.

<<==>>

That was in July 2003. Now Integrax was in a nice rally mood.

And soon in Oct 2003, it was trading around 1.90++ (which turned out to be its peak today)


And here is another extremely interesting point.

Integrax Loan Stocks and its Irredeemable Convertible Preference (ICP) shares were still constantly being converted into ordinary shares. (here is one announcement indicating
the conversion of ICP shares )

Which meant that the earnings per share were constanly being diluted at a very rapid pace.


But the share price was rocketing.

How?

Would an investor cash out back in Oct 2003? (remember, they had an opportunity to buy just in July 2003 at around 1.15)

A year later, on 27th Feb 2004, Integrax announced its fy 2003 quarterly earnings.

It made a total net earnings of 28.819 million from a sales revenue of 93.434 million for its fiscal year.

Integrax's results is pretty impressive really. And in fact it does look like a decent and very profitable company... but i guess the main question is why the share price is performing so poorly was explained clearly by the company.

  • PATMI changes are reflective of the above while EPS changes reflect the impact of a larger share capital base this quarter.

Ahh... the EPS shranked.

Diluted!

The dilution effects from the conversion of Integrax's ICP shares and loan stocks. And the more conversion are made, the large the share base becomes, hence Integrax share base is growing each quarter, which meant that unless Integrax earnings grow at a much faster than how its share base expands, the eps would become smaller each quarter and when the E in PE becomes smaller, the price 'usually' goes down to reflect the lower E.

To fully illustrate how diluted the earnings become:

Integrax number of shares now is 263.882 million shares!! (back in Feb 2004)

Which meant Integrax eps is only 10.9 sen for its fy 2003! (a huge cry from Ah Goh's estimate of 26 sen eps!.. and most important see how the net profit increased a lot BUT yet the EPS 'dropped drastically?)

Which meant that the traded shares of Integrax is now much more expensive despite a pretty impressive fiscal year earnings? (In Feb 2004, at 1.50, Integrax was trading at a PE of 13.7x!!)

Perhaps it is better to take note of all those ICP shares, right?

Example
(done on 28th Feb 2004)

Integra has 263.882 million shares
Integra LA has 31.890 million shares
Integra PA has 10.570 million shares.
Full dilution = 263.882 + 31.890 + 10.570 = 306.342 million shares.
Fully diluted eps = 28.819 / 306.342 =
9.4 sen.

So do remember.. this bugger just got soooooo many shares out there.... that you dun really know what is going.... plus since this is a RTO listed company.... so you never know the true cost of those ICP shares, etc, etc..... and do take one step back ... dig deeper back into history.... look at Ganz last reported earnings report. Ganz had only got 19.8 million shares. Compare it to now. 263.882 million shares. A lot of new shares has been issued.

<<==>>

So in July 2003.. Integrax was trading around 1.15-1.30.

It peaked in Oct 2003 around 1.90++

On Feb 2004 it traded in the 1.50 region.

now on May 2006? Less than 0.70!

The below pix says it all...
(long term buy and hold? if your initial reasoning is wrong.. holding it longer is holding in hope!)


So if one purchases a share in a company and discounts the effect of the dilution of earnings, see the drastic end result?

Of course not all companies are like that. And as mentioned in the case of IOI, the conversion of warrants did not have a negative impact on the share price. Why? IOI Corps earnings grew at a much faster pace.

It's pretty simple actually.. take the blog posting
ROI on Uchi: Part III - the ESOS issue

<<==>>

Now if you add both figures up, you will get 82,820,992 new shares, assuming full exercise of ESOS.

Currently Uchi has 372,392,800 shares. Which means there is a possible dilution in earnings per share of 22% assuming full exercise of all these ESOS.

Now let's be realistic and ask ourselves this... is 22% dilution in earnings per share a lot or not?

Simple way to look at this dilution.

Say U** has a current eps of 100 sen.
Say U** has a possibility to trade at a price earnings multiple of 18x.

Which means U** could be worth some 18.00 in market price.

Now a 22% dilution means... the eps would be 78 sen.
And using the same pe multiple assumption of 18x, U** should be trading at a market price of 14.00.

See how disadvantage it is to the minority shareholder?

<<==>>


Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP