Powered by Blogger.

Home

Showing posts with label Titan Chemcials. Show all posts

News On Titan Chemicals Earnings Performance

Tuesday, November 4, 2008

What good is sales without profit?

What good is talking about sales revenue growth when your profits are declining?
These are rather elementary issues, yes?

It was a shocker to read the following article:
Titan 9-month revenue up 32pc

Yes, boldly highlighted was Titan 9-month revenue up 32pc and that what was even more amazing that they even have a huge colored chart of Titan Chemical's sales revenue performance!


And how did Titan actually performed? Rather shockingly poor! It's a stinker!

A net profit of only 9.671 million!!!!!!!!!!! Last year same period, it made 74.710 million.

And the previous quarter, Titan made over 116 million!!!!!!! ( See Quarterly rpt on consolidated results for the financial period ended 30/6/2008 )

Hence Titan's earnings last night was TERRIBLY POOR!

On Star Biz, Titan third quarter net profit drops on inventory write-down

  • Titan third quarter net profit drops on inventory write-down

    PETALING JAYA:
    Titan Chemicals Corp Bhd’s net profit shrunk to RM9.67mil for the third quarter ended Sept 30 against RM74.7mil in the previous corresponding period.

    The drop was attributed to inventory write-down of RM124.7mil by the company on falling feedstock and end-product prices during the quarter under review.

    “With limited visibility on global economic growth and wavering levels of business confidence, industry producers and downstream manufacturers were understandably more cautious and conservative.

    “Hence demand weakened and prices fell between July and September,’’ managing director Warren Wilder said in a statement yesterday. Turnover for Q3 increased to RM2.05bil from RM1.56bil, as higher sales prices offset lower sales volume.

Which is why I cannot comprehend what Business Times is writing here: Titan 9-month revenue up 32pc. Here is the article in full.

  • Titan 9-month revenue up 32pc

    By Sharen KaurPublished: 2008/11/05

    Titan Chemicals Corp Bhd (5103) reported a 32 per cent surge in revenue to RM5.8 billion for the nine months to September 30 2008 on higher average selling prices.

    The net profit of Malaysia's biggest petrochemical firm, however, slid 26 per cent to RM216.5 million, largely because of lower earnings in the third quarter.

    Third quarter net profit fell 92 per cent to RM9.9 million from RM119.2 million in the same period last year.


    This was attributed to margin squeeze and writedown of inventories to net realisable value amounting to RM124.7 million in the third quarter, caused by plunging prices of oil and its derivatives, including feedstock and end-products.

    Titan, which makes olefins and polyolefins for the plastics industry and uses naphtha - a petroleum by-product - as raw material, said the average industry weekly prices for naphtha and polymers had moved downwards as global economic uncertainties seeped in.
    In a statement yesterday, the main board-listed firm said that group sales in the third quarter declined two per cent to RM2 billion from RM2.1 billion in the preceding quarter.

    "The global business environment has turned very challenging. With limited visibility on global economic growth and wavering levels of business confidence, industry products and downstream manufacturers were understandably more cautious and conservative. Hence, demand weakened and prices fell between July and September," Titan managing director Warren Wilder said.

    Titan said that demand for polymer products in the last quarter of 2008 was expected to be affected by the possible global recession, but believed the impact would be partially mitigated by the seasonal demand towards the end of the year.

    "Our diversification into higher manufacturing capacity for polypropylene production is part of our long-term strategy in product positioning," Wilder said.

    Titan has completed a plan to solve the bottleneck at its polypropylene plant, enabling it to increase production significantly.

Don't you think the article head line of Titan's revenue being up 32% is rather so misleading?

And do have a look at this past blog posting: Titan VIII


Read more...

Titan's Dividend.

Monday, February 26, 2007

Just saw this news clip posted on Business Times:

  • Payout cheer for Titan investors
    Pending shareholders approval in May, Titan Chemicals is proposing a full-year dividend payout ratio of 7.5 sen per share

  • Payout cheer for Titan investors
    By Ooi Tee Ching
    bt@nstp.com.my

    February 27 2007

    TITAN Chemicals Corp Bhd, South-East Asia's largest polyolefins producer, expects to give higher dividends to shareholders this year, its chief said.

    The company, whose products are used to make plastic products, wants to increase its payout to shareholders on higher profits.

    In 2006, Titan's net profit more than doubled to RM773.2 million, thanks to contribution from Chemical Brothers Ltd, a newly acquired unit. Revenue went up by 21 per cent to RM5.45 billion from RM4.50 billion.

    Managing director Thomas Patrick Grehl said, pending shareholders approval in May, Titan is proposing a full-year dividend payout ratio of 7.5 sen per share.

    In 2005, Titan paid out 20 per cent of its net profits as dividends and that worked out to be 6 sen per share.

    "We had a good year in 2006. We plan to give back 30 per cent of net profit, or 7.5 sen per share, to investors," he told a media briefing held in Kuala Lumpur yesterday.

    Titan plans to de-bottleneck its crackers to produce more olefins.

    "We are goint to de-bottleneck the polypropolene plant so that it can churn out to 480,000 tonnes per year from the current capacity of 380,000 tonnes," Grehl said.

    In the last six months, the trading gap between the price of raw material naphtha and end-product polyolefins had resulted in healthy profit margins for Titan.

    Grehl is optimistic of Titan's outlook as forward orders of polyolefins are exceeding regional supply.

    "The stable regional outlook for polyolefins, amid a slower supply growth and steady demand, will continue to boost Titan's revenue growth," he added.

    In meeting robust polyethlene demand in Indonesia, PT Titan, formerly known as PT Petrokimia Nusantara Interindo (PT PENI), is increasing output.

    Last year, Titan's Indonesia operation churned out 100,000 tonnes of polyethlene and sold them at between US$1,300 (RM4,550) and US$1,400 (RM4,900) per tonne.

    Despite such high prices, it captured 22 per cent of the Indonesian polyethlene market.

    "Basically, whatever we produce in Indonesia, we can sell. To meet growing demand, we're ramping up production to 300,000 tonnes," Grehl said.
I find it great to read such stuff where the listed companies reward their shareholders.

However, in Titan case, I am left wondering because as it is, the cash balance sheet is not looking that great to support the size of a 7.5 sen cash dividend.

Have a look at the pdf file link attached in Titan's earnings.

http://announcements.bursamalaysia.com/EDMS/edmsweb.nsf/ba387758ae37412b482568a300466fb6/48256e5d00102df3482572810031f62d/$FILE/Qtr%204Announcement1206.pdf

The following is the snapshot of their cash balance sheet.


Cash balances of some 25.748 million.

Consider this... Titan has some 1,752,700,000 shares. A dividend of 7.5 sen will work to..... ?

Read more...

Chat on Titan

Sunday, February 25, 2007

  • ywt06 said...
    hi,it's me again.i didn't blame for the shortfall of actual net profit vs forecast in IPO.who would know the sudden increase of oil price in second half of 2005?the ability of the management team is impressive under new MD.the stock is getting better and better ....


Hi ywt06,

I fully agree with you very much about the extremely diffiuclty in forecasting profits in an IPO.

I really do.

However, there are instances where companies take advantage of this situation and project an earnings number which are totally overly optimistic.

Take a look again at the following points mentioned. Please do note, I am merely sharing my opinions and this is not an issue of right and wrong. Ok?

Anyway, in my first Titan posting:
Titan

If you look at the attached snapshot of Titan earnings posted on OSK report, you would note that the company boldy projected a net earnings of 604 million for fy 2005.

Now, what's so wrong with that earnings projection?

Simple. Titan only earned some 262 million for their last reported earnings. And to project and then SELL their IPO to the investing public based on this earnings of 604 million or a growth of 130% was totally incredible and way overly optimistic in my opinion.

By the way, if you look at the blog posting, observe the dates and see how the company management continued to maintain their optimistic views on their earnings in May and Aug. Let me repaste here again:

  • Friday August 26, 12:38 PM
    Malaysia Titan sees strong profit margin until 2009

    KUALA LUMPUR, Aug 26 (Reuters) - Malaysia's Titan Chemicals Corp said on Friday it expects its strong profit margin to continue until 2009.Managing director Donald M. Condon Jr says Titan Chemicals has been largely unaffected by the surge in oil prices because it is able to pass growing costs to customers

How?

Crude oil was supposed to be a non-factor! (Another incredible statement in my opinion.)

Anyway, just sharing my views.

rgds


Read more...

Regarding Titan

Monday, February 19, 2007

  • ywt06 said...
    I have no idea why you dislike Titan. Lower cash flow is mainly due to the purchase of PPE for their new plant. In mid ot long term, you will know how great is this stock ...

Yes, you are absoultely correct on why the cash flow decreased.

Here is my archives of postings made on Titan. Perhaps you could understand why I am not impressed at all with Titan. (ps. this is just my personal opinion on Titan. And this is not an attempt to persuade others to follow my reasonings/opinions)

  1. Titan
  2. Titan: Part II
  3. Titan: Part III
  4. Titan: Part IV
  5. Titan: Part V
  6. Titan: Part VI
  7. Titan: Part VII
  8. Titan VIII
Just prior to their listing, during their ipo period, these companies would promise their prospective investors heaven and earth. Bright future prospects with optimistic earnings growth.

In
Titan: Part III

Record earnings? Excuse me, Titan was SOLD to the investing public in a titanic IPO worth some rm950 million. And the whole valuation was based on the fact that Titan itself gave a promise that it would deliver some rm604 million in net earnings. And how much did Titan deliver? rm361 million!

Here is some titanic stuff from that article..

  • Speaking at a media briefing in Kuala Lumpur on Feb 22, Titan managing director Donald M. Condon Jr attributed the impressive results to the strong first-half performance.

Well I am impressed, aren't you?

  • On the performance of Titan’s share price: “We do think our share is undervalued. That’s why we’ve put together a share buyback plan. The plan will be put in place depending upon how the share continues to do in the market.”

Undervalue? Did he say undervalue?
Titan clsoed the day trading at rm1.35.
What was Titan IPO price? rm2.17!

That was one of my main issues against Titan.

Anyway, as it is, total loans is at 1,544,626. Cash balances is only 25.748 million. From an investing point of view, this company is really overly geared isn't it?

ps. the market is kinda optmistic right now. As it is, all stocks stands a chance to be great, no?

Anyway, just a mere second opinion as usual.

Cheers

Read more...

Titan VIII

Tuesday, February 13, 2007

Saw this article posted on Business Times:

  • Titan Q4 net profit surges 20-fold

    February 14 2007

    TITAN Chemicals Corp Bhd's fourth quarter net profit grew a whopping 20 times compared to a year ago, driven by improved average selling price and sales volume.
    Titan registered a net profit of RM241.1 million for the quarter to December 31 2006 compared with the same quarter in 2005's figure of RM12 million.

    Average selling price grew by 14 per cent, while sales volume grew by 17 per cent.

    Revenue also grew by 33 per cent to RM1.5 billion compared with RM1.1 billion a year ago.

    Titan said business and consumer confidence strengthened during the period and that improved its operating profit even amid the high global crude oil prices.

    Net profit for the full year ended December 31 2006 grew two folds to RM773.2 million compared to RM319.4 million in year 2005.

    The sharp rise was mostly due to contribution of RM340.9 million from Chemical Brothers Ltd, a newly acquired unit.

    Revenue for the full year was also higher at RM5.4 billion, up 21 per cent from before.

    Meanwhile, OSK Research yesterday upgraded its recommendation on the stock, to a buy, on strong improvement in yields due to falling crude oil prices and its capacity expansion kicking in, in 2008.

    OSK Research analyst Chris Eng said Titan is expected to report three quarters of good results with oil prices going down, major shareholder Perbadanan Nasional Bhd to stop paring down its stake and foreign interest in the Malaysian market to pare down the regional discount.

    He said Titan will report bottom line growth in 2008 due to its capacity expansion.

    Titan is adding new capacity to its polypropylene plant and also debottlenecking its crackers to produce more olefins.

    A new butadiene plant will also be in place to allow Titan to capture higher margins for its C4 products.

    Titan is expected to see strong growth in the financial year 2007's net profits as margins recover this year as compared to 2006.

    Titan beat the research company's net profit and revenue forecasts of RM246.2 million net profit against RM5.2 billion in revenue for the financial year ended December 31 2006.

Nice way to highlight Titan earnings.

20-fold increase in earnings.

I wonder if the stock would increase 20-fold too?

Blogged on this stock last night: Oh Titan

Read more...

Oh Titan

Titan just released its quarterly earnings. Here's a news report posted on Titan's earnings:


  • Titan's net profit up 142% to RM773m
    By Joyce Goh

    Titan Chemicals Corp Bhd's net profit rose 142% to RM773.18 million for the year ended Dec 31, 2006 from RM319.4 million a year earlier, on improvement of naptha and polymer margins.

    In addition,
    the excess of the group’s interest in the net fair value of acquired company Chemical Brothers Ltd was also recognised, raising after-tax profit by RM340.9 million, the company said on Feb 13.

    Revenue for the year just ended was RM5.45 billion, up 21.11% from the RM4.5 billion achieved in 2005.

    Titan noted that the rise in the average selling price and sales volume by 14% and 17% respectively had contributed to the growth in sales revenue, driven by continued strong market fundamentals.

    For the fourth quarter ended Dec 31, 2006, Titan's net profit soared to RM241.12 million from RM12.01 million during the same period last year. Revenue was RM1.53 billion from RM1.15 billion.

    Titan expects its performance for the first quarter of 2007 to be satisfactory with the demand for polymer products continuing to be strong and the margin for the business expected to remain stable.

    Titan has recommended a final tax-exempt dividend of 4.5 sen per share for the year ended Dec 31, 2006.

So good?


  • Titan Chemicals Corp Bhd's net profit rose 142% to RM773.18 million for the year ended Dec 31, 2006

Quarterly rpt on consolidated results for the financial period ended 31/12/2006


Ok, what does the investor get from a company that just made RM773 million?


Well, the loans decreased.


Total loans is at 1,544,626 versus 1,643,010.


Bravo!


Much improvement.


But take a look at the cash flow... look at the very end balance...


Cash and cash equivalent at end of the period is only 16.925 million?

So much did Titan made?

Past postings:

  1. Titan
  2. Titan: Part II
  3. Titan: Part III
  4. Titan: Part IV
  5. Titan: Part V
  6. Titan: Part VI

Read more...

Titan: Part VI

Tuesday, August 8, 2006

Titan's 2Q net profit down 70% to RM30m
By Alfean Hardy, 08 Aug 2006 7:04 PM

Titan Chemicals Corporation Bhd's net profit plunged 70% to RM30.26 million for the second quarter ended June 30, 2006 from RM102.21 million a year ago, but it expects a better second-half performance due to tightness in the Asian market supply for its polymer products.

TITAN CHEMICALS CORP. BHD.
Quarterly rpt on consolidated results for the financial period ended 30/6/2006

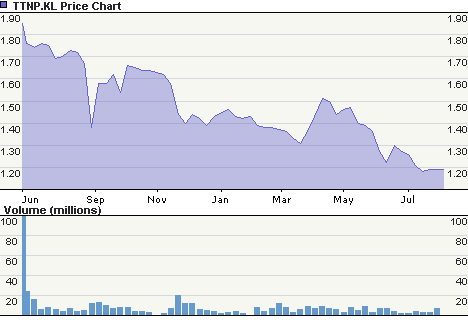
Titan last traded at 1.18!

This pictures says it all... err...


past blog postings:


Titan
Titan: Part II
Titan: Part III
Titan: Part IV
Titan: Part V

___________________________________

So here is Titan's earnings since listing:

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 37.070 million.

2006 Q2 net profit 30.262 million. (announced today)


Out of those blog postings, this one says it all.


--------------------------------------------------------------------------------
Titan: Part V

TITANic Bull Again?


Titan Chemicals announced its earnings yesterday. And this is how Titan has performed since listing.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 378.070 million.

The earnings look rather decent and it got some of the local news all excited. The Business Times has this header: Titan Chemicals Q1 net more than doubles; while the Star Business has this header: Titan first quarter profit up 149% to RM378m

Now the issue is 'the inclusion of a RM341mil non-recurring income from consolidation of its acquisition of PT Titan' which is nothing but mere accounting profit.

And if you minus this 341 million out, this is how Titan did since listing.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 37.070 million.

Which isn't all that bad but what irks me the most was mentioned in my initial blog on Titan


Now this is a company which sold itself to the investing public based on a repeated promise that it would earn some 604 million for its fiscal year 2005!


And how is Titan doing?

Oh, for those who like figures, let me be really cynical. Say we give Titan a helping hand, yeah spot the bugger a handicap of one extra quarter earnings. Guess what? If we add up these 5 quarterly earnings, Titan only earned 398.902 million. How? Can you imagine that with one extra quarterly earnings, Titan earnings is still no where close to the 604 million it promised during its IPO!!!!!!

Oh and the trailing earnings is a mere 239.602 million!

Yes, it is not easy making an earnings projection but when the projected earnings is so way off as in the example of Titan, it really makes you wonder. And worse still, those poor ipo investors bought Titan based on these incredibly optimistic earnings projections!

So how about the SC coming down really hard on buggers who make such incredibly optimistic earnings projections

How brown cow?

Read more...

TITANic Bull Again?

Wednesday, May 24, 2006

Titan Chemicals announced its earnings yesterday. And this is how Titan has performed since listing.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 378.070 million.

The earnings look rather decent and it got some of the local news all excited. The Business Times has this header:
Titan Chemicals Q1 net more than doubles ; while the Star Business has this header: Titan first quarter profit up 149% to RM378m

Now the issue is 'the inclusion of a RM341mil non-recurring income from consolidation of its acquisition of PT Titan' which is nothing but mere accounting profit.

And if you minus this 341 million out, this is how Titan did since listing.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 37.070 million.

Which isn't all that bad but what irks me the most was mentioned in my initial blog on
Titan.

Now this is a company which sold itself to the investing public based on a repeated promise that it would earn some 604 million for its fiscal year 2005!

And how is Titan doing?

Oh, for those who like figures, let me be really cynical. Say we give Titan a helping hand, yeah spot the bugger a handicap of one extra quarter earnings. Guess what? If we add up these 5 quarterly earnings, Titan only earned 398.902 million. How? Can you imagine that with one extra quarterly earnings, Titan earnings is still no where close to the 604 million it promised during its IPO!!!!!!

Oh and the trailing earnings is a mere 239.602 million!

Yes, it is not easy making an earnings projection but when the projected earnings is so way off as in the example of Titan, it really makes you wonder. And worse still, those poor ipo investors bought Titan based on these incredibly optimistic earnings projections!

So how about the SC coming down really hard on buggers who make such incredibly optimistic earnings projections?

How brown cow?

Read more...

Really Titanic Bull!!

Wednesday, February 22, 2006

This is how Titan performed on a quarterly basis.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million
2005 Q4 net profit 19.282 million.

Take a look at the numbers. It takes no rocket scientist to see that on a quarterly basis, Titan's net profits are DECLINING drastically.

159.3 -> 111.3 -> 71.924 -> 19.282???

And some might view such decline as ALARMING!

Let's look at what's been mentioned in today's financial news.

1. From Business Times:
Titan net profit rises to RM362m

  • TITAN Chemicals Corp Bhd yesterday said high oil prices were the reason for the 40 per cent shortfall in net profit for the year to December 2005 against what it forecast in its listing propectus. Despite the shortfall, however, net profit at Malaysia's largest petrochemical firm was 38 per cent higher than a year ago.
Firstly, that 38 percent higher than a year ago is a NON issue. No one forced Titan to boldy forecast that optmistic earning forecast. Or did some one forced Titan to boldy forecast its earnings will more than double the very year it seeks listing? So whose fault was it? Well, I have no idea but when Titan misses its promised earnings by a whopping 40%, I do feel sorry for them IPO investors of Titan, for they have bought a stock based on a grossly optimistic earnings projection.
  • Titan has decided to offer another 3 sen dividend to its shareholders, on top of the interim dividend of 3 sen declared earlier.
Hmm... would I be wrong to say that Titan is trying to offer more dividends as a sweetener to divert attention from its failure to deliver what was promised?

  • Managing director Donald M. Condon Jr expects 2006 to be a good year for the company as demand for polymer strengthens and oil price stabilises
Yet another classical Philip Fisher example (see Management Integrity )The company's earnings is DECLINING AT A DRASTIC pace. Instead of explaining clearly and precisely wat happened, this drastic decline of earnings appears to be a non-issue. Not even a mention. See how the company focused on the issue of record earnings? See how the MD chose to focus on the future and gives optmistic expectations yet again?

Ok... here is the version from
Star Biz

  • “We were able to keep up our good momentum for 2005 as a whole because we operated very efficiently. Our continued efforts to improve day-to-day running were also showing good results,” he said.

Good results?

A net profit that declined from 159.3 -> 111.3 -> 71.924 -> 19.282???

How could the above results be deemed as good results?

ps...

Did you all know that Titan's quarterly earnings was so drastically poor, declining at such an alarming rate?? If I had not post this fact, would you be thinking that this was just a simple issue of Titan not delivering what it promised in its IPO?

Oh... someone mentioned this to me before...

The higher the IPO forecast, the more money is generated and the more profit for everyone involved.

True ah?

Read more...

Titanic Bull Again!

Flashback (see Titan ):

LOL!!!!

It's just normal.

Just prior to their listing, during their ipo period, these companies would promise their prospective investors heaven and earth. Bright future prospects with optimistic earnings growth.

And of course, needless to say, their merchant bankers, marketing their ipo, were just as optimistic.

Oh... i am talking about Titan Chemicals.

Here are some of the optimistic claims made on the local news media.

  • Friday May 27, 2005
    Titan confident of meeting 2005 profit forecast
    SURAJ RAJ

    TITAN Chemicals Corp Bhd is optimistic that it can meet its net profit forecast of RM604mil for the financial year ending Dec 31, 2005.

    “Based on an annualised first quarter net profit, we have exceeded the forecast,” said chief financial officer Fauzi Ghani at a ceremony to launch the company's prospectus in Kuala Lumpur yesterday.

After being listed, the company made its 2005 Q2 earnings report on Aug 25th. It reported a net profit of 111.326 million for the quarter, giving it a year-to-date total net profit of 270.585 million.

And of course the company was very upbeat the day it released its earnings.

This was one of the headlines.

  • Friday August 26, 12:38 PM

    Malaysia Titan sees strong profit margin until 2009

    KUALA LUMPUR, Aug 26 (Reuters) - Malaysia's Titan Chemicals Corp said on Friday it expects its strong profit margin to continue until 2009.

    Managing director Donald M. Condon Jr says Titan Chemicals has been largely unaffected by the surge in oil prices because it is able to pass growing costs to customers

And here is a snippet from another article.

  • Titan on track to meet financial goals
    By KANG SIEW LI
    September 5 2005

    TITAN Chemicals Corp Bhd, Malaysia’s largest petrochemical company, said it remains on track to meet or exceed its financial goals for the full year, allaying concerns over the negative effect of higher oil prices on the company.

==>>>

22/2/2005

Titan just announced its earnings tonight.

And how much was promised by Titan again? RM604 million.

And how much did Titan deliver? RM361 million.

Just saw this shocking news article: Titan posts record earnings of RM361m

Record earnings? Excuse me, Titan was SOLD to the investing public in a titanic IPO worth some rm950 million. And the whole valuation was based on the fact that Titan itself gave a promise that it would deliver some rm604 million in net earnings. And how much did Titan deliver? rm361 million!

Here is some titanic stuff from that article..

  • Speaking at a media briefing in Kuala Lumpur on Feb 22, Titan managing director Donald M. Condon Jr attributed the impressive results to the strong first-half performance.

Well I am impressed, aren't you?

  • On the performance of Titan’s share price: “We do think our share is undervalued. That’s why we’ve put together a share buyback plan. The plan will be put in place depending upon how the share continues to do in the market.”

Undervalue? Did he say undervalue?
Titan clsoed the day trading at rm1.35.
What was Titan IPO price? rm2.17!
!!!!

Here is the summary of Titan's earnings from yahoo news..


Titan Chemicals Corp. Bhd. (5103.KU) - Malaysia

4Q ended Dec. 31:

Figures are in Ringgit

2005 2004
Revenue MYR1,145,187,000 MYR1,159,388,000
Pretax Profit 34,938,000 248,514,000
Net Profit 19,282,000 119,756,000
Earnings Per Share 1.24 Sen 9.11 Sen
Dividend 3.00 Sen Omitted

12 months ended Dec. 31:

Revenue 4,497,571,000 3,555,088,000
Pretax Profit 503,197,000 544,241,000
Net Profit 361,781,000 262,263,000
Earnings Per Share 23.31 Sen 19.95 Sen
Dividend 6.00 Sen Omitted

Read more...

TITANic Bull Part II

Wednesday, November 23, 2005

Well, Titan closed yesterday at 1.44. (ahem!)

What is most interesting is that the Star has another write-up on Titan:
Titan dips on expectation profit may fall short

Here's some of my comments on it.

1. The IPO price was priced at 1.77. (me was mistaken lah. I thought is was 2.17!!)

2. No mention on why Titan's IPO projection earnings for fy 2005 was soooooooooo optimistic.

3. The article focused on non-issues like sales growth. Duh! Sales growth so important meh?

4. Article suggested Titan has a share buyback which might limit the downside risk.

Now the last suggestion for me is totally nonsense.

Yes, share buyback can at times lend a boosting hand to a stock price and ultimately engineering a share price support and even a share price appreciation.

However... for me, it counts for nothing... it does not add extra 'value' to the company's fundamental value. And if and when Ze market deems a share not its worth, a company's share buyback will not stop a share price decline if and when Mr.Market heads for the exit. If so, how does one define might limit downside risk?

A good example? Take MPI. Many, many moons ago when MPI started its slide from its high, the company embarked on a share buyback in an attempt to support the shareprice around the RM30.00 region. Look at MPI's price now?


Sooo.... if and when a company has a share buyback program.... do u think it is wise to .... err..... errr.... (lol...lol...lol...... yeah.... here comes Posexpress favourite!) A S S - U - M E that the downside risk will be limited?

:D

Read more...

TITANic Bull!

Tuesday, November 22, 2005

LOL!!!!

It's just normal.

Just prior to their listing, during their ipo period, these companies would promise their prospective investors heaven and earth. Bright future prospects with optimistic earnings growth.

And of course, needless to say, their merchant bankers, marketing their ipo, were just as optimistic.

Oh... i am toking about Titan Chemicals.

Here are some of the optimistic claims made on the local news media.

Friday May 27, 2005
Titan confident of meeting 2005 profit forecastY
SURAJ RAJ

TITAN Chemicals Corp Bhd is optimistic that it can meet its net profit forecast of RM604mil for the financial year ending Dec 31, 2005.

“Based on an annualised first quarter net profit, we have exceeded the forecast,” said chief financial officer Fauzi Ghani at a ceremony to launch the company's prospectus in Kuala Lumpur yesterday.
After being listed, the company made its 2005 Q2 earnings report on Aug 25th. It reported a net profit of 111.326 million for the quarter, giving it a year-to-date total net profit of 270.585 million.

And of course the company was very upbeat the day it released its earnings.

This was one of the headliners.

Friday August 26, 12:38 PM

Malaysia Titan sees strong profit margin until 2009

KUALA LUMPUR, Aug 26 (Reuters) - Malaysia's Titan Chemicals Corp said on Friday it expects its strong profit margin to continue until 2009.

Managing director Donald M. Condon Jr says Titan Chemicals has been largely unaffected by the surge in oil prices because it is able to pass growing costs to customers
And here is a snippet of another article.

Titan on track to meet financial goals
By KANG SIEW LI
September 5 2005

TITAN Chemicals Corp Bhd, Malaysia’s largest petrochemical company, said it remains on track to meet or exceed its financial goals for the full year, allaying concerns over the negative effect of higher oil prices on the company.

Titan announced its 2005 Q3 earnings last nite.

Net profit was 71.914 million (the previous quarter it made 111.326 million! Ahem!), giving it a total net profit of 342.499 million.

Ahem.... one quarter left for the fiscal year... and they had just promised not too long ago that they can boleh-out a PROMISED net profit of 604 million to their ipo investors.

Let me put it clearer..... 2005 Q4 net profit + 342.499 million = 604 million wor.

Which means...2005 Q4 net profit should be around 261 million.

Ahem... which looks very, very unlikey.... prompting Titan to fast-fast sing-out that
it may not meet its 2005 IPO forecast. In fact it now warns that net profit for full year 2005 may fall 25% to 30% below its initial public offer (IPO) forecast of RM604.1mil.

Like this how cannnnnnnnnnnnnnnnnn??????

Belum listed, they can promise all the sweeties in the whole world.

After listed.... ahem!

Here is a table from OSK during Titan's ipo.


Quote:
Fair value of RM2.50Applying our fair PER of 7x to CY06 EPS, we derive a fair value of RM2.50.


That above table was from OSK.


1. Look at net earnings row.
See 2004 ~~~~~>>>> 2005.
see how net profit TITANICALY ROSE from 262.2 mil to 604 mil? LOL!!! Dun u forget, this was Titan's promised earnings wor!

2. see how OSK priced the IPO? It assigns a fair value of 2.50 based on Titan's projection to make a net profit of 624 million for fy 2006.

Ahem! Simply TITANIC cause now Titan is saying (warning) that it may not even meet its 2005 net profit forecast.

If 2005 tak boleh, then 2006 boeh ka?
If tak boleh, then what does this means about the IPO price sold by Titan to their IPO investors?

Titan is now trading at 1.49. IPO price? Errr.... if not mistaken was 2.17 wor!

How can?

See how the game is being played?

It's like when we go pak-toh-ing. During pak-toh, everything olso can. But after that, if and when we get Mary, ho ho ho..... !!!!

So next time got new IPO...
better see properly first lah b4 we say 'I wan! I wan!'

Tiok boh?

Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP