Powered by Blogger.

Home

Is Investing In Defensive Stocks A Good Strategy?

Tuesday, August 8, 2006


This is something I always find so amusing.

When we invest in a stock, it's only commonsense because we find that the stock represent a truly wonderful business and we are given an opportunity to invest in it a great price.

Defensive stocks? LOL!

What about Offensive stocks?

Do you reckon investing in defensive stocks just because they are 'defensive' stocks a good, 100% safe strategy during a bear market?

Anyway I am writing this post because of the comments written by Frank Barbera posted on FSO market-wrap. What is truly great is that he came up with hard facts to back what he is saying.

Enjoy!

link to article

Read more...

Titan: Part VI

Titan's 2Q net profit down 70% to RM30m
By Alfean Hardy, 08 Aug 2006 7:04 PM

Titan Chemicals Corporation Bhd's net profit plunged 70% to RM30.26 million for the second quarter ended June 30, 2006 from RM102.21 million a year ago, but it expects a better second-half performance due to tightness in the Asian market supply for its polymer products.

TITAN CHEMICALS CORP. BHD.
Quarterly rpt on consolidated results for the financial period ended 30/6/2006

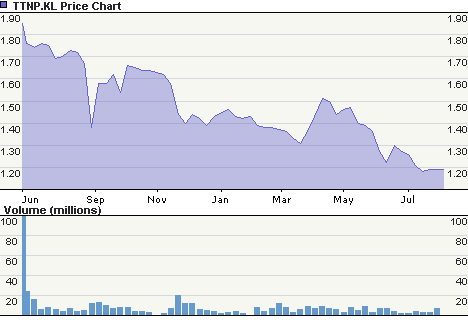
Titan last traded at 1.18!

This pictures says it all... err...


past blog postings:


Titan
Titan: Part II
Titan: Part III
Titan: Part IV
Titan: Part V

___________________________________

So here is Titan's earnings since listing:

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 37.070 million.

2006 Q2 net profit 30.262 million. (announced today)


Out of those blog postings, this one says it all.


--------------------------------------------------------------------------------
Titan: Part V

TITANic Bull Again?


Titan Chemicals announced its earnings yesterday. And this is how Titan has performed since listing.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 378.070 million.

The earnings look rather decent and it got some of the local news all excited. The Business Times has this header: Titan Chemicals Q1 net more than doubles; while the Star Business has this header: Titan first quarter profit up 149% to RM378m

Now the issue is 'the inclusion of a RM341mil non-recurring income from consolidation of its acquisition of PT Titan' which is nothing but mere accounting profit.

And if you minus this 341 million out, this is how Titan did since listing.

2005 Q1 net profit 159.3 million (not listed yet)
2005 Q2 net profit 111.326 million.
2005 Q3 net profit 71.924 million.
2005 Q4 net profit 19.282 million.
2006 Q1 net profit 37.070 million.

Which isn't all that bad but what irks me the most was mentioned in my initial blog on Titan


Now this is a company which sold itself to the investing public based on a repeated promise that it would earn some 604 million for its fiscal year 2005!


And how is Titan doing?

Oh, for those who like figures, let me be really cynical. Say we give Titan a helping hand, yeah spot the bugger a handicap of one extra quarter earnings. Guess what? If we add up these 5 quarterly earnings, Titan only earned 398.902 million. How? Can you imagine that with one extra quarterly earnings, Titan earnings is still no where close to the 604 million it promised during its IPO!!!!!!

Oh and the trailing earnings is a mere 239.602 million!

Yes, it is not easy making an earnings projection but when the projected earnings is so way off as in the example of Titan, it really makes you wonder. And worse still, those poor ipo investors bought Titan based on these incredibly optimistic earnings projections!

So how about the SC coming down really hard on buggers who make such incredibly optimistic earnings projections

How brown cow?

Read more...

Commentaries from The Big Picture.

Monday, August 7, 2006


Read some interesting comments from the transcripts of The Big Picture program. ( link )


Regarding oil:

Ok, as Joe Friday said, “Just the facts, Ma’am.” Let’s start out with a few simple facts. And one thing that people have to understand is in the last 3 years, where we’ve seen oil prices go up from the mid-20s to today’s price somewhere in the 73 to $74 range, demand worldwide has grown unabated for the last 3 years, unaffected in any way by rising prices. If we look at the United States, in the first half of 2006, we reached a 20 year high in US drilling activity. So it’s not like the oil companies are standing by saying, “look, we’re making lots of money, but, you know, hey, tough, that’s the way it is.” No, with their drilling activity, their amount of capital expenditures is at near records.

But here’s the thing that I think these news people do not put in perspective. This is it in a nutshell. In 1985, the world consumed 60 million barrels a day of production; we also had 70 million barrels of capacity for production. In other words, John, we had a spare capacity of 10 million barrels a day between what we could produce and what was demanded by the world.
Also, in 1985, capacity at our nation’s refineries was running at 78%, so if there was more demand our refineries could crank up and produce more gasoline; if there was a problem in the Middle East, if a refinery went down, we had 10 million barrels of spare capacity. They could handle anything like a war in Lebanon, rebels in Nigeria, a refinery catching fire in Venezuela. Today, oil demand is running at 85 million barrels a day; refinery capacity is at over 92%
today; and spare capacity has dwindled to somewhere between 1 and 2 million barrels a day. And that is the main picture in a nutshell.


And on the issue of 'Soft landing' (is it ever possible to have a manufactured 'soft landing'?)

Soft Landing or Has the car gone off the cliff?

  • SEN. CLINTON: A lot of Americans can’t work any harder, borrow
    any more, or save any less. And those same costs of health care, retirement,
    transportation, energy are impacting our businesses as well.
    It’s time for a new
    direction: 5 years we have lived with deficits, this agenda will help bring back
    fiscal responsibility.

JOHN: That was Senator Hillary Clinton from New York, Jim, speaking this week at a private speech, and she’s keyed the first part correctly – I’m not sure the second part is a realistic appraisal given how bad the deficit is, but she does reflect the problem that the Fed has. We seem to be stuck between – well, an old sailing term, Scylla and Charybdis. Remember that?
The Straits of Messina between Sicily and Italy. They can’t go one way, they can’t go the other, and everyone is beginning to feel the pinch as the Fed has been tightening everything up. So the real big question, right now, are we experiencing a soft landing or have we just yelled, “Geronimo,” and gone off the cliff.

JIM: You know, John, it is amazing what a difference a quarter makes. I mean if you take a look at the GDP numbers reported on Friday, growth has gone from 5.6% in the first quarter to just barely below 2 ½%. And one of the reasons for that slowdown is a dramatic shift in consumer spending. The downturn in consumer spending is accelerating. And why is that? Number one, the savings rate has been negative, so there is no cushion for consumers to offset what it is they’re receiving in income; wages have not kept pace with inflation. And that was Ok, as long as the price of the family castle was going up, and you can extract equity out of the family castle, and then refinance at a lower payment. So, that was the fuel that was sort of feeding this consumption, or increase in consumption, that we’ve seen in the last 3 years. That’s because one of the unusual characteristics about this economic recovery from the 2001 recession is that the consumer accounted for 80% of GDP growth the last 3 years.

Today’s dramatic slowdown is showing the accelerating impact of all those 17 rate hikes, meaning that anybody that got an adjustable rate mortgage in 2003 is seeing their mortgage probably adjust this year; there’ll be even more mortgages adjusted according to the National Association of Mortgage Brokers. The average family has seen their house payment go up by $400. And John, you know we’re dealing with $3.50 gasoline. So gasoline costs have gone
up, interest rate costs have gone up, the cost of food, inflation rates are up, so the cost of living is going up for consumers while labor wages are falling further behind the rate of inflation.

Now that's the BiG picture!

Read more...

GM and The Working Group

Thursday, August 3, 2006

There is this very interesting piece posed on LewRockwell.com ( here )

It first talks about the Plunge Protection Team or The Working Group:


The New York Post recently ran a piece on Washington’s tight-lipped Plunge Protection Team, or, the "Working Group," as it is formally known. Essentially, the role of this group is to prevent another 1987 "Black Monday" in the stock market. It was put into law in 1988, as Executive Order 12631, by Ronald Reagan. If you read the Executive Order you’ll note that it essentially allows the government to intervene in the stock market – should a crash or foreseeable dip appear to be on the horizon – via legislative law, administrative fiat, or the manipulation of private bodies via coercive tactics on the part of the Federal Reserve, Treasury Department, or the executive office. Section Two of the order states that its purpose and function is to recognize "the goals of enhancing the integrity, efficiency, orderliness, and competitiveness of our Nation's financial markets and maintaining investor confidence."

The Working Group was established in order to identify issues – which studies have vetted out – in regards to the events surrounding the 1987 market crash. Its purpose is to gather recommendations from anointed experts and consider what government actions, under existing laws and regulations, can be undertaken in order to carry out those recommendations. The last step is to "appropriately consult" with private sector bodies and participants in order to seek any possible private solutions. These "private solutions," however, will come from puppet organizations of the corporatist establishment.


And the author, Karen De Coster, has these comments on General Motors.


On May 24, 2006, at the behest of the Working Group (in our opinion), Merrill Lynch came out with a "buy" recommendation pertaining to General Motors’ stock. Keep in mind that this recommendation was made fully one month before Tracinda recommended that GM explore the idea of forming an alliance with Nissan and Renault. Shamefully enough, Merrill’s rationale hinged upon the premise "…that the automaker's restructuring plans, specifically the number of workers taking buyout packages, are coming along ahead of schedule." This is nothing short of harebrained reasoning serving the demented ends of the Working Group.

It is highly unusual for a restructuring plan that is so far away from accomplishing anything substantial to get such a standing ovation, even from the fraudulent Wall Street analysts. This move by Merrill Lynch is a hoodwink designed to keep the confidence level high among investors speculators, thus keeping under wraps any unwanted drama or uprising from the unsuspecting masses. In fact, if Johnny Beer Drinker could read a balance sheet, he'd bail out of GM's stock immediately. But Johnny Beer Drinker can't read a balance sheet; he may watch CNBC and
Jim Cramer, and if he does, he is a blind fool following a bullish fool who is serving up bad advice to serve his own interests.

Since Merrill Lynch’s pronouncement, GM’s stock has shown market leadership like a four-star general – it was up by 40.1% during the second quarter of 2006, making it the best performing Dow stock for the three-month period ending June 30th. Even on days where the Dow Jones Industrial Average had declined by over 100 points, the "General’s" stock held steady. One day, it was even up by over 4% when the market swooned terribly – and this in spite of the fact that gasoline prices are at $3.00 per gallon. We have little doubt that GM stock is being accumulated by Caribbean-based hedge funds owned and operated by the Federal Reserve – the very same folks who mysteriously emerged as buyers of U.S. Treasury debt (thus, keeping interest rates down) when other buyers began to shy away from that debtaholic Uncle Sam. For now, the General looks unbeatable – as long as "investors" believe the stock is the company.

When examining General Motors’ March 31, 2006 balance sheet, what comes to mind is not a proud general, but a bloated inmate of a debtor’s prison. It is boggling that any financial analyst would recommend purchasing the common stock of a company with the following financial profile:


  • General Motors’ automotive operations have a combined working capital position of deficit $15.4 billion.
  • GM has total debt and liabilities approaching half-a-trillion dollars.
  • GM’s total liabilities to equity ratio is 29 to 1. There once was a day when financial analysts sounded the alarm bells when this ratio exceeded 4 to 1.
  • Arguably, GM has a deficit net worth of $18.2 billion. Such a sobering conclusion can be deduced simply by disallowing intangible assets such as goodwill and deferred tax assets.

It is interesting to note that GM’s market capitalization was recently at $12.4 billion, which is smaller than that of Harley-Davidson, about equivalent to the market cap of Hershey Co., and in comparison, Toyota’s stands at $194.7 billion. With such a weak balance sheet, GM will not survive a recession. Hence, bankruptcy is a possibility – even if the aforementioned alliance with Nissan and Renault is consummated. GM’s banks understand this and have required that General Motors provide additional collateral in order to keep open a $5.6 billion operating line of credit. On the heels of this move by the banks, Standard & Poor's and Moody's cut GM's senior unsecured debt rating even deeper into junk territory. For the banks’ collateral-call and the debt downgradings to occur shortly after such a high-profile recommendation to buy GM stock, Merrill Lynch’s top executives should be embarrassed.

Ah, but the top dogs at Merrill Lynch have no shame and will sleep well. They know that most Americans don’t pay attention to the corporate bond market nor the backroom dealings of bankers. It is the Dow Jones Industrial Average that grabs the attention of Americans. By keeping the Dow up, the Plunge Protection Team – as assisted by Merrill Lynch – understands that it is making a key contribution to the insanely expensive game of "bread and circuses" Uncle Sam is playing with its citizens. Consequently, the Federal Reserve will conjure up as much fiat money as possible in order to intervene in, and prop up, the stock market so as to keep our collective confidence elevated – and, in the mind of these Keynesians, the economy will be peachy. Ultimately, and Bill Gross not withstanding, why is GM stock a selected target of the Plunge Protection Team? As GM’s CEO Charles E. Wilson famously stated in 1953: "…because for years I thought what was good for the country was good for General Motors and vice versa."

Take a look at GM's two year chart. Look how a plunging stock staged a remarkable turnaroun in May despite any change in its fundamentals.


Read more...

Litespeed

Monday, July 31, 2006

Posted on this before: Posted this one before: (see Not meeting forecast )

So they have NOT made a single sen since listing on the MessDaq.

And if you think that is bad, take a look at this:

Litespeed CEO sells 1.1m shares

Mesdaq-listed Litespeed Education Technologies Bhd chief executive officer Pok Vic Tor disposed of 1.12 million shares on July 19.

A filing to Bursa Malaysia showed that after the disposal of the 0.81% stake, his direct interest was reduced to 26.9% or 37.12 million shares.

The company is an e-learning provider involved in the design, development and distribution of e-Learning products and services for the regional market.

Its share price closed at 17.5 sen on July 19

-------------------

Isn't it so darn disgusting? List an absolute crap company and yet by selling his shares, he makes millions!!!


Read more...

TechnoDex Bhd


Saw this posted on the EdgeDaily.com
---------------------------------------------------------------------------------

TechnoDex expects net profit of RM7m for FY07

By Gan Yen Kuan

Mesdaq-bound TechnoDex Bhd, a business technology provider specialising in open source solutions, expects to achieve a net profit of RM7.02 million on the back of RM12.46 million in revenue, for the financial year ending June 30, 2007 (FY07).

The projection represents a 60% jump in revenue and 40% in net profit, compared with the targeted revenue and net profit of RM7.78 million and RM5.01 million respectively for FY06. TechnoDex managing director and chief executive officer Nigel Lee said the projection was based on the wide interest in the company’s products. He said that the company would leverage on its matured technology platform and products to boost sales.

Compare that to what was printed in Star Business: TechnoDex to triple net profit


TECHNODEX Bhd, which is targeting a Mesdaq listing next month, is confident of reporting a net profit of RM5mil for the financial year ended June 30, 2006 – more than triple the previous year's net profit of RM1.4mil. Chief executive officer Nigel Lee Siew Tat said the better earnings would be mainly due to the value-added features introduced for its core product, the TechnoDex Enterprise Solution Platform.

He said the platform was an open source-based software that provided the flexibility and scalability for application developers to customise their solutions structure as well as business model to meet market needs. “The product has played an important role in widening our local customer base,” he told StarBiz in an interview.

--------------------------------------------------

Huh?

The Edge: Mesdaq-bound TechnoDex Bhd, a business technology provider specialising in open source solutions, expects to achieve a net profit of RM7.02 million on the back of RM12.46 million in revenue, for the financial year ending June 30, 2007 (FY07).

The Star: TECHNODEX Bhd, which is targeting a Mesdaq listing next month, is confident of reporting a net profit of RM5mil for the financial year ended June 30, 2006 – more than triple the previous year's net profit of RM1.4mil

Fantastic isn't it?

See where the PROBLEM is?

Remember the recent articles about companies not meeting their IPO numbers?

Read more...

Yung Kong: Part II

Wednesday, July 26, 2006

Wrote on this stock before: here

Yung Kong just announced it's earnings and it did not lose money.

YUNG KONG GALVANISING INDUSTRIES BHD
Quarterly rpt on consolidated results for the financial period ended 30/6/2006

Well, it's only right that I made this short note.

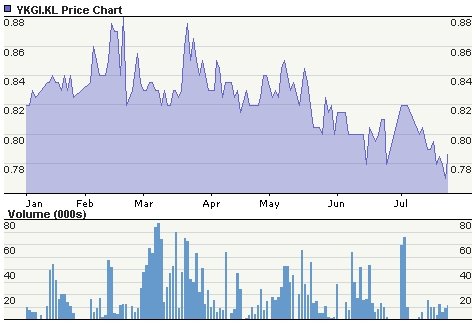
And just for the record, here is how the stock is performing.


Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP