Powered by Blogger.

Home

Good fund manager(s) makes a difference.

Monday, October 23, 2006

Star Business had been running a series of articles on Investing. I truly enjoyed it...

But...

Take a look at the following comments.

  • In this final part of our weekly series exploring investment opportunities, we look at options for a person who has at least RM1mil to invest.

    WHILE there are a variety of investment products in the market, their performance is subject to the expertise of the fund manager.

    According to Singular Asset Management chief investment officer Teoh Kok Lin, there is increasing accessibility to products as more and more products are being “unitised”; hence the fund manager “makes the difference.”

    A fund manager would be able to customise products according to the client's risk appetite and portfolio, he said.

    How a fund manager manages risks depends on his investment philosophy. Some focus on value while others on growth, he said.

    While the philosophy could be similar, how they implement it would be subject to their individual characteristics, he added.

    For Teoh himself, he looks for value in specific companies that are “unloved and unpolished gems.”

    On selecting a fund manager, he said it was important to look at the track record and the kinds of risk that the funds were undertaking.

    AmInvestment funds management division chief executive officer Datin Maznah Mahbob shared similar views.

    “Usually we look at the fund manager's track record over one year, three and five years,” she said.

Ok, I really DO agree that the fund manager makes a huge difference.

But..

In this industry, the fund management industry, good talent is limited. And worse still, these good ones they do not stay with a fund for a long time. Sometimes better job opportunity is available or offered and these fund manager(s) could switch for a better paying career. It's a possibility.

So for us, the investor, knowing and insisting that our funds, our hard-earned money is managed only by the best fund manager is a must but the investor should never discount the possibility that the TOP GUN fund manager will manage our funds forever and ever. Fund managers could always switch to another job.


Read more...

Kirby's Blast From the Past.

Read this article. Thought I share with everyone here.

A BLAST FROM THE PAST AND MORE

Former Fed Chairman Alan Greenspan had a few “choice” words for his Russian counterparts late last week when he warned them that their refusal to allow the Ruble to meaningfully appreciate against the dollar may have inflationary consequences.


Greenspan Warns
Russian Authorities Against Investing in U.S. Dollar
Created: 20.10.2006 12:52 MSK (GMT +3),
Updated: 15:43 MSK
MosNews
Russia should be wary about the inflationary impact of buying U.S. dollars to insulate its economy from an influx of foreign earnings from oil exports, former Federal Reserve Chairman
Alan Greenspan said on Thursday, Oct. 19
.


Tulips Come To Mind...

Greenspan went on to point out that Russia’s massive Trade Surplus – owing to 600 million per day in oil revenue – [implied] should naturally lead to a rising domestic currency as petrodollars are repatriated – an event or process dubbed “Dutch
Disease.”


Dutch Disease refers to the potential negative long-term impact of one explosive sector —- oil, in the case of Russia —- which boosts the value of the currency, making locally produced goods less competitive compared to foreign goods.


He warned that artificially depressing their currency to cure “Dutch Disease” – by buying foreign currencies like dollars - could lead to inflationary problems down the road.


The Russian Central Bank has intervened in the foreign exchange market by buying U.S. dollars to slow the ruble’s growth. The move, however, fuelled money supply growth of about 45 percent and inflation of around 10.9 percent in 2005.


Wow, money supply growth of 45%. That sure sounds inflationary, doesn’t it? Me wonders whether that 45% growth rate refers to the Russian equivalent of M3? That would be the very same measure of money supply that Sir Alan banished in the U.S. - as one of his last official acts as Chairman of the Federal Reserve – isn’t it?

Anyhow, Greenspan goes on to “speculate” about the Ruble’s future prospects as a “potential” Reserve Currency – and he points out how important the “rule of law” is – as a fundamental precondition for such an occurrence. Me wonders, again, speaking of rules in law - if he might be referring to such fundamental things as “habeas corpus” – an inalienable, basic human right since the 12th century that the U.S. recently discarded. Who knows, Greenspan always did have a way with words – didn’t he?

Read more...

Tanjung Offshore reaches OSK Target!

Thursday, October 19, 2006

On 4th October, there was an article on Business Times which states the following:

  • OSK Research has raised its recommendation to a 'buy' with a target price of RM2.69..

Tanjung Offshore closed at 2.68 yesterday and is currently trading at 2.71.

There is a strange and funny regarding the way OSK recommended this stock. Take a look at the recent chain of events.

Firstly, Tanjung Offshore reported its earnings on 28/8/06.

Well, the earnings in all honesty wasn't too happening, in fact perhaps it was kind of dismal. So folks like OSK decided to give it a downgrade. Which was rather rational in my opinion.

  • Tuesday, August 29, 2006

    TAKE PROFIT
    (Downgraded)

    Price RM2.43 Target RM2.34

    Time for a Breather
That was their header of their research report. A downgrade from 2.43 to 2.34. Kinda miniscule isn't it?


Downgrade to TAKE PROFIT. Adjusting for the 1-for-2 bonus issue (ex-17 th August), TGOFFS has appreciated by 63.5% since our initiation on the 13 th of April. Although we remain positive on the company’s long term prospects, we feel that such an excellent run up presents investors with an opportunity to TAKE PROFIT while awaiting for more good news in coming months. To also note that the 46.4m shares and 9.3m warrants from the bonus issue will be listed today.

And the stock, Tanjung Offshore did fall. Well, as 'MUCH' as to about 2.32.

But....

consider this issue. What OSK did then was rather amazing. OSK then quickly released a report, upgrading it to NEUTRAL!

  • NEUTRAL (upgraded) Price RM2.32 Target RM2.34

    A More Reasonable Price

    Share Price corrected to Fair Valu
    e. Since we downgraded TGOFFS on the 29 th of August, the share price has dropped by 4.5% to a more reasonable level close to our fair value. We feel this correction was important as TGOFFS share price had run too far ahead of fundamentals at that point of time.

:s54:See the price target? 2.34!!! :s54:

Any how and any which way is also possible. They downgraded to 2.43 to 2.34 and when the stock falls to 2.32, they quickly upgraded the stock back to 2.34!!!

Makes you wonder, doesn't it?

And this was their reasoning...


Upgrade to NEUTRAL. Although we are maintaining our forecasts at this juncture, due to the reasons above and the potential upside from possible asset acquisitions, we upgrade TGOFFS back to a Neutral. We remain very positive on management and the outlook of the overall industry.


It's like... errr... why bother downgrading in the first place? Right?

And look at the frame in which all happened. That initia Downgrade was posted on 29th Aug. The UPGRADE article was then made on 7th Sept.

See how fast their opinions changed??

And then, on Oct 3rd 2006, they wrote the following. (That Business Times article was based on this write-up.)

LOL!!!!!!

here were their reasonings...

  • New Contracts. TGOFFS announced a RM10m contract to supply electrical switchgear to Larsen & Toubro for the Petronas lube oil plant in Melaka. Aside from this, TGOFFS had also announced a new contract for the provision of Siemens gas turbine maintenance services for Petronas Carigali worth RM13m for 5 years. These contracts indicate that TGOFFS is still actively seeking to grow the engineering equipment and maintenance services businesses.

    Delay in MOPU.
    .. Although the Cendor MOPU was delivered to the site on schedule, we understand that there was a 1 month delay in the production due to factors beyond TGOFFS control. The announcement of the additional 10% stake in the Cendor MOPU will also be delayed until November due to restructuring in the MOPU partners. We have only factored in contribution from the additional 10% stake in our FY07 forecasts and make no changes to this slight delay but the 1 month oil production delay reduces our MOPU GP forecast by RM0.2m.

    …offset by higher contract & margin expectations.
    Given the new contracts announced and our expectations for more contracts in 4Q, we are bumping up our engineering equipment revenue by 3.5% and our margins to 8% (previously 7.7%). We also revise up FY07 GP margins for the offshore vessel business to 45% and for drilling rig rental to 5.9% in line with industry figures. As a result, our FY07 net profit is up by 10.7% closer to management’s guidance.

    Marine vessels looking goo
    d. Pinang 3 & 4 are to be delivered to TGOFFS by mid and end October respectively. We understand that Petronas will be releasing more contracts for vessels soon and TGOFFS hopes to lock in Pinang 3 and 4 into long term contracts as well as secure other contracts before ordering new ships.

    With all 4 support vessels launched and given the strong demand forecasted for offshore vessels, we are revising our Price to Book multiple for TGOFFS from 3.0x to 3.5x. Together with our earnings upgrade, our fair value (on average of PER and P/BV) is raised to RM2.69 and
    we upgrade TGOFFS back to a BUY.

So, currently Tanjung Offshore stock price is trading well past 2.69.

I do wonder what is next.

Read more...

Puncak Niaga

Thursday, October 12, 2006

Here is an interesting news comments link.


Puncak plans cash reward for shareholders

A Puncak Niaga's director has confirmed that such a plan was discussed at a board meeting yesterday, but he declined to reveal further information
Here are some issues.

A director of the company, who spoke strictly on condition of anonymity, confirmed that such a plan was discussed at a board meeting yesterday, but he declined to reveal further information.
Hmmm... correct me if wrong but isn't this director LEAKING out insider news?

Hey, is this even allowed???


Puncak Niaga is also awaiting a bumper cash payment from the Government via a 15 per cent automatic payment which was supposed to kick off in January this year.

Under the agreement, if Puncak Niaga did not receive the increment on time, the payment would be backdated when the Government increases the water tariff and Puncak Niaga will also receive some form of cash compensation from the Government for being patient.

The big bumper cash Puncak that Puncak is waiting for...

But....

There was an article on The Edge yesterday evening.


Puncak mulls RM1.25 per share capital repayment
By Thomas Soon, 12 Oct 2006 8:51 PM

Puncak Niaga Holdings Bhd shareholders are expected to be rewarded with a bumper cash payout of RM1.25 per share on the prospects of its assets and debts being taken over by Finance Ministry-owned Pengurusan Aset Air Bhd (PAAB).
MORE

This part of the article..


Energy, Water and Communications Minister Datuk Seri Dr Lim Keng Yaik said on Oct 10 that the government would soon start to take over the assets and debts of water service operators via PAAB.
He said the pilot project would see PAAB taking over the water assets in Melaka and Negeri Sembilan by year-end via agreements with the state governments. PAAB is now talking to other state governments and "other operators like Ranhill Utilities Bhd and Syabas (have indicated interest as well)." Puncak Niaga holds a 70% stake in Syabas.
Although the new water management arrangement will turn concessionaires into mere water services operators, an analyst said Puncak Niaga would, however, still be a main water player in the country.

The govt to take over Puncak's debts and Assets????

Errr... is this even possible???

Read more...

ViTrox: How to Poop Up a Stock!!

Wednesday, October 11, 2006

Imagine.

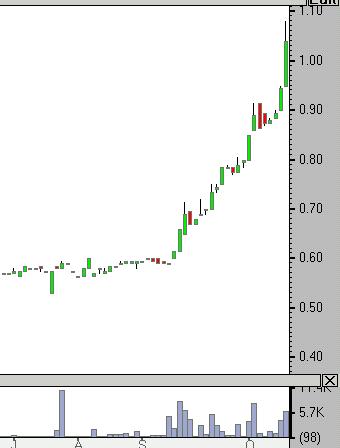
Say you have a stock that has just broken up broken its base of 0.60 and is now trading around 1.05. And this stock price appreciation was done in less than one month time.

Now imagine, you are an analyst and you are asked to give a positive comment on the stock. And of course a high Target Price for the stock.

And to make matters worse, this stock was just listed recently and back then, folks gave it an IPO fair value of just 36 sens. Remember stock is now trading at 1.05 ok?

Just imagine.

Now say this stock is earning some 2.4 to 2.5 mil per quarter. So for current fiscal year, this stock should earn some 9-10 million for its 2006 fiscal year.

Are we ready to begin our task?

Just imagine the following conversation between A (the writer) and B (the Bossie).

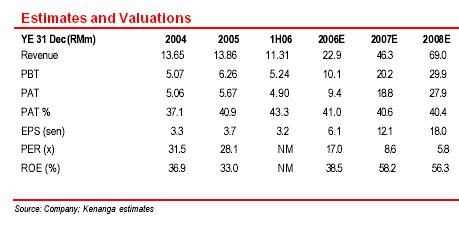
A: Bossie, I know how. I shall project fy 2007 earnings at 18.8 million for this fella. Is it enough?
B: Are you nuts? This is not going to cut it.

A: Not enough. I project the next fiscal year earnings, fy 2008, to be at 27.9 million. Is that enough?
B: Ahh... you are getting smarter each day. That's it, that's the ticket!! 27.9 million it is!! Make the target price as high as possible!
A: Ok Bossie. 1.80 enough?
B: Good boy!

Incredible isn't it?

Me think so too!!!

Look at what it is happening here.

Vitrox. A year ago.

  • ViTrox fair value at 36 sen

    September 10 2005

    SHARES of ViTrox Corp Bhd, a maker of systems that help chipmakers inspect their products, should be fairly valued at least at its reference price of 36 sen apiece, two research houses said.

    The company, which is en route for listing on Malaysian Exchange of Securities Dealing and Automated Quotation Bhd (Mesdaq) Market on September 12, had issued 17.6 million new shares of 10 sen each at 60 sen per share.

    However, it has also offered a 2-for-3 bonus issue and these bonus shares would also start trading on the first day, which means the theoretical ex-bonus price is 36 sen.

    SBB Securities Sdn Bhd has given a fair value of 36 sen a share for ViTrox while Jupiter Research put a fair value of 43 sen, a 19 per cent premium over its reference price.

Here is how ViTrox has traded..


See how nicely ViTrox has appreciated lately? The stock went zoom, zooming from 60 sen base to 1.04.

And this morning, I saw this Kenanga research on it. Well, for a stock that had clearly appreciated so much, I find it so incredible that Kenanga has managed to write such a positive write-up on it.

Here are the main points it made.

  • Home grown technology dynamo

    Company Report BUY RM1.04 Initiating Coverage (Target: RM1.80)

    12 October 2006

    l A home grown technology dynamo which is gain significant market acceptance in Asia Pacific region, Vitrox Corporation Berhad ("Vitrox") is the leading machine vision solutions provider in Malaysia, catering particularly to the semiconductor industry.

    l Rising trend of integrated circuit ("I/C") consumption especially in consumer electronics should continue to underpin demand for automation equipment and hence machine vision inspection system s.

    l Three champion products namely machine vision system, automated optical inspection ("AOI") and electronics communication (I/O cards) hardware should propel growth going forward, underpinned by strong value propositions in terms of price / performance to the end clients .

    l Extremely vibrant growth outlook with the company expected to grow a staggering 72.3% CAGR between 2006 and 2008 as the company’s new key products namely, AOI and gained traction in the market place.

    l Outstanding profitability with net margins of 40% and above as company leverage on its intellectual property in addition to 12-year tax free pioneer status.

    l Initiating coverage with a Buy. Our 12-month target price for the stock is RM1.80 using a 10x FY08 P/E instead of 8x given its explosive growth.

    Catalysts including (1) Rising demand for automation equipment, (2) strong value propositions to end clients in terms of price / performance / back-up service and (3) sterling CAGR of 72.6% in the next two years.

See how the 12-month target price is at 1.80 and is based on FY2008 earnings estimates?

Well have a look at the table below to see how nicely they project this fy2008 earnings.


Read more...

Why NO Interest?

Saturday, October 7, 2006

Here is some market commentary posted on Star Biz..


Equity Market outlook
On paper, it would appear that the local stock market is headed for better times, with easing fears about higher domestic interest rates, expectations of a stronger Ringgit and the pullback in the price of crude oil, which will keep inflation fears in check.

Note the following comments...


Rumours and speculation of mergers and acquisitions (including privatisations) also appear to profligate lately, which would obviously be good for the market, especially if there is actually fire behind some of the smoke.

Lots of fantastic rumours, isn't it? Or is plain speculation?

How ironic because OUR business news is one the MAJOR sauce of distribution!!!

As an investor, would you be willing to invest in a market dominated by rumours and speculations?


But for some strange reason, these positives are not being translated into a bullish sentiment on the local bourse. On the contrary, investor sentiment appears relatively muted, at best, particularly among the retail investors (as evidenced by the relatively low daily trading volumes and the almost evenly balanced number of gainers and losers each day).


Yes... big issue isn't it?

Why isn't ppl interested in the market despite the market being at its six years high?

Oh, perhaps this six years high is a lousy indicator? What say you?

And here's more interesting comments...


Spending on consumer durables and big ticket items such as purchase of passenger cars and real estate are down year-to-date and consumer sentiment is further affected by talks of further increases in prices of basic items such as toll rates, petrol prices and food prices.

Here's the thing... if the market is so hot (at its six years high mah), why isn't the consumer spending????

I don't know... what say you?

Care to share some opinions?

Read more...

When BAD is GOOD!! (Doh!)

Thursday, October 5, 2006

Read today's FSO by Martin Goldberg. Rather interesting point. ( here )


Although the Dow is hitting all time highs in nominal dollar terms, not all of the 30 Dow stocks are in bull markets. The bull market is largely being led by the financial stocks within the 30 Dow Stocks. Some key Dow stocks are in long term technical peril in spite of a rally in the index to all time highs. Some, such as Alcoa are also in short term technical peril.

I guess you could relate that issue to those here in our Bursa, right?

Anyway, there was an interesting link in his write-up.

http://www.financialsense.com/fsu/editorials/shepherd/05/0415.html


Going into August 2004 the market was down heavily in particularly the NASDAQ which was looking at a 10% loss. This is not good just before an election, Presidents are not re-elected when the markets are falling. Everything was looking very bearish it looked like the Iraq war rally had run out of steam at exactly the wrong time for the election. We wrote about this publicly in March 2004

how?

Look at Goldberg's comments on Today's market near the end of his write-up.


Tomorrow’s jobs number will have an impact upon the bond market. With regard to the market, a “good” number will probably be a bad number. Today a couple of Fed representatives chirped about inflation and the potential for higher interest rates


SEE HOW THE BAD NUMBER IS NEEDED as more fuel to this GREAT BULL RUN?

:s54: :s54: :s54:

Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP