- MaxWealth88 said...
appreciate your comment on Success Transformer.
I actually wrote on Success Transformer before, way back in 2006, Regarding Success Transformer
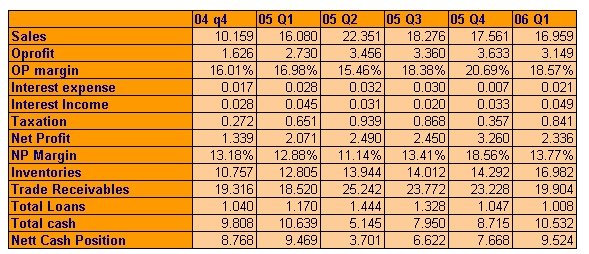
So how have Success Transformer done since then?
 2009* includes the earnings announced from Success Transformer last week.
Now what do you see from the compiled table? Me? As randomly mentioned before, Success Transformer has been doing remarkably well since its listing. The earnings growth is certainly commendable.
Of course some might prefer a better balance sheet.
The receivables does not appear to be an issue at all for now, in my flawed opinion.
Point to note, from the table, fy 2007 showed the tremendous jump in earnings growth. If one is a long term investor, understanding why would be useful.
Feb 2008: Quarterly rpt on consolidated results for the financial period ended 31/12/2007
From its notes:
- The Group recorded revenue of approximately RM 44.2 million and RM 146.1 million espectively for the current quarter and financial year ended 31 December 2007 under review as compared to RM 21.5 million and RM 81.0 million in the previous corresponding quarter and financial year ended 31 December 2006, a strong increase of approximately 105.9% and 80.4% respectively. This substantial increase was mainly due to higher sales volume from both local and export sales with Seremban Engineering Sdn Bhd (SESB) contributes approximately RM 17.0 million and RM 50.0 million respectively.
Profit after tax (PAT) improved to approximately RM 5.4 million and RM 17.9 million for the current quarter and financial year ended 31 December 2007, increased by approximately 47.4% and 48.4% respectively as compared to previous corresponding quarter and financial year ended 31 December 2006 of RM 3.7 million and RM 12.1 million. This was achieved on the back of higher sales volume from transformer and industrial lighting segment coupled with SESB’s profits contribution of approximately RM 1.2 million and RM 3.7 million respectively.
Some news clip. ( Sorry cannot provide links - the links are outdated!)
- Wednesday April 2, 2008
Success to buy remaining stake in SESB
PETALING JAYA: Success Transformer Corp Bhd, which owns a 60% stake in Seremban Engineering Sdn Bhd (SESB), has proposed to acquire the remaining 40% of the latter.
The company will acquire the 40% stake for RM21.78mil cash from its vendors, Wong Choon Cheong, Tan Tian Seng, Wong Poh Chee and Wong Chee Kian.
The vendors would guarantee that SESB earn a profit after tax of RM7.5mil and RM9.0 mil for the years ending Dec 31, 2008 and 2009 respectively, Success said in a statement yesterday.
The manufacturer of low-voltage transformers and electrical lighting products completed its initial acquisition of 60% of SESB in March last year, two years after its listing on the Bursa Malaysia second board. It has since transferred to the main board.
The acquisition of SESB, a manufacturer of process equipment such as pressure vessels and heat exchanges, had been a good experience, managing director Tan Ah Ping said in the statement.
“We are glad the entire 100% of SESB is now under our umbrella. It is almost a year since our first acquisition of a 60% share in SESB.
“During the period, we were impressed with the aggressive expansion plans and long term profitability of SESB as well as the full commitment of the vendors and their management,” he said.
In view of the long-term prospects in the palm oil and oil and gas sectors, Success decided to acquire the remaining 40% stake, which would also enable it to fully consolidate SESB's earnings.
It was agreed that the vendors would continue in their management roles in SESB to spearhead its growth for a period of no less than 10 years after the acquisition.
“With the continued support from this high calibre management team, we are confident that SESB will elevate to the next level of success,” Tan said.
As a 60%-owned subsidiary for 10 months last year, SESB contributed revenue of RM50mil and a net profit of RM3.7mil to Success' group earnings.
SESB's products are used in the palm oil, oleochemical and oil and gas industries in Vietnam, Indonesia, Singapore, China, Japan and the Netherlands.
The company secured an initial contract from a Singapore company last week, marking its entry into the waste management industry.
SESB had earlier acquired 2.6 acres in Senawang, Negri Sembilan for a new production facility to complement its existing four factories.
The new factory will increase SESB's total capacity by about 20% to cater to its rising order book from the process equipment sector.
22nd May 2008, on Star Business, Success Transformer net profit up 63% in Q1
26th May 2009.
- Tuesday May 26, 2009
Success expands in economic downturn
By YEOW POOI LING
Firm’s sixth factory to begin contributing in second half
PETALING JAYA: Success Transformer Corp Bhd’s process equipment subsidiary, Seremban Engineering Sdn Bhd (SESB) is constructing its sixth factory at a time when the country’s manufacturing sector is still grappling with the slowdown.
According to a company official, SESB’s fifth factory was ready late last year and has started contributing positively to the group this year.
The setting of the sixth factory is currently underway and expected to be completed in July.
“The sixth factory is likely to start contributing to the group in the second half of this year,” he told StarBiz in a phone interview.
SESB also added capacity last year when it subscribed to a 60% stake in Sepen Engineering Sdn Bhd, which manufactures process equipment. The group’s process equipment is mainly for the food industry where demand has not contracted.
The official said SESB’s first four factories are currently running at 80% capacity while the fifth plant is running at 30% to 40%. Its projects in hand are worth some RM39mil.
Success first bought 60% of SESB in March 2007 and upped the stake to 100% a year later as the acquisition proved to be profitable.
The acquisition has worked well as SESB had three plants at that time, and under Success, it will grow to six.
Yesterday, Success reported its results for the first quarter ended March 31, 2009. Net profit rose almost 19% to RM6.1mil compared with RM5.1mil in the preceding year.
Revenue increased to RM45.5mil from RM42.6mil previously. Earnings per share improved to 5.08 sen against 4.25 sen previously.
In the filing with Bursa Malaysia, it attributed the improvement to increase in sales from process equipment segment and an additional contribution from SESB after the acquisition of the remaining 40% stake in SESB.
Net profit in the first three months was also higher than the fourth quarter thanks to an increase in sales from the process equipment division, savings in production cost, operating expenses and improved production efficiency.
The group’s transformer and industrial lighting division produced an operating profit of RM5.2mil, down from RM5.8mil in the first quarter last year, while SESB contributed RM3.1mil, up from RM2.1mil in the corresponding quarter last year.
Despite the challenging global economic environment, the company’s strategies would continue to be leveraging on its extensive customer network, competitive products, quality services and wider range of products.
The group was optimistic to achieve comparable results in the present financial year from the previous year, it added
7th Oct 2009
- STC unit to offer 19.9m shares in IPO
Written by Financial Daily
Wednesday, 07 October 2009 10:37
KUALA LUMPUR: Success Transformer Corporation Bhd’s (STC) subsidiary Seremban Engineering Bhd (SEB) will undertake a public issue of 19.93 million new shares, representing 24.91% of its enlarged paid-up capital pursuant to its proposed listing on the Main Market.
In a statement yesterday, STC said it had submitted the applications to the relevant authorities to seek their approvals for the proposed flotation exercise involving an enlarged paid-up capital of RM40 million comprising 80 million shares of 50 sen each.
It said of the IPO shares, a total of 9.93 million, or 12.41% of the enlarged paid-up capital, would be reserved for bumiputera investors approved by the Ministry of International Trade and Industry by way of private placement.
SEB group’s eligible directors and employees, and persons who have contributed to the success of the group will be offered 3.5 million shares, while another 6.5 million shares will be offered to the public. STC said the issue price would be determined later after getting the approvals from the relevant authorities for the proposed listing.
Simultaneous with the proposed public issue, STC itself will make a restricted offer for sale of 8.07 million shares, representing 10.09% of SEB’s enlarged paid-up capital.
Of these, eight million shares will be reserved for STC shareholders on the basis of one SEB share for every 15 shares of 50 sen each held in STC, while 72,000 shares will be reserved for bumiputera investors approved by the ministry.
Prior to the IPO, SEB proposed a bonus issue of 58.07 million shares of 50 sen each on the basis of about 2,904 bonus shares for every 100 existing shares.
STC said the proceeds from the public issue would be used for the purchase of property, plant and equipment, for repayment of borrowings, as working capital and to defray expenses. It expects the listing exercise to be completed by the first quarter of next year.
RHB Investment Bank has been appointed as the principal adviser, managing underwriter and placement agent for the proposed flotation.
SEB group is involved in the fabrication of process equipment such as unfired pressure vessels, non-pressurised tanks and heat exchangers; metal structures such as plant fabrication and installation, steel structures, piping and ducting systems and other products and services; and the provision of maintenance and shutdown services.
For the six months to June 30, 2009, SEB group posted an unaudited net profit of RM4.52 million on the back of revenue totalling RM36 million. It posted an audited net profit of RM7.88 million and revenue of RM62 million in FY08.
This article appeared in The Edge Financial Daily, October 7, 2009.
And that's about it. So how?
Success Transformer, had indeed done fantastic since listing but one needs to point out that the last three fiscal year, Success Transformer's earnings has gone up another level, thanks to its subsidiary, SEB.
Now Success wants to list SEB. As a shareholder of Success, as mentioned on the Edge Financial Daily, "eight million shares will be reserved for STC shareholders on the basis of one SEB share for every 15 shares of 50 sen each held in STC".
Now obviously, the norm speculation is the stock should perform well since Success Transformer shareholders will be gaining some 'bonus' share - in the form of one SEB for every 15 shares held in Success. Naturally the hope is, once Success is listed, both Success and SEB could trade higher. That's the hope, that's the objective.
Will it work?
I do not know. Market is not mine. I have no idea what the market will or will not do. Sorry.
But if this is the sole reasoning you are buying this stock, perhaps you could be extremely hardworking by digging out information on recent listing of subsidiaries in the market. Did such a strategy work out?
Read more...