Powered by Blogger.

Home

Showing posts with label Top Glove. Show all posts

Brief Review Of Top Glove Earnings

Wednesday, March 16, 2011

Top Glove announced its earnings last night.

Now Top Glove earnings track record had been incredible. Here's a snapshot from their recent annual report.


With such impressive track record, the stock market and its investors simply loved the stock for it simply rewarded its investors handsomely.

However, growth is not forever, especially not for extreme high growth.

The industry was growing at rapid pace and with such rapid pace, huge capex was required. Last year the following were posted.

  1. 25 June 2010, Would You Be Concerned With All The Capex In The Rubber Glove Industry
  2. 16 Sep 2010. Bargain Hunting For Rubber Glove Stocks?

I raised the simple question:

  • But in regards to the glove sector, perhaps one should consider if the fundamental reasonings is unjust?

    Remember if the reasoning is indeed justifiable, ie, strong USD would see lower revenue and higher latex prices would mean higher costs and overcapacity could lead to price wars, then won't it be possible that future earnings could be much 'lower'?

    How?

And we did see some lower earnings.

From Top Glove's earnings report last night:


Look at the two numbers highlighted by the arrows. (All images can be clicked for a larger view)

Perhaps that's a bit not so clear.

How about this set of summarised data?


As can be seen clearly, since Top Glove's 10 Q2, earnings had been declining quite drastically and if one needs to keep count, that's FOUR consecutive quarters of decline.

And if one is an investor, perhaps one should check out the financial health. Compare the cash/debt balances. Are they improving or are they declining? ( LOL! Sorry babe, I am too lazy to do everything in one single post and more so I am not the financial advisor!)

However, shareholders of the company would be quick to point out that Top Glove had been a rather extremely good dividend stock! (aha.. how many knew this fact?)

From Top Glove's earnings notes..


That's impressive, yes?

Now I do not have the complete comparison data, so I dare not claim Top Glove is the best dividend stock but I have to admit that I am simply impress by Top Glove's track record of paying more dividends each year back to its shareholders, as seen by the data above. (I normally view the total monetary value paid by the company and not based on dividend yield. Why not dividend yield? Well the dividend yield equation is based on the price one invests on a stock and this price is not equal for everyone. Some might buy at 2.00, some might buy at 3, so the dividend yield is out of whack for me.)

Now why is the financial balance sheet an important issue? Well remember the posting highlighting the rubber gloves industry intense capex? Well if cash is getting lower, then this would put a huge strain on Top Glove's ability to pay more dividends this year. Ah, some layman would use the common sense thinking and say if earnings is falling then naturally the dividends would fall too. Heck it's a no brainer!

So how?

Me? I still think the few issues that are important for Top Glove is the USD factor, the price of latex and the industry over capacity issue.

And if one is still an investor, one needs to give these factors a serious consideration.


Read more...

Would You Be Concerned With All The Capex In The Rubber Glove Industry

Thursday, June 24, 2010

It makes you wonder about all these capex plans made by out rubber glove makers.

Now do not get me wrong. There's nothing wrong with expansion plans. In fact, it's good to see factories making expansion plans, for it indicates that demand is great.

However, there is a danger.

Demand is not everlasting. It's not forever and ever.

And needless to say, even if demand does not falter, oversupply can occur. Yes, when everyone in an industry sees supply not able to meet demand, people get greedy. Surely, the logical thing to do is to expand production. One starts but they fail to realise that everyone too had jumped onto the bandwagon and starts making huge expansion plans. Next thing you know, the supply is everywhere!

Let's have a simple look.

In today's Business times.

  • TOP Glove Corp Bhd (7113), the world's largest rubber glove maker, plans to spend RM80 million until May next year to set up three new plants and increase production lines.

    Chairman Tan Sri Dr Lim Wee-Chai said the expansion will bring the number of its factories and production lines to 20 and 459 respectively, producing 41.2 billion pieces of rubber gloves a year.

A 80 million expansion plan.

20 factories and 459 production lines. Meaning 3 new factories would be built.

The article continues...

  • Top Glove currently has 17 factories, out of which 11 are in Malaysia, four in Thailand and two in China. They produce 33 billion pieces of rubber gloves a year, or some 33 per cent or more of the world rubber glove. Read more: here

A couple of days earlier, Kossan made the following announcement: Kossan in RM60m expansion

  • Kossan in RM60m expansion

    By Zaidi Isham Ismail Published: 2010/06/23

    RUBBER glove maker Kossan Rubber Industries Bhd (7153) will
    spend RM60 million in the next two years to expand its operations in Klang, Selangor.

    The plans include two new plants, increasing production lines, buying new machinery, upgrading existing equipment and boosting research and development....

    He said the first plant will be completed by October, while the other will be ready by next year, bringing Kossan's number of plants to 12, producing 14 billion pieces of gloves a year, or some 14 per cent share of the world's rubber glove market.

Kossan plans to spend 60 million.

15th April 2010: Update Selldown of glove makers overdone, says Supermax

  • Thai said Supermax expected a 40% rise in revenue to RM1.15 billion in FY10, based on current latex prices and bigger capacity with its new plant in Meru, Klang as well as the installation of new production lines

    It is allocating RM131 million in FY10 for the setting up of the factories. The Meru plant is expected to be commissioned by July while the first of six plants in Glove City in Bukit Kapar, Klang will be commissioned next year.

Supermax's expansion plan is rm 131 million!

1st April 2010: Hartalega plans RM120m capex

  • Hartalega plans RM120m capex

    By Chong Pooi Koon Published: 2010/04/01

    GLOVE maker Hartalega Holdings Bhd (5168) has allocated RM120 million in capital expenditure for the next two years, part of which will be spent on plant expansion and technology investment, its chief says.

    The company, which operates five factories, is in the midst of upgrading an existing plant while completing the fifth one. The new capacity will boost its annual production by three billion pieces of gloves by the end of next year when the plants are fully operational.

    It is producing 6.5 billion pieces a year now.

Hartalega is allocating 120 million!

Recently I made the following posting on Adventa: A Look At Adventa's Earnings

  • Capex (capital expenditure) guided by management is RM30 million per year which will be funded internally and via borrowings.

Adventa management is saying that capex is about 30 million per year.

Latexx Partners: You have to search their capital commitment statement in their earnings notes reported in May 2008. Quarterly rpt on consolidated results for the financial period ended 31/3/2010. It stands at 63.128 million but for plant and machinery, the amount is 52.5 million..

Let me grab and crank up my cow-cool-lator... not sure if it can handle all these numbers... and if my fat little fingers are not clumsy and retarded... the grand total is 473.5 million.

So how?

Isn't it a little bit incy wincy scared?


And what about other glove manufactures? What if they get the same idea? Expand! Expand! Expand!

How?

And if we take into consideration that perhaps a huge increase in the demand was caused by the H1N1 flu. Now obviously it is possible that this H1N1 flu might not last forever. What if the demand decreases along with the H1N1? Not possible?

Yes, isn't it possible that demand could one day subside? But then with all these expansions, we know that supply would increase dramatically.

Would you be concerned? A little bit?

Read more...

Top Gloves Tops Again!

Thursday, October 8, 2009

Flashback!

>>>>>>>>


In the posting:
iCapital Did Explain Why It Lost So Much Money In Axiata!


  • invest said...

    End of the day, one has to see both sides of the coin....You tend to only see one side...U can criticise but I have never seen you give credit when it is due....or mayb you think he does not deserve any credit....sigh
Everyone knew that I was not a fan of Top Glove. You can use this search.......

.................................

But in April 2009, I wrote this posting: A Quick Look At Top Glove Quarterly Earnings.

How?

Here's a screen shot.


How?

What was the price of Top Glove on that day?

Lucky for me, I posted Top Glove chart on that day. (this link is link to that chart.)

Top Glove on that day was 4.96.

Top Glove right now is how much?

*** warning.. warning.. I really have no idea if you can make or lose money buying TopGlove now. So if you make money, you owe me nothing. And if you lose money, you owe me none of your tears too! ***


>>>>>>>>>>>

Yesterday Top Glove announced its earnings. Here's one article. Top Glove 4Q09 net profit surges to RM56.8m

How much did Top Glove closed at yesterday?

8.15.

Yes, it was 4.96 the day I highlighted or as some insist, 'giving credit where credit is due'.

ps: I do not know how much higher TopGlove can go and neither is this posting a buy recommendation. But hey, if you insist, it's your right of opinion.

ps/ps: With the weakening of the USD against the RM (LOL! Do notice that I did not say the strengthening of the RM), do give this issue a good consideration.

ps/ps/ps: other postings on

Read more...

Do I Not Give Credit Where Credit Is Due

Monday, August 17, 2009

In the posting: iCapital Did Explain Why It Lost So Much Money In Axiata!


  • invest said...

    End of the day, one has to see both sides of the coin....You tend to only see one side...U can criticise but I have never seen you give credit when it is due....or mayb you think he does not deserve any credit....sigh
Everyone knew that I was not a fan of Top Glove. You can use this search.

Or here is the list of postings.


And I am sure those are enough evidence to show that I am not a fan.

But in April 2009, I wrote this posting: A Quick Look At Top Glove Quarterly Earnings.

How?

Here's a screen shot.


How?

What was the price of Top Glove on that day?

Lucky for me, I posted Top Glove chart on that day. (this link is link to that chart.)

Top Glove on that day was 4.96.

Top Glove right now is how much?

*** warning.. warning.. I really have no idea if you can make or lose money buying TopGlove now. So if you make money, you owe me nothing. And if you lose money, you owe me none of your tears too! ***

Read more...

A Quick Look At Top Glove Quarterly Earnings.

Tuesday, April 7, 2009

Posted January 2009: Top Glove Gets Top Recommendations!

Top Glove then was at 4.30 and yes, I was not a fan of Top Glove.

Top Glove announced its earnings tonight and I was impressed with what I saw.


Yes, I am impressed!

Yeah, you really have to give credit when credit is due ( and you do know that I do not give stock recommendations and if you stubbornly insist that this is a stock recommendation, well let's put it on the record that it was you, yourself insisted! )


Company's review of performance.


And here is how Top Glove is faring the past one year.

Read more...

Top Glove Gets Top Recommendations!

Tuesday, January 13, 2009

Published on Star Business: More upside for Top Glove

  • KUALA LUMPUR: HwangDBS Vickers Research sees more upside for Top Glove and is maintaining a buy call on the stock with a price target to RM4.70, based on 10 times price to earnings for 2009.

    “We like the stock for its visible earnings, good dividend track record and attractive valuation. Top Glove is currently trading at one-year forward PE of 8.9 times and price-to-book of 1.6 times, which are near its historic lows,” it said.

    However, the research house said its share price performance, however, could be muted in the short term by the recent rally (up 22% since the start of the year). ( read rest
    here )

The blue bold highlight says it all for me.

The stock is up a lot - yes a lot and you really need to consider the global market environment, yes?

Have a look. Here's where we are!


Aren't we at a rather lofty high position now?


And amazingly HwangDBS buy price target of rm4.70 is rather lowish!

Yes rather lowish! LOL!

Kid you not.

In today's research reports, I note that OSK has the price target at rm 5.05, CIMB has it at 5.40 and RHB tops it with 5.50.

How?

Would you like to go for the buy high, seeker higher investment strategy?

Me?

I do not rate Top Glove at all. Search for postings on my blog on Top Glove and you would understand why. :D

Read more...

Huh?

Tuesday, August 5, 2008

Yesterday I saw an announcement posted on Bursa Website: TOP GLOVE CORPORATION BERHAD (“the Company” or “Top Glove”) - Article entitled : Top Glove issues profit warning

  • We refer to the article entitled “Top Glove issue profit warning” appearing in The Edge Financial Daily on Monday, 4 August 2008, page 1 and 4 and with reference to our reply to Bursa Malaysia Securities Berhad on 25 September 2007.

    The Company would like to clarify that the Company has not issued any Profit Warning Statement. The headline of the article published by The Edge was merely its own interpretation from the interview carried out on 29 July 2008.

    The Company is able to achieve a higher turnover in FY08 compared with last year, but lower than targeted turnover due to the weakening of US Dollar by around 8%.

    The targeted profit of FY08 was affected by the unexpected surge in raw material prices and the inflationary effect. In particular, the oil price which has gone up by around 65% and the latex price increased by around 45% compared with last year. Also, the recent revision in gas price of around 72% by the government also affected the profitability.

    However, the Company as always will endeavour to achieve better results than last year, with the commitment of the management team and with the continuous improvement of our glove quality and cost efficiency

The following is the link to the said article on The Financial Edge on Monday, 04-08-2008: Top Glove issues profit warning

  • 04-08-2008: Top Glove issues profit warning

    KLANG: Top Glove Corporation Bhd, the world’s largest rubber glove maker, does not expect to meet its target of RM125 million net profit for its financial year ending Aug 31, 2008 (FY08), said executive director Lim Cheong Guan.

    For the nine months to May 31, 2008, the company’s net profit rose 11.6% to RM84.96 million from RM76.12 million a year earlier. Annualised, the profit for FY08 would be about RM113 million.

    “It is very difficult for us to get RM40 million net profit in one quarter, especially when the US dollar is weakening and (with the) several cautious steps we have taken amid the concerns on the uncertain market situation.

    “However, we will try our best,” Lim told The Edge Financial Daily in a recent interview. The company posted a 12-year-high net profit of RM103 million in FY07.

    Nevertheless, the company is targeting to pay a total dividend of 22%, or 11 sen per share, in FY08 against 20% or 10 sen per share in FY07. As of May, it had declared an interim dividend of 10%, or five sen per share.

    Similarly, Lim said the company is most likely to fall short of its targeted RM1.55 billion in sales revenue, expecting instead to reach RM1.4 billion. However, he believed that its performance in FY08 would still be better than that in FY07.

    Top Glove’s cumulative sales revenue for the nine months breached RM1 billion in FY08 compared with RM921.22 million a year earlier. It posted a record revenue of RM1.23 billion in FY07. The company controls 25% of the global rubber glove market.

    Analysts’ consensus forecast has Top Glove’s net profit at RM114.55 million for FY08. An analyst with a local bank expects Top Glove’s FY08 net profit to reach only RM112 million. “There is only one quarter left and I don’t think Top Glove can make RM40 million in this short period. Furthermore, its profit margin is under pressure following the higher raw material prices and weakening currency,” he said.

    “There is a possibility of the market slowing down, and it might have a slight impact on Top Glove. However, the company’s operations in China are doing well and have received high demand. It would contribute to their bottom line.”

    On the industry outlook, the analyst said he was concerned that demand would slow down. He believed that glove makers would be cautious of any capacity expansion and investment.

    In line with the uncertain market, Top Glove has reduced its capacity utilisation to 80% from more than 90% previously. However, Lim said the reduced capacity utilisation had not affected sales growth.

    “We are not as aggressive as last time. We are cautious about the market situation and have slowed down our production rate. Some factories are not fully operated,” Lim said. Top Glove has an annual production capacity of 30 billion pieces of gloves.

    “We are an original equipment manufacturer, and we produce gloves based on customers’ requirements. It is unlikely for us to see reduced demand, as gloves are a necessity in some industries,” Lim said.

    Top Glove exports its products to 180 countries, with the United States and Europe each contributing 30% to its revenue. Asia makes up 12%.

    “We see more business potential in Asia, especially India and China,” Lim said. About 80% of its gloves are sold to the medical industry.

    With some minor glove makers expected to cease operations during this difficult period, Lim sees it as an opportunity for Top Glove to get more business.

    In mitigating the escalating raw material prices, Top Glove has increased glove prices since May. Latex powdered gloves, which make up 52% of its total revenue, are currently sold at US$27 per 1,000 pieces, up from US$23 per 1,000 pieces in May.

    “We pass 100% of the cost of natural gas, electricity, fuel and chemicals to customers. For latex, we absorb 20% of the cost and pass the other 80% to the customers,” Lim said.

    He was confident that raising prices to retain profit margin would not dent its competitiveness against rivals in Thailand and Indonesia.

    “The cost of making gloves in Thailand and Indonesia is much higher than in Malaysia. For example, the natural gas price in Thailand is RM38 per mmBtu (million metric British thermal unit). Our gap (of cost) was reduced only after inflation, but their cost is still higher than us,” he added.

    Lim also dismissed suggestions that using biomass as fuel could be expensive, as manufacturers had to maintain boilers and also provide storage for biomass materials.

    “Before the increase in natural gas prices, the production cost of using either biomass or natural gas was similar. However, the government has raised the price of natural gas by 71% to RM22.06 per mmBtu from Aug 1.

    “After deducting the cost of storing biomass materials and maintaining the boilers, we could still save up to 70% compared to using natural gas,” Lim said, adding that Top Glove was using palm kernel shells, empty fruit bunches and wood chips to feed its boilers.

    The government had on June 4 announced that it would increase the selling price of natural gas by as much as 187% to RM32.56 mmBtu by July 1. However, it has deferred the full implementation and the price hike would be gradual over the next 10 years until they are on par with global prices.

    Lim noted that the cost of building a biomass-powered boiler is RM5 million more than the cost of installing natural gas piping. “The construction cost for a biomass-powered boiler is more expensive but we can save on the operating cost in the long run,” he said.

    With the costlier natural gas, the company estimated that fuel would constitute about 11% of its overall production cost compared with 8% previously.

    However, Lim said the cost would be reduced by 1% to 2% upon the completion of two factories which would use biomass. The factories would be completed in August and October, respectively. At present, Top Glove has four factories with biomass-powered boilers — two in Malaysia and two in Thailand.

    Moving forward, the company would spend 1% of its revenue annually on research and development (R&D) in technology, which could save another 10% to 20% in cost.

    Asked if Top Glove would expand its upstream businesses, Lim said: “We are actually exploring a joint-venture opportunity with the government or third party to lease rubber estate. However, nothing is concrete yet.”

    “We are not in a hurry to buy rubber estate as we have two latex concentrate plants in Thailand to process raw latex. Rubber estate is very costly now,” he added.

    The two factories in Thailand have a total capacity of 70,000 tonnes per annum, supplying 60% to 70% of Top Glove’s latex needs.

Today, the financial Edge decides to do a follow up, 05-08-2008: Top Glove to achieve higher turnover

  • PETALING JAYA: Malaysia’s leading glove manufacturer Top Glove Corp Bhd said the company would be able to achieve a higher turnover in the current year ending Aug 31 but it would be lower than the targeted turnover due to the weakening of the US dollar.

    The company said the targeted profit of FY08 was affected by the unexpected surge in raw material prices and the inflationary effect.

    “In particular, the oil price which has gone up by around 65% and the latex price increased by around 45% compared with last year. The recent revision in gas price of around 72% by the government also affected profitability,” said Top Glove.

    It said it would always endeavour to achieve better results than last year, with the commitment of the management team and with the continuous improvement of its glove quality and cost efficiency.

    Top Glove clarified that it had not issued any profit warning.

    The counter slipped 6 sen to RM3.96 at the close of yesterday’s trade.

Hmm.. I was thinking of what Avatar had commented.

Avatar said...

  • On the other hand, when the news in the financial dailies are way off the mark, there are no retractions, no comments...

    This just gives many people the *wrong* perception that there are very little or no errors in the news published in the financial dailies.

Huh?

Read more...

Financial News: True Or False?

Monday, August 4, 2008

Consider the following scenario.

Auntie May buys a weekly financial business news. She reads the news.
Unfortunately what she reads might not be true.

Some are based on rumours and speculation from sources who are NEVER named despite their constant, blatant inaccuracy.

And then sometimes the financial news are mere interpretations which are staunchly denied by the companies involved.


Which means Auntie May would never know what she reads is true or not unless she surfs diligently the Bursa Malaysia website!

Yes, Auntie May would need to seek confirmation from the Bursa website to confirm what she reads is true or false!

For example, in today's announcements posted on Bursa website, several announcements caught my attention. Yes, SEVERAL!

1.
TOP GLOVE CORPORATION BERHAD (“the Company” or “Top Glove”) - Article entitled : Top Glove issues profit warning

  • We refer to the article entitled “Top Glove issue profit warning” appearing in The Edge Financial Daily on Monday, 4 August 2008, page 1 and 4 and with reference to our reply to Bursa Malaysia Securities Berhad on 25 September 2007.

    The Company would like to clarify that the Company has not issued any Profit Warning Statement. The headline of the article published by The Edge was merely its own interpretation from the interview carried out on 29 July 2008.

    The Company is able to achieve a higher turnover in FY08 compared with last year, but lower than targeted turnover due to the weakening of US Dollar by around 8%.

    The targeted profit of FY08 was affected by the unexpected surge in raw material prices and the inflationary effect. In particular, the oil price which has gone up by around 65% and the latex price increased by around 45% compared with last year. Also, the recent revision in gas price of around 72% by the government also affected the profitability.

    However, the Company as always will endeavour to achieve better results than last year, with the commitment of the management team and with the continuous improvement of our glove quality and cost efficiency
2. HAP SENG CONSOLIDATED BERHAD Article entitled “Is C&C Bintang making an exit?”


  • Pursuant to paragraphs 9.09 and 9.10 of the Listing Requirements of Bursa Malaysia Securities Berhad, the Company, after having made due inquiry on the above, wishes to confirm that the Company has never made any representation to such effect and hereby deny information contained in the Extracted C&C Report

3. ARTICLE ENTITLED: “IS C&C BINTANG MAKING AN EXIT?” IN THE EDGE FOR THE WEEK OF AUGUST 4 – AUGUST 10 2008

  • We refer to the above article in The Edge and wish to clarify that the story about the Company exiting the Mercedes-Benz business is unfounded and untrue. This matter was never considered by the Board.

    We wish to draw your attention to the announcement of the Group’s first half results for 2008 on 30th July 2008 wherein the Chairman highlighted that having completed the restructuring of its operations, the Company is now able to concentrate on its Mercedes-Benz retail business and is better positioned to meet the challenges ahead.

    We trust the above clarifies the matter.

Three announcements denying what was written by the so-called financial reporters. (ok, Hap Seng is co-related to Cycle & Carriage)

Isn't incredible?

Read more...

Regarding Top Glove share buybacks.

Monday, January 14, 2008

The Smart Investors wrote:

  • What do you think of Topglove's share buy back scheme. Seems every few days they buy back their shares. But doesnt seem to be affecting share price. As a company i really like Topglove and have taken their share buy back as a positive signal. Juz wondering what your thoughts on it might be.

Dear Smart Investor.

Here are some of my thoughts on this issue. (Do realise I am not a legal investment advisor, so do take my comments with a pinch of 'garam'. )

1. Regarding TopGlove share buyback.

In my opinion, I'm not too impressed with their share buyback program. I could be wrong but I do not see much point in initiating a share buyback based on the current prices for I do not see much value in doing so and I would certainly question why the need for it. Perhaps money could be utilised much better.

For starters, Top Glove's cash flow is weak and if you look at their recent announced quarterly earnings, you would see that their cash balances is much weaker if you compared to the previous year.

And amidst their rather insane everlasting global capital expansion (yes, I am not a fan of their continuous expansion over all these years.) Top Glove is a company which is in a nett debt position. And when you have more debts than cash, I am simply not in favour of such a corporate exercise.

2. Buybacks not affecting the share price.

Not all buybacks works. Some fail. Do read Dali's truly brilliant article on Why buybacks fail.

Hence, I ask you in return. Are you really expecting the share price to increase?

3. Regarding Top Glove.

I have posted before quite a number of postings on Top Glove ( See this posting: Top Of Ze World: VIII. It include links to other Top Glove postings) and I am sorry but I am not a fan of this company and I do see some valid reasons to be sceptical. For example, I seriously believe Top Glove has over-expanded and I am sceptical if the company can truly manage their expansions in a profitable manner. And then you have the rising costs issue. Rising fuel and high rubber prices simply means higher cost. And last but not least, I could be wrong but Top Glove's sales are predominantly in the US Dollar. And a shrinking US Dollar will have a huge impact on Top Glove profitability.

Hope my thoughts help as a second opinion.

rgds

Read more...

Top Glove

Thursday, July 5, 2007

I was looking through some of the comments posted by some research houses.

1. RHB: Following the earnings downgrade, our indicative fair value has been trimmed to rm9.56, based on unchanged 20x CY08 EPS. Maintain Outperform. ( CY08 estimated earnings is 134 million)

2. Alliance: Maintain BUY with a Target Price of RM10.30, based on PER21X EPS FY8/08 of 49sen. (FY08 estimated earnings is 147.1 million)

3. SJ Securities: We have fairly valued the Group at RM9.40 based on a forward PER of 17x. (Estimated earnings is 137 million)

4. OSK: Maintain BUY. Fair value remain unchanged at RM10.10 by using the composite PE of 21x over FY08 EPS of 46 sen and 4.4x P/B over FY08 BV/share of RM2.37. (Estimated FY08 earnings is 142.1 million).

I find the earnings estimates overly optimistic.

As it is, current fiscal year 2007 (3 quarters) earnings for Top Glove is around 76.115 million and current twelve month earnings is around 94.656 million. So one is perhaps looking at around 95-100 million in earnings for Top Glove for its fiscal 2007. However, look at the above estimates. Most of the research houses is estimating that the next fiscal year Top Glove would earn around 134 to 147 million! If assuming Top Glove does achieve 100 million in earnings for its fiscal year 2007, they are expecting Top Glove earnings to grow between 34% to 47% for its fy 2008.

Isn't this too optmistic?

Read more...

Top Glove fined

Friday, August 25, 2006

Well the fine was expected when the law was broken.

Top fine for Top Glove Corp

  • PUTRAJAYA: A whopping RM11.4mil fine! That is the amount that Top Glove Corp Bhd, which was caught with 1,769 illegal workers on Aug 16, will have to pay.

    It is the largest fine ever imposed on an employer for hiring illegal workers in the country’s history.

    Immigration enforcement chief Datuk Ishak Mohamed said the Klang-based glove-making company has also been asked to pay RM2.3mil in outstanding levies for the illegal immigrants they hired.

    Ishak said the previous record fine of RM500,000 was imposed by the Johor Immigration Department on a construction firm for a similar offence in 2000.

    On Aug 16, Ishak led a raid on the factory which was found to have hired more than 1,000 illegal foreign workers who were either working without permits or with expired permits.

    However, the department did not detain any of the illegal workers to ensure that the company, which is public-listed, could fulfil its overseas orders.

    “I urge the public to continue to help the authorities identify unscrupulous employers. In the case of the rubber glove manufacturer, we were successful because we were tipped off,” he added.

    Top Glove executive director K.M. Lee said last night the company would appeal on Monday for a reduced fine.

    “There are a few mitigating factors. Firstly, the workers came in with proper papers. “Not a single one of them came in without a passport,” he said.

    Secondly, it was an administrative failure on the part of the company and it was not intentional. Thirdly, when the company discovered the problem last month, it took steps to renew their papers, he said.
It would be nice to see the law be enforced and that Top Glove's appeal be rejected. The bottom-line is they broke the law and if the authorities are not strict on such issues, how do we expect a better future?

Think about this...

Laws would be totally useless if they can be broken and easily appealed.

Read more...

Top Of Ze World: VIII

Wednesday, August 16, 2006

From AP News:

KUALA LUMPUR (AP)--The world's largest rubber glove manufacturer faces fines of up to MYR121.2 million ($33 million) for employing more than 2,000 illegal foreign workers, a company official and news reports said Wednesday.

However, Malaysia's Top Glove Corp. said it expects to be spared from paying the maximum penalty.

Immigration officers raided a factory in Klang town, west of Kuala Lumpur, based on a tip-off and found that work permits for 2,071 of its foreign workers had expired, Immigration Enforcement Director Ishak Mohamad was quoted as saying by the New Straits Times newspaper.

Another 353 workers had no permits at all and 72 were without passports, he said. However, they were not arrested so the factory's production would not be disrupted, the newspaper said.

"The managers gave the excuse that they forgot (to renew the permits) or there were too many of them, but we don't buy that," Ishak was quoted as saying.

The Star newspaper quoted Ishak as saying it was "the first time the department has come across a case involving such a huge number of illegal workers in a single premises."

Under immigration laws, an employer can be fined up to MYR50,000 for each illegal worker.

Ishak and other immigration officers could not immediately be reached for comment.

Top Glove is the world's largest producer of rubber gloves for medical, household and industrial use.

Media reports did not identify the company, but Top Glove officials acknowledged it was their factory.

"It is an oversight on our part but we are giving our full cooperation to resolve this and to ensure it will not recur in the future," company executive director K.M. Lee told The Associated Press.

He said the fine was expected to have only a "minimal effect" on company earnings, noting that courts usually only impose maximum fines on employers who hire illegal migrants who enter the country without documents.

Lee said the company had been careless because of its rapid expansion in recent years but steps have been taken to strengthen internal monitoring. Most of the foreign workers caught were Indians, with some from Vietnam and Indonesia, he said.

Top Glove has 8,000 workers in eight factories in Malaysia, of whom 3,600 are foreigners, Lee added. The company also has two factories in Thailand and two in China.

Top Glove shares were down 3.3% at midday Wednesday at MYR8.70.

Top Glove closed at 8.65.


Questions/Issues.


1. Besides the issue of fines, assuming that the fines impact would be minimal, it now appears that Top Glove had been keeping its production cost low by engaging in such unlawful practise such as hiring illegals. So what's next?

Top Glove can't have this luxury no more. Right?

Which means its production cost will increase since they have to hire 'legals'.

Which means its bottom-line will be HIT in the future in regardless of the size of the fine.

2. Integrity issue!

This will stick out like a sore thumb!

How?

If proven guilty, it means that Top Glove is willing to engage in such unlawful activities to boost its bottom-line.

So how much can an investor trust this company?

3. How do you rate the management handling of this crisis?

The initial excuse of forgetting to renew the permits was as lame as it could get.


How?

past blog postings:


Top Glove..
Top Glove: Part II
Top Glove: Part III
Top Glove: Part IV
Top Glove: Part V
Top Glove: Part VI
Top Glove: Part VII

Read more...

Top of Ze World: Part VII

Tuesday, July 4, 2006

Here's an update to Top of Ze World: Part VI

Wrote the following back in April:

  • Let me bore everyone with numbers and more numbers for Top Glove.

    1. FY 2001.
    Shareholders Equity = 93.170 million. Total loans = 13.958 million.
    Total capital used = 107.128 million.
    Earnings generated = 17.217 million.
    Return of total capital used for 2001 = 17.217/107.128 = 16.1%

    2. FY 2002.
    Shareholders Equity = 109.136 million. Total loans = 13.440 million.
    Total capital used = 122.576 million.
    Earnings generated = 18.036 million.
    Return of total capital used for 2001 = 18.036/122.576 = 14.7%

    3. FY 2003.
    Shareholders Equity = 130.471 million. Total loans = 39.289 million.
    Total capital used = 169.760 million
    Current earnings generated = 25.222 million
    Return of total capital used for ttm = 25.222/169.760 = 14.9%.

    4.. FY 2004.
    Shareholders Equity = 162.006 million. Total loans = 63.063 million.
    Total capital used = 225.069 million.
    Earnings generated = 39.509 million.
    Return of total capital used for 2001 = 39.509/225.069 = 17.6%

    5. FY2005.
    Shareholders Equity = 216.082 million. Total loans = 154.191 million.
    Total capital used = 370.993 million
    Current earnings generated = 58.141 million
    Return of total capital used for ttm = 58.141/370.993 = 15.7%.

    6. TTM (Trailing Twelve Months or most recent 4 quarters).
    Shareholders Equity = 255.538 million. Total loans = 199.478 million.
    Total capital used = 455.016 million
    Current earnings generated = 69.666 million
    Return of total capital used for ttm = 69.666/455.016 = 15.3%.

After today's earnings report from Top Glove, here are the following numbers for Top Glove:

TTM (Trailing Twelve Months or most recent 4 quarters).
Shareholders Equity = 271.624 million. Total loans =
231.937 million.
Total capital used = 503.561 million
Current earnings generated = 76.103 million
Return of total capital used for ttm = 76.103/503.561 = 15.1%.

how?

Read more...

Top of Ze World: Part VI

Thursday, April 6, 2006

Edited: April 7th. 7.20 pm

Let me bore everyone with numbers and more numbers for Top Glove.

1. FY 2001.
Shareholders Equity = 93.170 million. Total loans = 13.958 million.
Total capital used = 107.128 million.
Earnings generated = 17.217 million.
Return of total capital used for 2001 = 17.217/107.128 = 16.1%

2. FY 2002.
Shareholders Equity = 109.136 million. Total loans = 13.440 million.
Total capital used = 122.576 million.
Earnings generated = 18.036 million.
Return of total capital used for 2001 = 18.036/122.576 = 14.7%

3. FY 2003.
Shareholders Equity = 130.471 million. Total loans = 39.289 million.
Total capital used = 169.760 million
Current earnings generated = 25.222 million
Return of total capital used for ttm = 25.222/169.760 = 14.9%.

4.. FY 2004.
Shareholders Equity = 162.006 million. Total loans = 63.063 million.
Total capital used = 225.069 million.
Earnings generated = 39.509 million.
Return of total capital used for 2001 = 39.509/225.069 = 17.6%

5. FY2005.
Shareholders Equity = 216.082 million. Total loans = 154.191 million.
Total capital used = 370.993 million
Current earnings generated = 58.141 million
Return of total capital used for ttm = 58.141/370.993 = 15.7%.

6. TTM (Trailing Twelve Months or most recent 4 quarters).
Shareholders Equity = 255.538 million. Total loans = 199.478 million.
Total capital used = 455.016 million
Current earnings generated = 69.666 million
Return of total capital used for ttm = 69.666/455.016 = 15.3%.

How?

How would you want to evaluate such numbers?

On one side of the coin, a ROTC of 15.3% is still pretty impressive despite the huge debts being employed to fun the expansion. And because the ROTC is 15.3%, surely this simply vindicates that all the spending, the negative cash flow and all the borrowings is justifiable.

But.... butt.... buttt....

On the other side of the coin, one could argue that since hitting the peak in FY 2004, with a ROTC of 17.6%, Fy 2005 only showed a ROTC of only 15.7% and the most recent 4 quarters numbers are only showing a ROTC of only a 15.3%. Although the numbers is still impressive, one could argue that a visible downtrend can be seen. And the interpretation could be, yes the initial expansion is justifiable but pace of expansion has grown way too fast and that the company could not generate enough returns to justify the huge outlay in its expansion.

Again... two sides of a coin.

How would one interpret this?

And here is another more interesting issue. Blogger Ichi The Killer , mentioned the following:

  • I have many of the same reservations about it, but still it keeps going up ... so what can we say, right?

Ahh... this one issue that will forever exist in the share market and it depends so much on how the individual handles such situation.

Take Megan Media last quarterly earnings. Despite it reporting a huge jump in earnings, the investor finds their earnings so suspect since the main catalyst for the huge jump in the earnings is caused by a shift in accounting. Crudely put, it was simply an earnings made by the accountants.

And the market reaction? The stock went zoom, zoom, zooooom from 60 sen to 70 sen.

How?

Well stuff like this will always happen. Take trading for example. A trader could find a whole bunch of stocks that he or she is not comfortable with it. And yet, these stocks yet went zoom, zoom, zooooom too!

How?

Should the investor or even trader adjust their strategy/game plan to try to catch every uptick, every stock movement?

My say? I believe in sticking to what I am comfortable with. Stick to my comfort zone and play the game that most suits me.. yup, play the game where my chances of winning is good!

Oh... remember the story of the 3 legged mahjong and dead dummy mention in this blog posting?

Let me repeat here again... :D

Now my Granny simply loves playing either Mahjong or Dead Rummy. Now she really excels in the game of mahjong, especially the 3-legged mahjong, in which I would say that she wins probably 7 out of 10 times whenever she plays. Her winning average is about 70%. In the game of dead rummy, she ain't as hot. (not so geng wor!) She has probably a winning average of about 30%. And because of her knowing exactly what she's good at, she always, always insist to play the game of 3-legged mahjong, because she knows winning is much easier for her.

So what about me?

Me? LOL!.. Firstly, I am good at Dead Rummy and my best strategy is to avoid her at all cost at the mahjong table and wait patiently to play Dead Rummy with her. LOL!.. yeah, I am indeed being very snake here (ho ho ho) but by playing only Dead Rummy with my Granny, I know very well that I am playing my best game verus her worse game. Won't this improve my chances of winning? (else? I will be slaughtered at ze mahjong table and be ze water fish!)

----------------------------------------------------------------------

Some interesting comments from hhc. April 7th. 7.20 pm

  • Let's look at the sector Topglov is operating with. It's a volume game business with pretty tight margin which means anymore price cut will hurt its bottomline.

    Imagine what will u do if u r the owner? (of course we can just DONT invest in it). But, as the owner, the only logical way is to make yrself HUGE before anyone else and elbow them out. If u r the number one in these kind of volume game, u can control a lot of things to protect yr margin.

    ok then, how to increase size?
    1)Build new plant and reinvest yr profit (too slow , i think)
    2)Leveraging and M&A. fast but will attract a lot of attention and risk of indigestion.

    Topglov chooses the 2nd part which is , i will say pretty well run, at least until now.

    I dont like its balance sheet but i do admire that Topglov boss has the gut to face the world. If i m not mistaken, MR Lim stil hold a lot stake in topglove.

    And generally, no hanky panky deal between major shareholder and company so far which is the sign that the owner is willing to share the wealth with minorities.

    Maybe that's why fund managers like it and it's all in its price. If they are not long term investor, u wont see topglov volume is decreasing a lot from last years. One explanation is that ppl are holding the share.

    Lastly i fully agreed with yr concern and i was out from topglov not so long ago. There are value elsewhere...

Read more...

Top of Ze World: Part V

Wednesday, April 5, 2006

Back in 2001... that was the year Top Glove was listed on KLSE. On Oct 2001, they announced their 2001 q 4 earnings. (it would good to note the announced their very aggressive ambition, Top Glove Forecasts 40% Sales Growth two days after releasing their 2001 results)

total sales. 138.662 million
net ytd profit. 17.217 million
Cash & equiv 9.824 million
total debts 13.958 million

Did it deliver? A year later on Oct 2002, they announced their 2002 q4 earnings.

total ytd sales. 181.055 million
total ytd net profit. 18.036 million
Cash & equiv 21.214 million
total debts 13.440 million (net cash 7.774 million)

Sales revenue increased a lot but profit were flat. Ahh.. cash grew nicely.

Under the title of Margin Pressure, dated 22 Oct 2002, Surf 88 wrote the following...

  • Margin squeeze. In our previous result commentary (see ), we highlighted that Top Glove (RM2.12, stock code 7113) could have locked in rubber stocks at lower prices and hence the impact of higher rubber prices would only manifest in Jun-Aug 2002. This appears to be the case, as operating margin dropped to 13.9% in Jun-Aug 2002 from 16.0% in the preceding quarter. As such, pretax profit only rose 6% despite 19.0% turnover growth. Deferred taxation further depressed net profit to show an 11% decline.

    Results in line. Overall, the full-year results were within our expectations, where topline growth was largely driven by a 23% capacity expansion but profits did not keep pace as margins fell from 17.3% to 14.9% due to higher raw material costs.

And here is a snippet from a Star interview back in 2002...

  • According to Lim, Top Glove’s second factory in Thailand is scheduled to begin operation next month while the one in China will start in March next year. Top Glove currently also has five factories in Malaysia.

New 2nd factory starting in Thailand... the start... the begining of the explosive, promised growth in earnings.

Here is Top Glove's 2003 Q4 quarterly earnings.

total ytd sales. 265.089 million
total ytd net profit. 25.222 million (ahh... ze big jump in net earnings!!!)
Cash & equiv 22.051 million
total debts 39.289 million (net debt of 17.238 million)

point to note... last fiscal year, Top Glove was in a net cash position. To achieve the jump in net profit, from 18.063 million to 25.222 (or an an increase of 7.159 million), Top Glove went from a net cash position of 7.774 million to a net debt of 17.238 million.

So, a year later... the big jump in earnings happened and Top Glove delivered.... but alas.... Surf 88 sudah bungkus by then .... anyway we now see that this company has really, really been aggressive. Many new production lines were set-up, new plants... and most of all.... we have Ze birdie thingy!

Ahhh.... good birdie fortunes + aggressive expansion = fantastic growth for 2003.

Now, here is Top Glove's 2004 Q4 quarterly earnings.

total ytd sales. 413.967 million
total ytd net profit. 39.509 million (wow.. bigger jump in net earnings!!!)
Cash & equiv 30.226 million
total debts 63.063 million (net debt of 32.837 million)

again some points to note... last fiscal year, Top Glove was in a net debt position of only 17.238 million. To achieve the 'additional growth', from 25.222 million to 39.509 (or an an increase of 14.287 million), Top Glove went from a net debt position of 17.238 million to a net debt of 32.837 million. (or it increased its net debt position by 15.599 million). How was their expansion justifiable?

anyway how was Top Glove achieving its super duper Top Glove? Here is some RHB notes which indicates that the growth is via acquisitions of new factories and starting of new production lines...

  • It has commissioned two new lines each in Factory 5 in Ipoh and Factory 6 in Phuket at end-August 2004. In Factory 5, Ipoh, the target is to install 10 new lines, bringing its capacity to 175m pieces a month, from the current level of 110m pieces a month. In Factory 6, Phuket, the plan is to replace the existing seven production lines with 10 advanced production lines, lifting capacity from current level of 35m pieces a month, to 65m pieces a month. Meanwhile, installation of new lines in Factory 10 is in progress while construction of Factory 11, Klang is going on full steam. It aims to commission a total of at least 155 production lines with annual capacity of 13.0bn pieces a year by end-2005. It has identified two new sites for two new factories which will be constructed in CY2005 and CY2006, respectively.

    It has completed the acquisition of the remaining 40%-stake in Factory 7 in Hatyai, Thailand on 11 October 2004. Plan is in place to increase its capacity from current level of 1.08bn pieces a year to 4.8bn pieces a year by end-FY06. Its proposed acquisition of the remaining 45%-stake in the China plant is expected to complete by end-1QFY05.

How?

ok ... let me try to give an unbiased view on what is happening... :D.... try hor...

Firstly when there is huge spikes in sales & net profit, the first thing i always check on is whether there was any company acquisition which might have caused the spike in earnings.

Well, what i saw is TG is simply a very aggressive and ambitious company. It started off by buying a couple of factories in Malaysia and started expanding its production lines. It then moved on to Thailand and it even moved into CHina.

So over the years, TG focus was simple. Aggressive growth thru acquisitions and organic growth. And plans to stick to this gameplan for the next few years.

And of course all this has been helped by the birdie issue in 2003.

And the end result, although we are seeing the fantastic growth in earnings, TG is paying a hefty price for their expansion.

And last year, Oct 2005, Top Glove reported its 2005 Q5 quarterly earnings.

total ytd sales. 641.827 million
total ytd net profit. 58.141 million (wow.. earnings still very good!!!)
Cash & equiv 31.755 million
total debts 154.191 million (net debt of 122.436 million!!)

How?

Let's look at those issue or rather those points again.... last fiscal year, Top Glove was in a net debt position of 32.837 million. To achieve the 'additional growth', from 39.509 million to 58.141 million (or an an increase of 18.632 million), Top Glove went from a net debt position of 32.837 million to a net debt of 122.436 million. (or it increased its net debt position by 89.599 million).

How was their expansion justifiable?

Which was why I blogged that posting in Oct 2005. And let me repeat the main issues.

Sooooooooooo despite it’s great sales and net profit growth… it’s bottom-line certainly ain’t too top-looking for me.

Btw…in my opinion, the need to have some sort of understanding of the explosive growth in Top Glove is kinda important.

So far, it looks to me it has been 'quite' prudent in the number of factories it has been adding per year. Yes, adding a new factory per year is indeed aggressive but i think it has not been too aggressive. (tiok boh?) From a management point of view, consideration should be given regarding the ability for Top Glove to manage the growth in its factories. (Layman's view: Buying and managing a business is always manageable, but if u buy 'too much' businesses, then the very obvious issue, is can we manage all these factories?) Yup, the issue of managing and cordination of all factories in a profitable and efficient manner becomes a concern if the company increases the number of factories too fast.

Whereas, the increment in production line should be a much easier task to handle compared to the number of factories.
(tiok boh?)

Now one probably ask why all this? Growth in a company is always good however commonsense would tell us that excessive growth might pose some danger too. As such, this is why I am not discounting this issue.

Which is what is happening in Top Glove isn’t it? The company is expanding and expanding and expanding. Buy/adding a new factory here and there… but all these capex comes with a huge borrowing cost… and in me opinion…i the end result just does not justify all these expansions. Take a look at their Thailand and China segmental results. Does it justify all the moola spend expanding into these markets?

How? What say u?

Am I too prejudiced against what Top Glove has achieved so far?

Is all my mumblings not valid? Or am I mumbling just for the sake of mumbling?

:D

Read more...

Top of Ze World: Part IV

Last edit: 6th April 9.35 am

Found the following comment in my blog entry Top of Ze World: Part III

  • Strictly followed Ben Graham, "a good company is a company made more money than it spend", i have no objection to this. But, sorry to say that this statement is too general. Stocks are different from each other, we cannot apply this rule across the board. On the Topglove case, i am of opinion that a good company should employ the profit/equity wisely, either thru' business expansion or returned to shareholders. I personally prefer business expansion. Pertaining to debt, a am of the opinion that some manageable debt is acceptable. Of course borrowings come with a cost. I do agreed with U that the pace Topglove is expanding is to fast.

And here is my reply:

  • You see, yes I do agree very much that a good company should employ their profit/equity wisely, which as you have said, either thru business expansion or returning the excess cash back to the shareholders.

    And this is the very issue here in Top Glove.

    Is Top Glove expanding their business wisely?

    Take a very good look at their cash flow.

    Based on current numbers... Top Glove recorded a record half year earnings of 38.360 million.

    And the very same question I asked back in first posting in Oct 2005, I asked again yesterday, where is the Money? Where is the wealth generated?

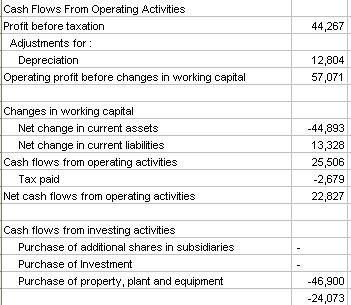
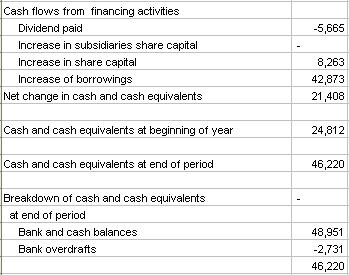
    In this quarterly earnings, Top Glove mentioned that it's piggy bank cash at the start of the year was 24.812 million. At the end of this quarter, yes cash increased to 46.220 million BUT this was aided by an increase in borrowings of 42.873 million. If you minus out the borrowings, where did that earnings of 38.360 million go? And what if you take into consideration of the depreciation charges of 12.804 million?

    Should one be worried that in Top Glove example, we are seeing a company that has been constantly consuming more cash than it generates?

    And then what about the end results from Thailand and China?

    And asked in the blog postings: 'And how did their current Thailand and China plants results appeal to you?'

    Now these are the issues I have raised...

    What's one opinion on it?

    Do you agree or do you disagree?

    For some.. they get worried... company cash flow has not been positive for a long time already, so is it wrong to be worried? Is the justifications to be worried valid?

    However... ahhh... the differing opinions.... :D

    For some.. it is considered OK.. since they consider that because Top Glove is expanding and has the inspirations to be the TOP GLOVE MAKER in the world. And to be no.1, some sacrifices needs to be made. The company has to use their cash flow to fund the expansions. And if that is not enough, the company has to borrow more to fund the expansions.

    Ahh... do you see the differing opinions?

    Which is right?
    Which is wrong?

    I have no idea... me just raised the issues only via my mumblings...

here's a reply from 2nd brother on this issue.. 6th April 8.00 am

  • Accordingly to Robert Hagstrom in (The Warren Buffett Way) and Phil Fisher in (Common Stock Uncommon Profit), how a company employ its cash depend on the stage of a company/business. At Topglove, it is at growing stage (Stage 2). It is growing so fast, every dollar they made have to plunge back for expanding the business. The profit itself is not sufficient enough for increasing production capacity, Topglove need to borrow more money to expand. Therefore, cash in hand is not a good tool to measure the company.

    As business expand, of course the increased of working capital is a by-product. Strictly follow the latest quarter report, there was an increse of 30++million in working capital. Another 45 millon was spend on the production lines.

    Althought the cash flow is not "pretty enough", i personally feel that it is not a alarming sign yet.

    What i want to say is all these cashflow/ debt level are depend on the stage of a company.

    Strictly followed Phil Fisher and Micheal Porter, low-cost producer would win especially in the commondity game. Since Topglove is the low-cost producer, i think they would win in this game.

    In glove industry, scale of economy is crucial. Topglove yet to achieve scale of economy in China, so the reported profit would not be impressive. Maybe we would see some improvemnt in the offing.

Reply (April 6th 9.35 am):

For me, it depends on what one seeks for when they invest in a company. Now as mentioned many times before, the key to a successful investing is pretty much simple. One seeks to invest in a good company at a cheap price. And obviously the very key to this simple statement is the definition of 'good' and 'cheap'.

Now let's take the issue of good. What is considered good? Some wants to see the creation of wealth and on the other hand, one wants to see the company simply grow. And on the other hand, some see both as a must in their definition of a good company. They want to see the creation of wealth and they also want to see the company grow. And of course, such opinion simply varies.

Me? I would want to see the creation of wealth but yet I also want to see growth... LOL!! ... yalor.. I am way too demanding... :D

Ahh... am I wrong to be so selective?

For sure, some finds it acceptable to have an aggressive company, deploying every single cash back into the business for the sake of expansion. And if they have to, borrowing is needed. As mentioned again, such sacrifices is a must if the company wants to grow.

For some, they might ask if such management practise is prudent? For they would argue that expansion is a must BUT it must not be made at all costs. Spending all the cash flow and incurring loans to fund such expansion might be considered excessive. The arguement is that nothing truly great is made via fevered acquisitions of companies and that frequent acquisitions are a sign of weakness, of misplaced priorities and of the inability to enhance worth from within. For them they would rather see their company grow from their own funding. For them this is the real worth. Else they consider it as artificial engineered growth.

How?

Two school of thoughts. Yes?

Well, since I am one that wants to see the worth and yet one want to see the growth, perhaps it would be better if I explain more in terms of my views on what is happening in Top Glove.... (sorry.. let me start a whole new posting else this posting will be way too long..!!)

~~~~~~~~~~~~~~~

ps... I have turned this into a whole new blog posting into a discussion and if any1 wants to have their say, you are more than welcomed......

Read more...

Top of Ze World: Part III

Tuesday, April 4, 2006

* edited 5th April 2006 *


Past postings:

Flashback:

In the first posting, I wrote the following..

  • However….what puzzles me is… where is ze Moola?

    Mana pergi tok?

    If i remember correctly, Jason Zweig stated somewhere (cannot remember which page lah) in the Fourth Revised edition of the legendary Benjamin Graham’s book, “The Intelligent Investor”…the best definition of a good business is that the good business generates more cash than it consumes.

    The good business is generating more cash of the company’s piggy bank and the company’s piggy bank grows at a healthy pace.

    Think about it.

    Isn’t this what we want for our investment?

    Now if a company keeps growing in size and expanding and expanding….sales is growing lah, net earnings is also growing at a fantastic rate….but then... somehow the end result is not there.. cos the company’s piggy bank is NOT reflecting the excellent result. Yup, company sales are increasing, net profits are increasing BUT cash is depleting. And in some drastic cases, the company’s loans are increasing too.

    And this is my current prejudice against Top Glove.

    Where is ze Moola?

    Top Glove announced it MADE a net profit of 58.1 million for the current fiscal year 2005.

    Fantastic! Bravo! Superb!

    However.. open the company’s earnings excel file.. and look at the CF worksheet.


    Line 41: Cash and cash equivalent at beginning of the year was 16.168 million

    Line 43: Cash and cash equivalent at end of end of period was 4.616 million.

    Ahem.

    4.616 million wor… and according to the company it MADE 58.1 million. Isn’t the company consuming MORE cash than it generates? How? Would u justify Top Glove being a top business?

    And Top Glove’s total borrowings now total 154 million. Errr… a year ago… how much ar?

    Sooooooooooo despite it’s great sales and net profit growth… it’s bottom-line certainly ain’t too top-looking for me.

    Btw…in my opinion, the need to have some sort of understanding of the explosive growth in Top Glove is kinda important.

    So far, it looks to me it has been 'quite' prudent in the number of factories it has been adding per year. Yes, adding a new factory per year is indeed aggressive but i think it has not been too aggressive. (tiok boh?) From a management point of view, consideration should be given regarding the ability for Top Glove to manage the growth in its factories. (Layman's view: Buying and managing a business is always manageable, but if u buy 'too much' businesses, then the very obvious issue, is can we manage all these factories?) Yup, the issue of managing and cordination of all factories in a profitable and efficient manner becomes a concern if the company increases the number of factories too fast.

    Whereas, the increment in production line should be a much easier task to handle compared to the number of factories. (tiok boh?)

    Now one probably ask why all this? Growth in a company is always good however commonsense would tell us that excessive growth might pose some danger too. As such, this is why I am not discounting this issue.

    Which is what is happening in Top Glove isn’t it? The company is expanding and expanding and expanding. Buy/adding a new factory here and there… but all these capex comes with a huge borrowing cost… and in me opinion…i the end result just does not justify all these expansions. Take a look at their Thailand and China segmental results. Does it justify all the moola spend expanding into these markets?

    How? What say u?

    Am I too prejudiced against what Top Glove has achieved so far?

Top Glove announced its quarterly earnings tonite.

Let's look at their cash flow...


how?

And again.. Where is Ze Moola?

Did Top Glove's cash flow improved?

Was my earlier concern still valid?


Take a look at their balance sheet...

See how the total loans have increased a lot?

Short term Loans is now 47.934 million. Long term borrowings is now 81.544 million and Top Glove has issued bonds amounting 70 million.

And how did their current Thailand and China plants results appeal to you?


And how would one evaluate the following past comment below?

  • Which is what is happening in Top Glove isn’t it? The company is expanding and expanding and expanding. Buy/adding a new factory here and there… but all these capex comes with a huge borrowing cost… and in me opinion… the end result just does not justify all these expansions. Take a look at their Thailand and China segmental results. Does it justify all the moola spend expanding into these markets?

Am I Wrong?

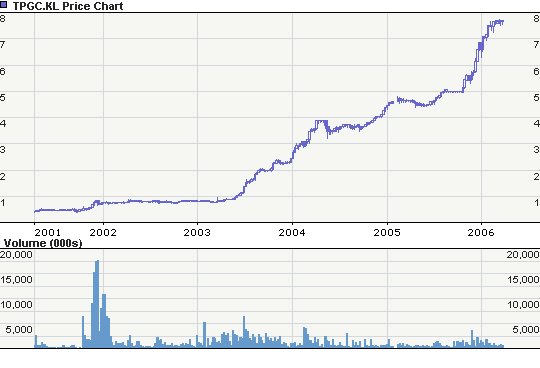
Btw... Top Glove is now at 7.70.... and all this is a mere mumbling from me... i have no idea what the share will do... will the so-called improved earnings seduce some demand today? I have no idea dude...


Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP