Powered by Blogger.

Home

Showing posts with label Worldwide Holdings. Show all posts

More On Privatisation Issue

Wednesday, September 6, 2006

Fellow blogger, Salvatore Dali, featured my post, Privatisation, a heathy trend? on the very popular blog, Malaysia Finance Blogspot, in a posting called Privatisation / M&A In Malaysia.

I have a couple of comments on it and since it's rather longish, I thought it would be best that I made a whole new blog post. Plus this posting is not a direct reply to Sal but more mumblings on this issue frome me.

This was Sal's take.

  • 4) For me, the issue is when a company is completely taken off the block. For example Worldwide, many minority shareholders buy for the long term as its NTA is anywhere from RM4.00 - RM5.00 while the market price traded usually closer to RM2.00. Naturally its a no-brainer for controlling shareholder to privatise the company especially with excellent cash flow. Merchant bankers worth their salt would be scrambling to lend money to the owners to do the buyout and get healthy advisory fees in return in an almost risk free scenario. The G.O. at RM3.50 seems rich compared to the market price for the last 12 months, does that mean minority shareholders should be appeased? The straight forward answer is NO. M.I.s invested for the long term to realise the full value of the company, even though RM3.50 is a huge premium to average market price, we do not know M.I.s entry price or investing objectives. While we cannot expect the controlling shareholder to offer RM5.00, we do expect a closer price to underlying value of the company.
  • Part of the problem of growing privatisation is that the market does not value shares properly. Worldwide has been trading way below NTA for such a long time

Ah, yes there are so many different types of investors around. Some speculated but believes that they are investing and then there are some plain old investors. Investors, who would invest in a stock based on a business perspective. In Worldwide Holdings: Value or Value Trap?: Part II , I have clearly brought out the issue of value versus common business logic. The value was there always but because of the lack of management quality, how could the investor invest in such a company believing that they would be adequatly compensated for taking the risk in this company.

This was what's said then.
  • Its total earnings for fy 2005 was 50.708 million versus fy 2004 total earnings of 52.632 million. Another sluggish performance. And what was Genting Sanyen Power earnings contribution to this group? 57.641 million.And again... don't you wonder what's happening in this listed company? Crudely put.. some might even question what the management is paid to do!
See the point? It's a known fact that Genting Sanyen (GS) is contributing so much money to the company. 57.641 million was what Worldwide said it contributed. But what about the rest of the business in the group? It contributed NOTHING. In fact, to be precise, it was a burden to Worldwide for total net earnings was only 50.708 million.

In Worldwide Holdings: Value or Value Trap? I drew up a table which clearly highlighted that showed from 1999 to 2003, if one discounts the GS conrtibution to the group, Worldwide would have lost money 3 years out of that 5 years. In short Worldwide has a historical record of making poor business ventures.

And in my opinion, this was why Worldwide was trading at such a low price for such a long time. There was value in the company no doubt but because of the management issue, I questioned the viability of an investment in the stock. Hence the title of the inital post, Value or Value Trap.

Anyway, let's wipe this out and assume that Worldwide is a CLEAN company without the poor management issue.

Now back to the issue of value.

How does one to value this GS stake? They, the market are insisting on RNAV. HLG Research values Worldwide's stake in GS to be worth 1.87 per share, which works out to a mere 330 million.

Can it be right when GS contributed 57.641 million in the last fiscal year? If you own such a stake, would you be willing to sell at a mere 330 million??

As mentioned in the other blog posting, Do you think privatisation is healthy? , to make an equivalent of 57.641 million, the comparison yardstick is the 4% money rate, in which one has to invest a whopping 1436.53 million to get an equivalent return, or the equivalent of 8.00.

Some would have used this as their investing objective.

And this is based on the GS stake itself, discounting Worldwide's landbank and waste management business and the piggy bank cash.

And this is why some would regard this GO of rm3.50 as shambolical.

So what can the investor do?

Is it fair?

Why shouldn't this GO, from the minority investor's perspective, be regarded as a business proposition?

The majority shareholder is making an offer to buy the shares from them.

Should the minority investor even sell at a discount?

Shouldn't the majority shareholder be buying it a premium instead?

Me? I hope they realised that they are short changed BIG TIME.

Amazing. The share market is the only place where business offers are so lopsided. I have seen it in the privatisation of Bumi Armada and I have also seen it in the case of Propel and Metro Jaya.

Anyway, I believe that there is something good to observe from this GO.

The argument is the minority shareholder is being offered a very raw deal. Short changed from getting their adequate compensation for risking their money in investing in their stocks.

Let's watch what will happens...

1. Will the authorities do something? Can the investor depend on someone, some party will come in and rescue them from being short changed?

2. If no... what's the best course of action in terms of an investor?


my answer? (let's see if I am right)

1. Fat hopes. Never rely on the 'market' to rescue you.
2. AVOID.. AVOID.. AVOID.. AVOID investing in stocks whose management/owners one cannot trust or whose integrity is questionable. (ps. big difference between investing and trading)

And in the issue of Worldwide, see why I hold my stance on it? Yeah, the speculators they made money and my congratulations to them but do look at the bigger picture. The market needs speculators just as it needs investor and I, from an investor point of view, to see such corporate exercise is shambolical to say the least. If the investor is never given a true chance to be adequately compensated for investing in the stock, the investor is better off avoiding these stocks or maybe shunning the share market totally if such unfair practices were to continue.

Oh... last but not least...


  • That's because in deciding for privatisation, the deal hugely favours the controlling party already - hence someone must look out for the long-suffering small tenacious investor.
Well said Sal!!!

Imagine the market without the small tenacious investor!!!!

Read more...

Do you think privatisation is a healthy trend?

Friday, September 1, 2006

The privatisation of Worldwide Holdings.

As asked in earlier posting, do you think that is this a healthy trend?

Let's take a simple look at the recent proposal made to privatise Worldwide Holdings.

Let's not complicate matters and let's keep the issue is simple. Let's do this exercise from a simple reverse angle. Assume we are a potential buyer and assume that we, owns no shareholding (easier to see if viewed as a whole and when done, just count back the percentage) in this stock. And the objective of this exercise is to see if we are getting a good deal for this exercise or not. Let's see how profitable it is.

1. The crown or the moola in Worldwide is its shareholding of 20% in Genting Sanyen power plant (GS). Simple counting again. Just count how much this plant is contributing per quarter.

How much is this power planting contributing to Worldwide each year?


The above snapshot is taken for Worldwide's last fiscal year Q4 quarterly earnings. As can see from that table reported by Worldwide, GS is contributing some 57.461 million per year.

So if we buy Worldwide, we effectively buy the rights to receiving this 57.461 million per year!

This is what Worldwide gets. It's like rental money from its ownership in GS. How you want to value it?

Let's do some simple counting. Let's assume that we can get fixed deposit rates of 4% per annum. To get the equivalent of 57.461 million, how much would we need to deposit?

Answer?

Are you ready? How about 1436.53 million!!!

Now get this.

Do you reckon it is a good deal to pay 3.50 per share for Worldwide?

Now, Worldwide has some 177 million shares. So assuming we buy the whole company, we would need to pay 177 * 3.50 or some 619.5 million!!

And by paying 619.5 million, we get to keep that 57.461 million per year.

Which is a better deal? You tell me.

2. Just by buying Worldwide, we are already getting such wonderful return of investment from the money received from GS.

What about Worldwide Holdings itself? Worldwide is not an empty company.

* Cough* Its piggy bank cash is worth some 120 million wor.

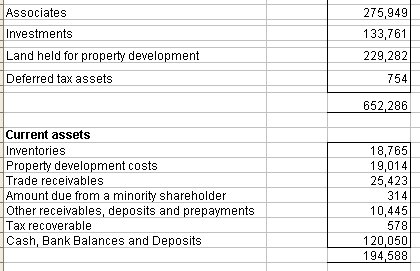
How? Is this free money? Take a look at Worldwide's last fiscal year Q4 assets stated in its quarterly earnings report.


Based on 177 million shares, the cash per share is already worth some 68 sen.

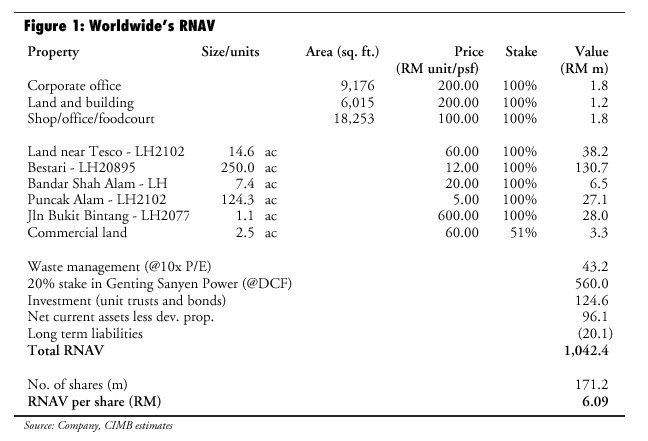
3) And what about it's landbank? CIMB on 4th April 2006, wrote on this stock. This is how it described Worldwide's landbank.


See that nice piece of 1.1 ac land on Jalan Bukit Bintang? See CIMB's valuations?

4) And what about it's waste management business?

So if we offer 3.50 for Worldwide, which effectively values Worldwide at 619.5 million, frankly speaking, do you think we are getting a good deal? We get the rights to receive some 57 million a year from the power plants, we get to keep the company cash, we get the land banks and also we get to have a waste disposal business too?

Don't you think we are getting an extremely out of the world deal of a lifetime?

And oh... so do you think privatisation is a healthy trend?

Read more...

Value or Value Trap in Worldwide: Part VI

Thursday, April 6, 2006

Hmm.... it seems that CIMB wrote a write-up on WorldWide today and with that write-up, it proved to be a catalyst itself, driving the stock by as much as 14 sen today!!!

And the Edge had an article based on that
write-up...

  • CIMB Investment Research reported that Worldwide has RM249 million net cash and equivalents and valuable stakes in the power and waste management businesses.

    The research house said Worldwide shares are backed by RM1.45 cash per share.

    "Based on our RM2.8 billion valuation for the 720MW Genting Sanyen IPP, Worldwide's 20% stake alone is worth a massive RM560m or RM3.27 per share, well above the share price," it said.

    It said investors were getting the RM249 million net cash (RM1.45/share), property land bank and waste disposal businesses for free and more.

    It estimated Worldwide's revised net asset value per share at RM6.09 more than triple its share price. It said the stock was also trading at a hefty discount to its NTA/share of RM4.23.

    "Although Worldwide is cheap on discount to asset backing and P/E basis (6 times historical), the key problem is the lack of share price catalysts," it said.

    Worldwide offers good value to long-term investors with the patience to wait for an eventual re-rating, it said.
First of all.. if one refers back to this blog posting Part III , one would have noted that these are the 'almost' the same exact issues mentioned back in June 2003. See the Edge article: Worldwide Pt 2 – assured earnings, undervalued assets

But in today's CIMB write-up, CIMB is declaring that the Genting Sanyen stake is worth so much more.

  • Based on our RM2.8bn valuation for the 720MW Genting Sanyen IPP, Worldwide’s 20% stake alone is worth a massive RM560m or RM3.27 per share, well above the share price.

Hmmm.... rm 560 million wor!

And then it mentioned that Worldwide has RM249 million net cash and equivalents..

Ah... I discovered something new today.

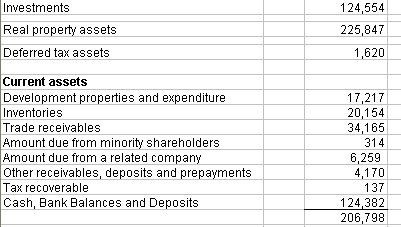
The following is a screenshot of Worldwide's balance sheet.


Ahh... as can seen, under current assets, Worldwide's cash, bank balances and deposits totals only 124.382 million.

And on the first line, you would see an entry of 'Investments' totalling some 124.554 million.. same period a year ago? Worldwide's such investment was only 69.075 million!!

And according to CIMB ( see a screenshot of their report below) these 'investments consist of unit trusts and bonds!)


Ahem... unit trusts and bonds!!!... and the obvious point of debate is why should a company like Worldwide (which had a poor history in investing... such as their theme park debacle recently) be dabbling in such investments??

Now if I check on Worldwide earnings notes, I could NOT find Worldwide's explaination on how and why such investment increased by so much. Lack of transparency???

What unit trusts did Worldwide buy?

What kind of bonds did Worldwide invest in?

And also... since such investments consist of unit trusts and bonds, how reliable is CIMB's value of rm249 million in cash and equivalents?

Ahh... anywayyyyyyyy.......remember me stating the issue of Worldwide's poor investment history?

Well... just for your information... Worldwide does dabble itself in the sharemarket too!!!

Yup!

And again, considering the issue of Worldwide's poor performance as a property developer, would the investor be faulted for questioning why Worldwide is dabbling in purchase and disposal of listed securities? Shouldn't the company management be more focused on their jobs? Would it be wrong to be so cynical? Well, consider the fact that Worldwide's value of investment in bonds and unit trusts totals some 124.544 million is more than Worldwide's sales revenue for its fiscal year 2005.

How?

anyway... do u wonder their performance in their purchase and disposal of quoted securities? Think they are good ah?

well the following table... err... u better have a look urself at those figures...


Err... how?

And another issue.. is the following statement from CIMB is not mentioned in the Edge article.

  • Although Worldwide is cheap on discount to asset backing and P/E basis (6x historical), the key problem is the lack of share price catalysts. Earnings outlook for FY06 is flattish as contribution from waste management will likely dip temporarily due to relocation to a new site. Also, the group does not appear keen to unlock the value of its assets, including its stake in Genting Sanyen, unless it can put the
    proceeds to good use.

See the points in red. Do you think that these two issues are rather important?

how? Should the Edge be omitting such issue?

(ps... and if consider the fact that Worldwide's management INCREASED their investment in bonds and unit trusts from 69.075 million to 124.382 million in their fiscal year 2005, does it appear that Worldwide is keen to unlock the value of their 'assets'?)

Anyway... what do you think?

Value Trap?
Or there is really VALUE as statetd by CIMB!

How?

Oh... some of the points made by hhc in part IV is worth noting now... :D

  • 2)Small time trader or ikan bilis
    Rule one to rule 9 are still attractive stories. They dont care what is it but as long as there is a renewed interest in this stock, they will swarm in. Most of them will be eaten by the ikan besar. Some of the nible one will managed to snatch the bait put out by big fish.

    OK back to TA.

    For the last whole year, Wldwide has been building base at around 1.8 region. IN the last 3 months, the vol is increasing and it's now trading close to its resistance area at 1.9 area and inside its mini uptrend established on Oct last year.

    Its technical stand is interesting but i would pay attention if i can break and hold at above RM2 area. IN the mean time, i would say the bull and bear are fighting out. The outcome is still unclear. (chart pictures are contributed by hhc... many thanks!!)


------


past mumblings on Worldwide:

  1. Worldwide Holdings: Value or Value Trap?
  2. Worldwide Holdings: Value or Value Trap?: Part II
  3. Worldwide Holdings: Value or Value Trap?: Part III
  4. Worldwide Holdings: Value or Value Trap?: Part IV
  5. Worldwide Holdings: Value or Value Trap?: Part V


Read more...

Value or value Trap in Worldwide: Part V

Sunday, March 19, 2006

The following are some issues raised in the shoutbox by one NewBee.

Although the IP address of both NewBee and KingPin is suspiciously close, nevertheless, I will still answer the questions raised in good faith.


  • Are you saying when buying shares, dividend is not a big issue to consider?
Nope. I did not say that, did I?

A company that is making good money and is willing to sharing its good fortunes by distributing the earnings back in the form of dividends is simply desired by all investors. Yes, dividends are of course important. But as an investor, we want to minimise as much as possible the risks involved when we invest in a company. For example, can we safely assume that a company will continue to pay the exact dividends every year? We simply cannot. In our country, 'most' companies have their cycles of good and bad fortunes. And have we not seen good companies gone bad when the management embarks on poor corporate exercise(s)? To blatantly making such assumption will be putting our invested money at risk.

So what guarantees that the company will continue to pay out good generous dividends in the long run?

Me? Yes, although there is no absolute guarentees in any company but I still look for 2 things. These two issues act as my guide on whether I should stay invested or not in a stock.

  1. A good business.
  2. A management that can be trusted.
So what is a good business? Well, the most intelligent approach as suggested by Graham and Buffett is that investing is most-intelligent when it is business like. (blogged recently)

So how good a business is Worldwide? ( Take a look at the earlier blog posting:
Value or Value Trap in Worldwide Holdings?

If you minus out the earnings contributions from Genting Sanyen... ask yourself... what has the management been doing from 1999 till now? have a look the table made again.

(If that is the case, perhaps one might want to do a new table with a column indicating this share of profit from Genting Sanyen... and of course add in a column indicating the net profit less Genting Sanyen's earning contributions!)


Does this look like a good business? Again, if you minus out Genting Sanyen profit, what have the mangement been doing all these years?

Second part, a management that can be trusted. As mentioned before, the theme park debacle. Or the recent issue mentioned about the murky dealings behind its subsidiary holding, Panaroma Worldwide, as reported in the Edge and in Malaysia Today.

How? Can we trust such a company? Can we trust the management that we will receive good dividend in the long run? What if the management embarks on another debacle project like the Sydney Theme Park?

Side track a bit.

Here's a good exercise.

On 27th June 2003, Insider Asia wrote this article.Worldwide Pt 2 – assured earnings, undervalued assets

Same old, same old. Assured earnings, undervalue assets.

Insider Asia recommended Worldwide at a price of 1.95. Today, March 2006, Worldwide price is less than 1.90.

total dividend received?

  • in 2003... Worldwide paid 3 sen tax exempt... (paid in Aug 2003)
  • in 2004... Worldwide paid 5 sen tax exempt... (paid in July 2004)
  • in 2005... Worldwide paid a 5.6 sen gross interim dividend.. (paid in Jan 2006)

If one had invested in Worldwide since 2003 because it's earnings, has it been a profitable investment?

How?

Well.. it's up to you to decide such issues... and I for one do not have all the answers... which is why I blogged in a manner of a discussion.. always welcoming honest views and opinions... but sadly in our country there exist selfish scums who lurks in stock forums who are only interested in their own vested interests...

'Hail the greatness of MY stock(s) and Speak No Evil about what stocks I own' is their utterly disgusting attitude.

Sigh!

Anyway, All I am saying is that one should not discount such issues and pin their investment on blind faith that they will continue to receive such dividends in the long run.

  • Or are you saying we should only consider the paid dividen and that the dividend that has been proposed but not paid is not a big issue and should be ignored? Is it correct to interpret dividend yield as being based only on paid dividend and omit the proposed dividend? You say your own interpretation of dividend yield is based on the dividend paid.If we base only on dividend paid and omit the proposed dividend, can we still say the dividend yield figure is correct and meaningful?

The interpretation of the dividend yield is simple in theory but complex in practicality.

In simple.. Dividend yield = dividend received / cost of investment.

Complexity. Take Worldwide.

1. If one had invested in say early Jan 2006 or end 2005, one would have received that interim dividend paid in Jan 2006. And if and if the investor continues to stay invested in Worldwide for that PROPOSED dividend, then the dividend received will be 5.6 sen + 10 sen = 15.6 sen. And the yield will be that amount divided by the price of investment.

2. If one wants to purchase now.. will the yield be the same? Will one get that 8.3% yield as suggested?

Well.. that 5.6 sen has been paid. So the dividend yield will be that PROPOSED 10 sen divided by the price of investment.

And in either case.. the dividend yield will depend greatly on the price that the investor (reader of the article) pays for the investment.

How?

For me.. I have always not bothered about talking about proposed dividends, mainly because I do not want to seen promoting the stock for my own vested interests. Such simplicity calculations is best left for the reader, isn't it?

And yes... what about corporate rescinding their corporate proposals? Not happened before? I do remember vaguely that back in 2002 or maybe 2003, there was an outroar over United Merchant Group (now known as ASCap) announcement over its proposed distribution of cash on one of the local newspapers. The company later acknolwedged that there was a mistake made on how much was to distributed back. Or what the incidents in India back in 2001 or 2002? I do remember reading multinational and well-known companies like Nestle India rescinding their proposed dividends.

Ahh.. again.. I AM NOT SAYING THIS WILL HAPPEN FOR WORLDWIDE...

All I am saying is this type of events happened before... and in the world of the sharemarket, where the banker is the corporate management and the player is us, it never hurts to be extra carefull.

Read more...

Value or Value Trap in Worldwide Holdings? Part IV

Thursday, March 16, 2006

Hmm... more feedback on Worldwide

  • The joint venture in the Sydney Theme Park is 40% indirectly owned by Worldwide and whatever loses incurred is more than cover for by its other profitable property ventures which means contribution from Genting Sanyen and waste disposal service continued to add on to the company's bank account. Look, even Warren dare not say he is always right! Meanwhile I don't see any problem with income from Genting.

==> Yes, there is nothing wrong with Genting Sanyen's money at all. In a nutshell, that's all there is in Worldwide. Which is the earnings derived from Worldwide's investment of a 20% stake in Genting Sanyen. If you take away Genting Sanyen, what has the management done since 2000?

The earlier argument was that Worldwide business is safe and protected and the management is conservative. And the counter argument was that the Sydney Theme Park venture did not paint a picture of Worldwide's management being conservative. And as argued one would be left scratching their heads wondering why Worldwide ventured in that theme park business.

  • All IPP here are doing fine. They also sold off their Holiday Inn KL and made 17mil profit.With continous build up of cash in their a/c the current price will be deem undervalued! So what are they going to do with all this cash?

Yes, all IPP are making tons of money. Too much money in fact!

However, the point here is Worldwide merely has an investment stake in an IPP. A 20% stake. That's all.

Yes, again there is no denying that Worldwide has tons of cash... but what the very key is what are they going to do with it?

What are some possibilities that could happen with the cash ...

  1. They hoard the cash. (not possible? they can hoard like UAC and do nothing)
  2. They distribute most of the cash. (if so.. the investor speculating on this issue wins!)
  3. They distribute the cash but in small amounts per year.
  4. They keep the majority of the cash.. and embarks on 'new projects'... which is not a problem.. but given the issue of the theme park.. and the questionable Panorama Worldwide thingy... how safe is this option?

So how does one rate such speculation?

more comments..

  • Great even directors of Mieco bought shares in their company so is Meico very "Geng"? If there is complete transparency in Worldwide and they are very good to minority shareholders Worldwide should be worth much more! Look there is no total transparency even in the good counters. What I am trying to point out is Worldwide will not SINK! period. I believe at its current price it is stable and should it fall below 1.80 great!

and more..

  • Ah yes talk about GLC. Bursa gave out millions in ESOS at RM3.00.Suddenly they decide to give out 82sen per share in capital repayment. Before the payment price was around 4.50 now after payment it is at 4.60...Petgas?? Maybank??

err... the discussion was on Worldwide, wasn't it?

  • Oh also some company gave little or no dividend. Liondiv, Farmbest. Wowww better still Berkshire Harthaway no dividend since 1971 and today it is worth ahemmm... around.... around I wonder how much...

and more....

  • They know it is tough making a successful venture. Now guess whether they will "kill the goose that lay the golden egg" ie sell off their Genting Sanyen. Well run IPP from genting...

and more..

  • Wldwide is risky investment but only if it's selling at revised NTA, say 4.50. But reservations about management's skills has already been fully discounted by all and sundry...why the hell you think it's selling 1.88.PKNS needs WLDwide's dividend...that's why it is paying a full 15.6 sen for the curremnt year....and probably more next year and the next since it has fat bank bal.

==> hmm.. let's be more accurate here on the issue of Worldwide dividend.

Worldwide paid a gross dividend of 10 sen for fy 2004. And for fy 2005, it had paid a gross interim dividend of 5.6 sen.

  • If robert kuok should take over the management today, the price would shoot up to 5.00....wouldn't be far fetched. So with current management, the price is discounted to the extent it gives div yield 8.3% and the possibility of more in future. What more do you want...everything must be safe safe, then quit stock mkt, put money in FD with a lousy 3%. I would say, taking all into a/c, it's a safe buy at 1.88...in fact a good buy.

==> what has Mr.Kuok got to do with Worldwide Holdings???

Dividend of 8.3%???

The risk in the stock market is always there and should never ever be discounted. Hence, if an investor does not think the stock market is safe, then the investor should always, always opt for the FD.

more comments...

  • having said that, this stock is good for those seeking safe and good dividend income over the long term, definitely better than putting in FD. Its dividend payouts can only increase because parent co needs the cash. And remember, their power business is not run by them...and that is a very very good thing...LOL. If you are selling this stock, go ahead, meanwhile I stand at 1.87 and sapu whatever I can take....LOL...

hmmm.. 'power business is not run by them... and that is a good thing... LOL'

hmm... would it be wrong if I sense some concern over the trust of the management?

If that is the case... could the investor safely expect to receive safe and good dividends over the long term? What if the management decides to embark on a funky project again? Yes this is a speculation... but there is a chance it could happen. And since if it could happen... how safe is it to assume that the investor will receive good dividends?

  • one hhc mention the directors not holding shares.....therefore implying company no good....LOL....really funny...what if I tell you there are holding millions of shares under various nominee accounts, then the company must be a really good company by your reasoning....hahaha.......directors say banyak susah, put under my name you ask where i get the money, don't put under my name you say company lousy....

If the director is not willing to own shares in the company... isn't this a valid reason to be concern? Remember the strategy in Worldwide is to invest in the share and expect to receive safe and good dividends over the long run. In the long run.. anything could happen... so is it wrong to think conservative?

  • about edge article....about wldwide going through third party to get the contract...LOL...this edge journalist is very funny...doesn't he knows this is thwe way business is done, not only here but in other countries too. You simply can't take all the money for yourself, you must split it with others, else there is no contract to speak of.

How would one rate such business dealing? Wait ... what about the issue of being transparent?

If the management is not transparent.. then how could one trust? Could one dare to ass-u-me that one could expect to receive safe and good dividends over the long run?

Btw... please let's be more diplomatic.

Comments are most welcomed but at the end of the day, let's not forget that comments are mere opinions of each individual. In the stock market, no one will have the same exact view and opinions all the time. Opinions and views will always differ.

So.. if and when an opinion differ..

I would strongly ask everyone to refrain from resorting to making FUN of names.

Such childish actions is unwanted here.

~~~~~~~~~~~~~~~

Edit: 1.50 pm March 17th

Ok.. let me throw a new poser in..

Ahh... let me be put on my speculator suit... LOL!!

For Worldwide .. the main seduction is the cash in the piggy bank.

So what's Worldwide going to do about it? That for me, I think would be the main catalyst for other(s) to speculate also on the stock, thus creating the demand for the stock. Else no demand then how to expect the stock to a-go-go?

The other issues like low PE and discount to NTA simply isn't working! As mentioned earlier, these issues simply wasn't enough to attract investors to the stock.

For example on 27th June 2003, Insider wrote the following article, Worldwide Pt 2 – assured earnings, undervalued assets . Price of Worldwide was 1.95. That investment idea simply failed to seduce investors. And in Sept 18th 2004, SBB made the same suggestions at 2.04. Again the end result is for all to see.

So... as a speculator... what do I want to see?

Ahh... for me... LOL... just me mere opinions only... and if you do not agree... state your reasons lor... as a speculator... I would want Worldwide to Show ME the Moola!!!!

Simple as that. Make a concrete effort.. let the investing world know that you are willing to share! (Share market mah... if company got tons of cash.. surely Shirley you must share. tiok boh?)

So what's the best plan? Buy and wait for such an announcement? (What shold be my safety plan? Do I have one? If they do not share or announce another one silly project again.. surely Shirley the share price might take a big hit.... tiok boh?)

Or should I wait till they announce? (what if too late? cos when they announce the share price will rocket mah!)..

Or should I be the wise speculator and consult them trading sifus?

how?

~~~~~~~~~~~~~~~~~~~~~

more comments:

Such a hot topic which i think i will add some more comments

1):kingpin
"So if you oriiginally can make margin of 50%, but have to split with others 30%, you still get 20%. Does that mean you don't want the contract anymore?"
The issue here is integrity and honest business. Are Mr Kingpin recommends to get business by hook or by cook?

2)Mr Kingpin
"You simply can't take all the money for yourself, you must split it with others, else there is no contract to speak of."
Sharing contract and profit is nothing wrong per se. The problem is co-partner with some funny fly by night companies with directors in their 30s. The best part, they dont need to come out with cash. Risiko is bornt by Worldwide and profit they sama-sama enjoy. Is this kind of business model Mr Kingpin encourages?

3)Mr Kingpin Again
"directors not holding shares.....therefore implying company no good....LOL....really funny...what if I tell you there are holding millions of shares under various nominee accounts, then the company must be a really good company by your reasoning....hahaha.......directors say banyak susah, put under my name you ask where i get the money, don't put under my name you say company lousy...."
The problem here is that worldwide has its ESOS and definitely its directors will entitled to it. If worldwide is such a fabulous company, why the director is not holding any share here. They definitely has better knowledge of how the company is doing. And we are not discussing the case of majority owner cum management case like megan. Just to put thing into perspective

Did anyone ask where RObert kuok or LimGoh Thong or Anand Krishna where they get their money? unless yr money is something from your share share business dealing......

4)Kingpin
"Its dividend payouts can only increase because parent co needs the cash. "
Are you sure? They are other faster and easier way for the mother co to get money. The simplest way is asset injection like land which PKNS got a lot. Another oversear venture is another possibility.

And i respect the way kingpin thinks but pls dont make fun on other ppl name. We all entitled to our own opinion. I ain't got pleasure in changing yr opinion to be like mind.

~~~~~~~~~~~~~~~~~~~~~~~~~

more comments:

Some of opinions

"Oh also some company gave little or no dividend. Liondiv, Farmbest.
Wowww better still Berkshire Harthaway no dividend since 1971 and today it is worth ahemmm... around.... around I wonder "

1)LionDiv
We ready has to see in the long run, how this LionDiv will become. Yes, it did make spectacular gain on Parkson listing. But, can it maintains its edge? Or will it succumb to competition. So, not much to comment here.

2)Farmbest
Is this really a run because of improving fundamental or syndicate play? The answer will be shown after a few months. If this is realy supported by syndicate, it wont hold out too long. So, let's keep our finger cross.

3)HB
Hah, do u know what is the big difference here? It is the MANAGEMENT integrity. Try to read those listed comp director report. Or doesnt Lion group owner has the track record which match HB?
I want to stress that Div Yield is not the most critical criteria for me. Just as a guideline

I found out that Mr Willy liked to use price increment to justify the stock quality. There is nothing wrong in this but dont you find that investing in a honorable management is safer? And in BSKL, we all know there are a few syndicates operating around.

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

More comments....

Just my 2 sen Ok, let's put on as trader with TA skill.
There are 2 types of TA traders. If

1)Trader who can swing a big line.
Thing to consider
a)Liquidity
b)Free float
-->Wrldwide cap now 320M. Let's say 20% is floating, that means i need at least RM64M*7 to goreng. THis is liama rule. Dont ask me why use 7
c)Attractive story
-->not much at this moment. At least all those cash per share, NTA, project are OLD story.
d)Volatility in price
-->At least still in accumulating phase. If this indeed is the acc phase, then the syn has accumulated for almost 3 years.

2)Small time trader or ikan bilis
Rule one to rule 9 are still attractive stories. They dont care what is it but as long as there is a renewed interest in this stock, they will swarm in. Most of them will be eaten by the ikan besar. Some of the nible one will managed to snatch the bait put out by big fish.

OK back to TA.

For the last whole year, Wldwide has been building base at around 1.8 region. IN the last 3 months, the vol is increasing and it's now trading close to its resistance area at 1.9 area and inside its mini uptrend established on Oct last year.

Its technical stand is interesting but i would pay attention if i can break and hold at above RM2 area. IN the mean time, i would say the bull and bear are fighting out. The outcome is still unclear.

===>>

pictures from hhc. (many thanks!!!)


------

Read more...

Value or Value Trap in Worldwide Holdings? Part III

There was some interesting comments posted in my mumbling box.

I thought I shall post it here for all to have a clearer view... (ps.. this is merely for sharing and exchanging of views.. not an issue of who is right or who is wrong.. and it's best the reader be their own judge!)

  • Worldwide landfill business is taking off and its power share gave it lots of cash through dividend payment but yet price is muted because it did not have much publicity done unlike electronics stock that got a shot in the arm due to comments from Thestar newspaper.In my opinion, Worldwide is safe counter and if one keeps it long term will receive more payment than putting money in bank FD.

If one keeps for long term it will receive more payment than putting money in bank FD.

Well that's what one wants in an investment, no doubt. However, for Worldwide, has it shown any past indication that the dividend yield is any better than FD?

With all the cash in the piggy bank now, wiill Worldwide be willing to pay more in dividends in the future? (would you consider this as an investment or would you consider it as a speculation?)

Take the best example, The Star did publish a rosy article on Worldwide but that was in Sept 18th 2004. ( click
here for the article in full ). Worldwide closed that day at 2.04 after the nice publicity article from the Star. Buying the stock then at 2.04 would have seen the investor collect a total gross dividend of 15.6 sen since then. Closing price today is 1.89.

Which was better? FD or investing in Worldwide?

Now that was the past... future? Will Worldwide be better than the safer FD rates?

  • Oppss... I mean waste treatment services and not landfill! Thousand apologies ...Okay for all you folks out there, this is the revenue/profit breakdown for 4th quarter.
  • 1.Property and investment holdings, 1.532mil/907k
  • 2.Property development, 74.712mil/6.025mil.
  • 3.Waste treatment service, 24.168mil/11.045mil.
  • 4.Others,profit 1.659mil.
  • 5. Power,57.467mil profit.
Point is... power contributed 57.467 million and Worldwide's total earnings for fy 2005 was 50.708 million.

How? Did Worldwide other business contributed positively to Worldwide's bottom line?
  • Total profit is 77.097million!!Not bad.Her sister companies all made colosal loses in property business but worldwide still brings in profit from that venture.Being a GLC its business is protected and with such huge cashpile and zero debt it may one day decide it do not need this stash away. So may give it out to shareholders. Then the price will move up rapidly. Mind you, from what I observed the management is very careful and conservative.

The point is Worldwide has a historical record of making poor business ventures!

Yes, it has a huge cash pile.. but let's not forget, if you read the star article again, the following statement is a good indicator..

  • And the proposed sale of its loss-making theme park operation in Sydney, Australia, for RM56mil cash is expected to boost the company's cash reserves to almost 81 sen a share.

The cash reserves was boosted by 56 million because Worldwide sold it's venture in that Sydney theme park. The following was a comment from a long-lost friend...

  • If you look back in history, you see that they sold a themepark in Australia. First you can scratch your head why the hell they want to invest in something like that. And secondly, the themepark was all the time losing money. ( click here for full details)

Can one gurantee that this won't happen again? Was there any hank-panky in that deal? What were the management thinking? And as mentioned by hhc regarding the cash per share..

  • Great to boast that u in a business with lot of cash in hand. But to have the cake and eat it is totally impossible. The best thing is , u will never know when the cash will be depleted (pumped into funny oversea venture with no return, remember epic in canada).

So how safe is it to invest because of the cash pile?

And lastly.. does one reckon that 'the management is very careful and conservative'.?

How?

Comments and feedback will be welcomed...

Oops here is more.. LOL!!

  • What interest me is its huge cashpile and the conservative management coupled with a safe and protected business.Remember what you preach us on Warren Buffett's investment strategy.

Safe and protected business? I guess you mean that WEB stressing in investing in business with a strong competitive advantage. So where is the advantage in Worldwide? Their earnings contribution from Genting Sanyen is via a 20% stake. A minority stake. How safe is this?

Conservative management? Their theme park venture was a poor indicator of their conservative management. Don't you agree?

~~~~~~~~~~~~~~~~~~~~~~~

  • kingpin:well i bought it 1.78, and it pays 5.6s +another 10s this year 9total15.6s)...definitely better than FD. The power business contributes about 75% and landfill maybe 10%, so forget its property business...so long as it doesn't lose too much on it. Wldwide is definitely a buy at 1.88.

==>' so long as it doesn't lose too much on it' - good point isn't it?

~~~~~~~~~~~~~~~~

7.45pm March 16th

From Our Goal

  • Our goal is to acquire either part or all of businesses that we believe we understand, that have good, sustainable underlying economics, and that are run by managers whom we like, admire and trust.

~~~~~~~~~~~~~~~~~~~~~~~~~

from hhc:


Since the topic is v hot, i would add some more comments on this worldwide.

From KLSE-RIS
Substantial Shareholders
Perbadanan Kemajuan Negeri Selangor 89,835,590 52.780%
Malaysia Nominees (Tempatan) Sdn Bhd - Kumpulan Perangsang Selangor Berhad 10,000,000 5.870%

Just by looking at its major shareholder, u oredi know how good they are in managing company in commercial sense.

2) Director ownership of the company.
From KLSE-ris again, we will see that its CEO
YBhg Dato' Haji Ibrahim Md Yusof, DSIS, SSA Group Managing Director 104,000 share Only,
The other director holds 0, kosong share.
Let me ask u, if the comp is so profitable, why the director wont put his money into it?
Even with ESOS going on, the director is still not holding any share in this comp.

3)GLC
When it's GLC, u better stay away. In msia, sometime, political consideration will overshadow commercial one. See Tenaga. And u have to know the gov mentality, even they are flushed with cash, why they need to share it with u? Who do u think u are? Can u raid the company? With 60% in the hand of Selangor gov, u r strcuk w them. Dancing w the wolf(es), i think.

If u like this kind of yield, cash and nta stuff, i suggest u look at other better candidate.

Lastly, i think warren also recommend that the management staff is professional and well motivated. What is a better motivation than owning part of the comp you manage and enjoy the long term return together? If the director dont trust their own skill in growing the company, i dont see reason why i should part w my hard earned money.

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

Moola: 9.32 pm March 16th

more from hhc:

found interesting article from malaysia today..

"Worldwide Holdings Berhad (WHB)

This is what The Edge reported on 7 June 2005 in its report entitled " Poser over Worldwide's partner " (note the parts in red italic):

On the face of it, Worldwide Holdings Bhd's success in securing two privatisation waste management deals from the Selangor government should have brought much cheer to its shareholders. Not only will the company be building a waste transfer station in Shah Alam and a waste landfill in Sepang, but it also has the concessions to operate these for 25 years. This means that Worldwide will get the construction profit as well as a steady revenue stream from operating the facilities.

What is even more interesting about the deal is the role of Worldwide's 30% partner in the waste transfer project. The company says the waste transfer project will be undertaken by its newly acquired 70% subsidiary Panorama Worldwide Sdn Bhd. Little-known Kekal Positif Development Sdn Bhd holds the remaining 30%.

With Worldwide and Kekal Positif having a stake in Panorama, one would expect both parties to finance the construction of the waste transfer station, where the amount of capital to be injected is determined by their share of ownership in Panorama. However, that is not the case.

When announcing the deals two weeks ago, Worldwide explicitly stated that "the cost of the (waste transfer station) project shall be solely financed by WHB (Worldwide)". {Is this the so called professional management?}

Market observers are puzzled. "As a shareholder in Panorama, why is Kekal Positif not putting up its portion of funding for the construction of the waste transfer station? Why is Worldwide fully financing the deal?" they ask.

Another pertinent question is: why were the privatisation awards not given directly to Worldwide, which is controlled by the (Selangor) state government? {not hanky panky?}

Worldwide did not reply to queries from The Edge.

Vital information that would interest shareholders was conspicuously missing in Worldwide's announcement. The company did not explain why it was solely financing the waste transfer station project nor indicate the cost. There was no information on the business nature of Kekal Positif, and more importantly, who controls the company.

"If it does not have to provide the capital, what exactly is the role of Kekal Positif and its input in the project?" asks a market observer.

Waste transfer stations are facilities where municipal solid waste is unloaded from collection vehicles and briefly held while it is reloaded onto larger long-distance transport vehicles for shipment to landfills or other treatment or disposal facilities.

Meanwhile, the inert waste landfill project will be undertaken by another newly acquired company, WL Environment Sdn Bhd, which is wholly owned by Worldwide Landfills Sdn Bhd -- a 60% subsidiary of Worldwide. The landfill project is being financed solely by Worldwide Landfills, which is expected because it owns all of WL Environment.

That Worldwide was able to secure the two privatisation deals from Selangor is not surprising because the state government controls Worldwide via the Selangor State Development Corporation (PKNS), which holds 89.83 million shares or a 52.55% stake. The second largest shareholder, with a 5.85% stake, is another Selangor government-controlled listed company, Kumpulan Perangsang Selangor Bhd. The Employees Provident Fund holds 3.62%.

The privatisation deals were initially awarded to Panorama Worldwide and WL Environment, after which they were acquired by Worldwide. "The intermediary parties will increase the cost of the transfer station and landfill projects," say market observers. {money is passed to the orang tengah}

According to filings to the Companies Commission of Malaysia, Kekal Positif is controlled by 37-year-old Wan Aminuddin Wan Daud, who holds 10,000 of the company's 25,000 shares of RM1 each. He is neither a board member nor part of the senior management team in Worldwide.

Adnan Che Mud and Setu Ahmad each hold 6,250 shares in Kekal Positif. Mohd Noor Jaafar holds 2,498 shares while Haslina Mohammed Fesal Arbee and Suzlita Nasron hold a share each. None of them sits on Kekal Positif's board. The five directors -- Noor Suhaila Saad, Mohd Rizal Ramli, Mohammad Rizal Abidin, Khairul Anuar Shaharudin and Mohamad Nizam Yaacob -- are all in their early 30s.

Kekal Positif, which states its nature of business as "housing developers and general traders", was registered in April 2001.

Corporate Information on Worldwide Holdings Berhad (WHB)

WHB was registered on 29 December 1965 and its present paid up capital is RM170,159,405. Its latest accounts filed with the Companies Commission of Malaysia shows it has fixed assets of RM202,579,562, current assets of RM193,919,775 and investments of RM295,769,245. Its total assets is RM665,818,555 against liabilities of only RM30,460,563.

That can be considered a healthy balance sheet. WHB's accumulated profit is RM377,879,794.

The Directors of the company are mostly politicians, all nominees of the state government while its major shareholder is PKNS (89,835,590 shares), EPF (6,184,600), and many bank-owned and investment nominee and trustee institutions,
ECM Libra being one of them that holds 1,111,000 shares.

Well, that is the story of Worldwide Holdings Berhad, the flagship of PKNS, indah khabar dari rupa (the news in prettier than the picture). And that is the good news, mind you. In part 3 we shall look at the bad news. And yes, there are plenty, so stay tuned."

http://malaysia-today.net/reports/2006/02/part-2-pkns-indah-khabar-dari-rupa.htm

Moola: 10.03 pm March 16th

saw this article: Worldwide Pt 2 – assured earnings, undervalued assets

  • Valuation & financials

    Worldwide has stayed consistently profitable and its balance sheet is strong, helped by a series of asset disposals, which include a hotel and office building in 1999 for RM101.3 million and most recently, Kuala Lumpur’s Holiday Inn on the Park hotel for RM55 million in 1Q2003.

    As at March 2003, Worldwide has net cash totaling RM15.5 million. For the first three months of this year, pre-tax profit rose to RM35.7 million from RM15.8 million, mainly from an exceptional one-off gain of RM18.7 million from the Holiday Inn disposal and higher waste management earnings. Net profit was RM29.9 million, or 17.9 sen per share, in the first quarter.

    We estimate Worldwide’s full year EPS, excluding exceptional items, to be around 29 sen per share. At the current share price of RM1.95, that translates into an equivalent P/E of just 6.7 times – less than half the market’s average and Malakoff’s 8-9 times. Including exceptional gains, full-year EPS is likely to come in at around 40 sen.

    Pay for power, rest comes free

    Apart from low P/E valuations, Worldwide is also trading at a significant 46 percent discount to their NTA of RM3.64 per share. Its NTA itself is understated due to the increase in value of the company’s two main assets, Genting Sanyen and the Subang Bestari.

    The Genting Sanyen stake is carried in Worldwide’s balance sheet at RM271 million. Malakoff’s 1,715MW capacity is currently valued by the stock market at RM2.25 million per MW. Applying this to Genting Sanyen’s 740 MW capacity, Worldwide’s 20 per cent stake should be worth RM330 million. This represents a surplus of RM59 million or 35 sen per Worldwide share.

    Ironically, Worldwide’s entire market capitalization stands at just RM325 million – equivalent to the value of Genting Sanyen. So, investors are effectively just paying for the IPP – with no value ascribed to Worldwide’s properties and others assets.

    Land at Subang Bestari is carried in Worldwide’s books at just RM2.40 psf, but is worth much more. For example further down the same Batu Tiga-Sungei Buloh road, Amcorp’s leasehold Kayangan Heights is selling bungalow lots for RM30-40 psf. Leasehold land in upmarket privatized developments in Kota Damansara are going for RM75-90 psf.

    Assuming a revaluation to just RM10 psf, Worldwide’s remaining 280 acres would be worth RM122 million, instead of a book cost of RM29.2 million. The surplus of RM92.8 million is equivalent to 55.6 sen per share. These two factors alone could add a potential surplus of 90.7 sen to Worldwide’s NTA, raising it by 25 per cent to RM4.54 per share.

hmmm... that article was posted 27th June 2003.

Kinda dejavu...back in 2003, price of Worldwide 1.95, low PE (6.7x!), discount to NTA...

now March 2006... err... same old, same old... !!

Read more...

Value or Value Trap in Worldwide Holdings? Part II

Wednesday, March 15, 2006

Cont...

Here's an interesting issue.

Say I Ass-u-me (LOL!!) that one purchased Worldwide Holdings Bhd back in Sept 2004 as per the article suggested at a price of 2.04.

Reasons?

Low price earnings multiple (6x), 50% discount to its NTA of 3.91 and with a cash balance of 83 million or a cash per share of 48 sen.

Let's look at the end result if one had invested in Worldwide at a price of 2.04.

Present day. March 2006. Worldwide is now trading at a price of 1.89. (ps. last May, Worldwide was trading as low as 1.71)

How do you rate such an investment? And how do you rate investing based soley on yardsticks?

Present day.. Worldwide announced its earnings on 28th Feb 2006.

Quarterly rpt on consolidated results for the financial period ended 31/12/2005

Its total earnings for fy 2005 was 50.708 million versus fy 2004 total earnings of 52.632 million.

Another sluggish performance.

And what was Genting Sanyen Power earnings contribution to this group? 57.641 million.

And again... don't you wonder what's happening in this listed company?

Crudely put.. some might even question what the management is paid to do!

Here's the value poser again... :D

Worldwide now trades at a price of 1.89.

And at 1.89, Worldwide is trading at a price earnings multiple of only 6.5x based on its trailing twelve months earnings.

Worldwide is still trading at a huge discount to its NTA.

Worldwide cash per share yardstick has risen to a whopping 72 sen per share. (cash at piggy bank now stands at some 124.382 million as reported in their Feb quarterly earnings)

How brown cow?

Still interested in considering Worldwide as a value stock?

At 1.89... you want onot?

Or do you really think this is a value trap?

~~~~~~~~~~~~~~~~~~

here's some comments from hhc:

For worldwide...

1) Management.
0/10. With so many hanky panky deals ongoing, i dont trust its board. If not of genting sanyen, worldwide will be in PN4 long time ago

2)Growth
0/10. Do u see growth? Do u see what is the future growth sector for worldwide? Nile,zero, nothing.

3)Div yield
Peanut in this case even though they can afford much more

4)Cash per share
8/10. Great to boast that u in a business with lot of cash in hand. But to have the cake and eat it is totally impossible. The best thing is , u will never know when the cash will be depleted (pumped into funny oversea venture with no return, remember epic in canada).

5)PE
2/10 If u look at worldwide as Property dev, then its PE is terrible. It doesnt make much (or any) money in Pro even with cheap land. Wonder do the board knows how to calculate?
AS for genting sanyan, it's saturating and one off good luck event for Worldwide. Dont expect another deal like this soon.

6)Liquidity
4/10. Not heavy tradinf volume and not volatile in its share price. Even the syndicate finds it hard to push the stock. Too lousy story to sell.

Overall: Avoid. the reward just doesnt correlate with the risk involve. I will try in Genting casino instead. At least i got the free drink.

~~~~~~~~~~~~~~~~~~~

how? Got any comments to share?

Read more...

Value or Value Trap in Worldwide Holdings?

Back in 2004, I was mumbling on Worldwide Holdings. Now I am just curious of the outcome if I were to make another review of it. My new comments will be in red.

29th May 2004.

Quarterly rpt on consolidated results for the financial period ended 31/3/2004

From the quarterly earnings notes, it was reported that the power generation business contributed a net profit of 14.407 million to Worldwide's earnings... and guess what? Worldwide's total net profit for the quarter only stood at 12.454 million.

Er... don't you wonder what is happening in Worldwide?

So if one takes away the Genting Sanyen Power earning contributions, you would get a company that's losing money! Speaks volume of the company's management doesn't it? And to compound the matter worse, Worldwide's stake in Genting Sanyen is only the minority stake. How? How would one evaluate the issue of shareholding risk?

Anyhow, what ails this bugger?

Look at the profit & loss statement... look at the big jump in operating expenses. (28.8 million vs 19.2 million last year)... What is happening here?

Then you have shrinking piggy bank cash (67.4 mil vs 85.7 mil last year) and you also have raising trade receivables (38.7 mil vs 29.9 mil last year)...

And what does the company says about its prospects?

  • As the outlook for the property development sector remains favourable the management is confident in registering profits in the current year.

    Continuous stable earnings from the Group’s investment in its power generation sector is expected to help maintain the Group’s profitability throughout.
how? Company insists that the property development sector will remain favourable wor and is confident in registering profits! LOL!.. what a joke of a statement. Surely Shirley that any decent management is capable of registering profits, isn't it? So if a company management has to declare this issue openly, won't you have any doubts over the company's ability to perform?

So do you reckon that Worldwide is value or perhaps Worldwide is nothing but a value trap?

==> That was May 2004...

Sept 18th 2004. Worldwide is now trading at 2.04.

There was an article in the star newspaper suggesting that Worldwide Holdings was worth a re-look. Here are some highlights from that article.

  • PROPERTY developer Worldwide Holdings Bhd (WHB) may be worth a re-look now that it has regained some ground in recent weeks, after falling for eight months and sinking to a 14-month low of RM1.70 on Aug 24. The counter, which has lost 13.2% year-to-date, closed at RM2.04 yesterday for a two sen gain. WHB shares currently trade at a price/earnings ratio of only six times on this year's annualised earnings, and at a 50% discount to its net tangible assets per share of RM3.91, said SBB Securities Sdn Bhd.
    WHB, 53% owned by Perbadanan Kemajuan Negri Selangor (PKNS), has a solid balance sheet, with a net cash position of RM83mil or 48.6 sen per share. And the proposed sale of its loss-making theme park operation in Sydney, Australia, for RM56mil cash is expected to boost the company's cash reserves to almost 81 sen a share.
    The property development arm, its main revenue contributor, accounted for 67% of turnover in the first half of the financial year ended June 30, but contributed only RM2mil to group pre-tax profit of RM40mil during the period.
Wahhh.... very strong article... pointing out so many strong points...
Sooo.... is Worldwide worth a revisit? Why not take a look?
This is their latest earnings...

Quarterly rpt on consolidated results for the financial period ended 30/6/2004


So the very first statement...


  • WHB shares currently trade at a price/earnings ratio of only six times on this year's annualised earnings, and at a 50% discount to its net tangible assets per share of RM3.91, said SBB Securities Sdn Bhd.
This tells the valuation... it does not tell the QUALITY of the company. Perhaps we should check the quality of the company. Is it a good company? Or an average company? Or a Lousy company?

If we dun check the Quality..... what is the use of buying it at a cheap price?

The theory of buying only good companies at a cheap price is a rather commonsense business thinking right? As an investor, what do we want? Don't we only want the best? Equate it to properties. Do we want to buy a lousy property at a cheap price? Surely Shirley wants only the best property at the best price, right?

Soooo... take a look at the track record.... track record are always very important... say if you look at a company's last 5 year history... and if the track record is rather unexciting, doesn't commonsense suggests that perhaps the next 5 years to be unexciting too?

here is Worldwide performance since 1999... how would you rate it?


Does this look like a company with a exciting prospect? It's profitability looks very impressive right? look at those margins... !! But sometimes looks can be very deceiving! Remember the issue that Worldwide's earnings is boosted by its share of 20% in Genting Sanyen Power? If that is the case, perhaps one might want to do a new table with a column indicating this share of profit from Genting Sanyen... and of course add in a column indicating the net profit less Genting Sanyen's earning contributions!


What is one's impression of Worldwide now?

Isn't it clear that if one takes away the Genting Sanyen Power earning contributions, you would get a company that's losing money! And Worldwide would have lost money 3 out of the last 5 fiscal years!

And there is only one verdict here. Utterly poor performance from Worldwide management! Don't you wonder what the management is there for?

Any sign of improvement? From their last reported quarterly earnings, look at their property development, which was supposed to be their CORE business, is still losing money!!

So if one rate the QUALITY of the company to be lousy then what we really have is a lousy company selling at a cheap price! Interested?

Second issue...

  • has a solid balance sheet, with a net cash position of RM83mil or 48.6 sen per share.
Ahhh yes. That is a fact. Worldwide's piggy bank is pretty healthy. However... it still doesn't hide the fact that the management has no idea on how to make money.

Anyway, for companies with nice piggy bank(s), don't you want to know what the company does with the excess money, rite? Understanding their historical dividend payouts, would give one an understanding of what to expect, right?

in 2003... Worldwide paid 3 sen tax exempt... (paid in Aug 2003)
in 2004... Worldwide paid 5 sen tax exempt... (paid in July 2004)

Sooo..... you probably might be safe to ass-u-me that Worldwide will pay at least a 5 sen tax exempt next year....

Worldwide closed at 2.04.

So if Worldwide pays the equivalent amount in dividend... then investing in it will see a possible stock paying one a yearly dividend yield of around 2.5%... Err.... is this yield attractive?

Commonsene thingy. Is this the best available investment for our money? Surely, Shirley there simply has to be another better choice?

(ahh... die! Remember Never Say I Ass-U-Me! Did you see that I said 'you probably might be safe to ass-u-me that Worldwide will pay at least a 5 sen tax exempt for next year'? Well if one had invested in Worldwide in Sept 2004 at a price of 2.04, Worldwide actually paid a total gross dividend of 10 sen, or a dividend yield of 5%!... and in January 2006, Worldwide paid a 3.6 sen tax exempt + 2 sen less tax interim dividend!)

WOW! too long already... to be continued ...

Read more...

  © Blogger templates Newspaper by Ourblogtemplates.com 2008

Back to TOP